LIKE MARVEL VILLAINS, most fashion writers have origin stories. Mine began with a navy nylon Prada purse, salvaged from a Boston thrift store when I was a teen in the 1990s. Scuffed with black streaks and sagging, it was terribly beat-up. But I saw it as a golden ticket to a future, chicer self. No longer a screechy suburban theatre kid, I would revamp myself as sophisticated, arch, even aloof. The bag, I reasoned, would lead the way.
That fall, I slung it against my shoulder like a shotgun and marched into school, where a girl far more interesting than I was called out, “Hey, cool bag.” After feigning apathy —“I don’t know, you could use a Sharpie on a lunch bag and it would look the same”—we became friends. She introduced me to a former classmate who worked at a magazine. That woman helped me get an internship, which led to a job.
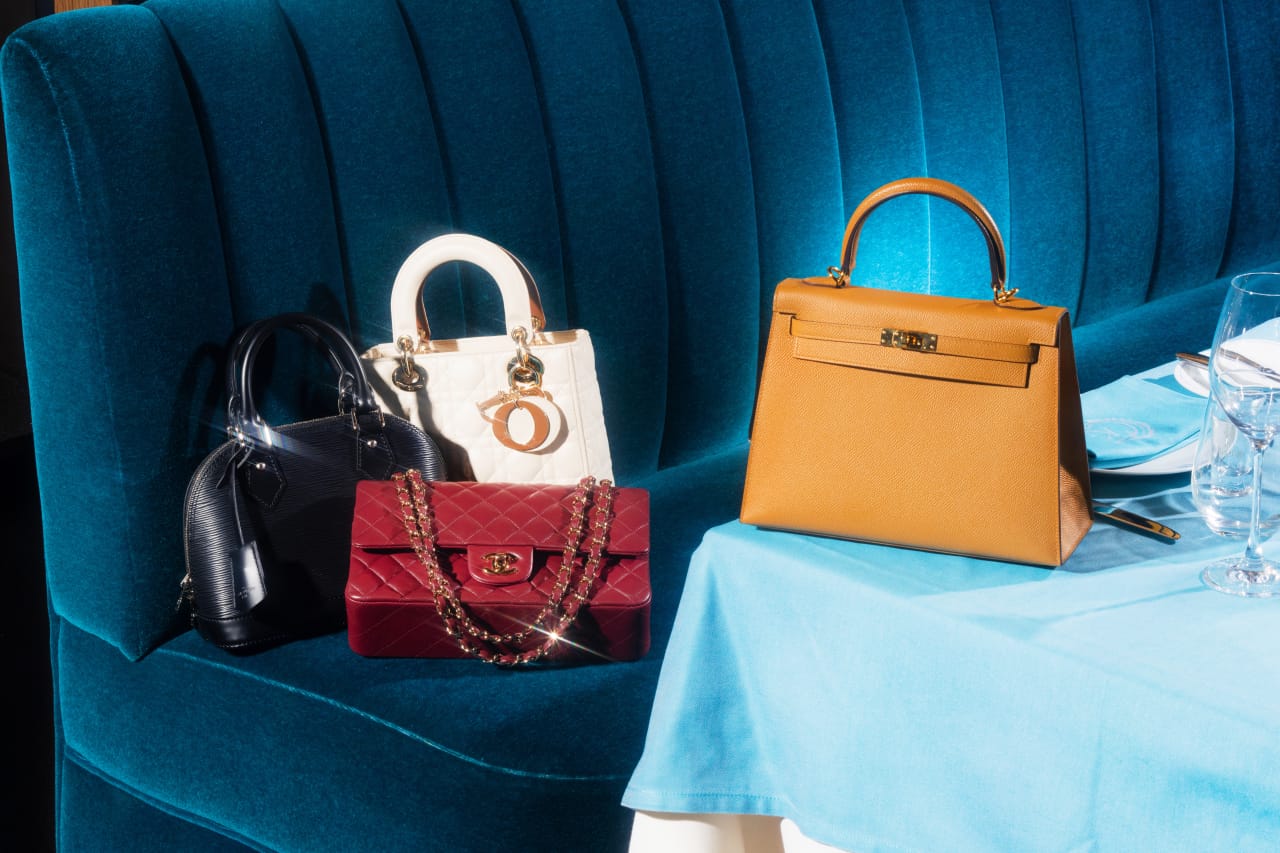
Twenty years later, I still wonder how big of a role that Prada purse played in my future—and whether designer bags can function as a silent partner in our success. Branded luxury bags took off in 1957, when Grace Kelly posed with an Hermès bag in Life magazine. (Hermès renamed that bag “the Kelly” in 1973.) The term “status bag” was popularised in 1990 by Gaile Robinson in the Los Angeles Times, describing any purse that projects social or economic power. Not surprisingly, these accessories are costly. Kelly bags cost over $10,000; ditto Chanel’s 11.22 handbag. Some bags by Louis Vuitton and Dior command similar price points. The cost isn’t repelling customers—both brands reported revenue surges in 2023. But isn’t there something dusty about the idea that a branded bag carries meaning along with your phone and wallet? How much status can a status bag deliver in 2024?
Quite a lot, said Daniel Langer, a business professor at Pepperdine University and the CEO of Équité, a Swiss luxury consulting firm. Beginning in 2007, Langer showed a series of photo portraits to hundreds of people across Europe, Asia and the U.S., then asked them 60 questions. Those pictured carrying a luxury handbag were seen as “more attractive, more intelligent, more interesting,” he said. The conclusion was “so ridiculous” to Langer that he repeated the studies several times over the next decade and a half. The results were always the same: “Purchasing a ‘status bag’ will prepare you to be more successful in your social actions. That is the data.”
Intrigued, I gathered various Very Important Purses—I borrowed some from friends, and others from brands—to see if they could elevate my station with the same unspoken oomph as a “Pride and Prejudice” suitor.
First, I took Alaïa’s Le Teckel bag—a narrow purse resembling an elegant flute case and carried by actress Margot Robbie—to New York’s Carlyle Hotel on a Saturday night. The line for the famous Bemelmans Bar stretched to the fire exit. “Can I get a table right away?” I asked the host, holding out my bag like a passport before an international flight. “It’s very busy,” he said in hushed tones. “But come sit. A table should open soon.” I sank into one of the Carlyle’s lush red sofas and sipped a martini while waiting—a much nicer way to kill 30 minutes than slumped against a lobby wall.
Wondering if this was a one-time thing, I called up Desta, the mononymous “culture director” (read: gatekeeper) who has worked for Manhattan celebrity hide-outs like Chapel Bar and Boom, the Standard Hotel bar that hosts the Met Gala’s official after party. “Sure, we pay attention to bags,” he said. “Not too long ago at Veronika,” the Park Avenue restaurant where Desta also steered the social ship, “we had one table left. A woman had a Saint Laurent bag from the Hedi Era,” he said, referencing Hedi Slimane , the brand’s revered designer from 2012 to 2016. “I said, ‘Give her the table. She appreciates style. She’ll appreciate this place.’”
Some say a status bag can open professional doors, too. Cleo Capital founder Sarah Kunst, who lives between San Francisco and London, notes that in private-equity circles, these accessories can act as a quick head-nod in introductory situations. Kunst says that especially as a Black woman, she found a designer bag to be “almost like armour” at the beginning of her career. “You put it on, and if you’re walking into a work event or a happy hour where you need to network, it can help you fit in immediately.” She cites Chanel flap bags made from the brand’s signature quilted leather and stamped with a double-C logo as an industry favourite. “People love to talk about them. They’ll say, ‘Ohhh, I love your bag,’ in a low voice.” They talk to you, said Kunst, “like you’re a tiger.”
For high-stakes jobs that rely on commissions—sports agents or sales reps, for instance—a fancy handbag can help establish credibility. “It says, ‘I’m succeeding at my job,’” said Mary Bonnet, vice president of the Oppenheim Group, the California real-estate firm at the centre of Netflix reality show “Selling Sunset.” As a new real-estate agent in her 20s, Bonnet brought a fake designer bag to a meeting. To her horror, a potential buyer had the real thing. “I work in an industry where trust is important, and there I was being inauthentic. That was a real lesson.” Now Bonnet rotates several (real) Saint Laurent and Chanel bags, but notes that a super-expensive purse could alienate some clients. “I don’t think I’d walk into [some client homes] with a giant Hermès bag.”
Hermès bags are supposedly the apex predator of purses. But I didn’t feel invincible when I strapped a Kelly bag around my chest like a pebbled-leather ammo belt. The dun-brown purse cost $11,800, a sum that prompted my boyfriend to ask if I needed a bodyguard. Shaking with “is this insured?” anxiety, I walked into a showing for an $8.5 million apartment steps from Central Park. I made it through the door but was soon stopped by a gruff real-estate agent asking if I had an appointment. No, but I had an Hermès bag? Alas, it wasn’t enough. The gleaming black door closed in my face.
“What went wrong?” I asked Dafna Goor, a London Business School professor who studies the psychology behind luxury purchases. “You felt nervous,” she replied. “That always makes others uncomfortable, especially in a high stakes situation,” like an open house with jittery agents. Goor said recognisable bags from Louis Vuitton and Christian Dior are also often faked, which can lead to suspicion if not paired with “other signals of wealth.”
“You can’t just treat a bag as a backstage pass,” said Jess Graves, who runs the shopping Substack the Love List. Graves says bags are more of a secret code shared between potential connections. “I’ve been in line for coffee and a woman will see my Margaux [from the Row] and go, ‘Oh, I know that bag.’ Then we’ll chat.” Graves moved from Atlanta to Manhattan in 2023, and says she’s made some new, local friends thanks to these “bag chats.”
I had my own bag chat that night, when I brought Khaite’s Olivia—a slim crescent of shiny maroon leather—to a house party thrown by a rock star I’d never met. In fact I knew hardly any guests, but as I stood in the kitchen, a woman in vintage Chanel pointed to my bag and asked, “How did you get that colour? It’s sold out!” Before I could tell her my name, she told me the make and model of my purse. Then she laughed about her ex-boss, a tech billionaire, and encouraged me to buy some cryptocurrency. The token I picked surged nearly 30% in about a week. Now I was onto something—a status bag that might bring not just status, but an actual market return.
Thanks to their prominence on social media, certain bags have gained favour among Gen Zers. “TikTok and Instagram make some luxury items even more visible and more desirable to young people,” said Goor. I experienced this firsthand on a stormy Saturday morning, when a girl in a college hoodie pointed at my Miu Miu Wander bag as I puddle-hopped through downtown New York. The piglet-pink purse is a TikTok favourite seen on young stars like Sydney Sweeney and Hailey Bieber. “Your bag is everything!” yelled the girl from the crosswalk. “Thanks, can I have your umbrella?” I shouted back. She laughed and left. My Wander had made a splash—but it couldn’t keep me dry. I ran to the subway, soaked. The bag looked even better wet.
Changing the Status Bag Quo
Everyone loves an ingénue—fashion insiders included. Perhaps that’s why at Paris Fashion Week in September, newer handbags from Bottega Veneta and Loewe jostled for space and street-style flashbulbs.
“These bags, especially ones by independent labels like Khaite, are quieter signals of cultural access,” explained Goor. “Everyone knows what an Hermès Kelly bag is. So now there need to be new signals” beyond traditional status bags to convey power.
Sasha Bikoff Cooper, a Manhattan interior designer, says there’s a less cynical explanation for why these bags have captured celebrity fans—and more important, paying customers. “They’re fresh and also beautiful,” she said. “Hermès is always classic. It’s like a first love. But you want newness, too.”
The Wall Street Journal is not compensated by retailers listed in its articles as outlets for products. Listed retailers frequently are not the sole retail outlets.


 6 min
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide.



