
General Motors And Other Car Makers Have Big EV Goals. Why The Numbers Make No Sense.

By Al Root
Fri, Feb 5, 2021 5:40am 4 min
4 min

 4 min
General Motors shook up the car industry this past week, saying it is aiming to stop selling gasoline-powered cars by 2035, much sooner than many on Wall Street would have predicted.
It is a sign that analysts and investors should be sharpening their pencils to figure out what is likely—and what is possible—for global electric-vehicle demand. The results of that number crunching will help to show whether the market has valued highflying EV stocks correctly and which, if any, still offer good value.
It isn’t an easy equation to solve. Auto makers express their goals—one indication of what might happen in the market—in different ways.
General Motors (ticker: GM) has its target for 2035. Tesla (TSLA) CEO Elon Musk has talked about selling 20 million EVs by 2030 and plans to increase its production volume at 50% a year for the foreseeable future.
Volkswagen (VOW. Germany) wants up to 25% of vehicle sales to come from battery-powered electric vehicles by 2030. And Toyota (TM) plans to sell 5.5 million electrified vehicles by 2030—a figure that includes hybrid electric cars as well as fuel-cell vehicles.
Barron’s added up the numbers in the publicly announced goals, aligning them by year and filling in some gaps. We calculate that, based on company comments, somewhere between 15 million and 20 million EVs will be sold a year by 2025. That implies an average annual growth rate of about 50% between last year and then. With that growth, EVs would account for roughly 15% to 20% of total light-vehicle sales.
Wedbush analyst Dan Ives qualifies as an electric-vehicle bull, but his estimate of EVs’ share of the market isn’t that high. “I am laser-focused on the skyrocketing EV demand out of China, Biden green initiatives, and [battery innovation] across the EV supply chain,” he tells Barron’s. “It looks like a golden age for EVs.”
Still, he is assuming EVs will win about 10% of the global market by 2025.
Focusing on China is a good idea. It’s the largest new-car market in the world and government incentives make buying an EV a “no brainer” for most consumers, according to Ives. Goldman Sachs analyst Fei Fang has predicted EVs will have 20% of the Chinese market by 2025.
RBC analyst Joseph Spak recently projected battery- and hybrid-electric vehicles could account for roughly 15% of new-car sales by 2025. That call was made back in December, before GM announced its aspiration to be all-electric by 2035.
Now Spak believes his projection could be too low. He did his own math to illustrate why.
“GM historically has had [about] 17% total U.S. market share,” he wrote in a recent research note. In December, he expected EVs to account for 40% of U.S. new-car sales by 2035. But for GM to go all-electric by then, assuming it keeps its historic 17% of the market, it would have to win 43% of U.S. EV sales, he said.
“The other way to interpret this [math] is that there could be upside to our 40% [battery electric] mix assumption,” added the analyst. That would be bullish for EV stocks, but he has a word of caution too. “A massive ramp in battery supply is needed to support this,” he said.
That gets at another important point for investors. There are many tertiary effects from faster EV penetration.
For one, as EVs take a bigger share of the market, they will start to get more of the capital the industry is willing to spend on product development. GM, for instance, is spending about half its capital over the next few years on EV and autonomous-driving technologies. By 2030, cars powered by internal combustion engines—ICE cars, in industry jargon—won’t look as attractive, relatively speaking, as those programs are drained of resources.
Electricity infrastructure is another critical issue. Right now oil and the refining industry essentially power cars. In the future, utilities and the electric grid will bear the burden.
The math needed to predict global electricity demand is harder, but higher EV penetration in 2025 would probably boost growth, now at roughly 3% a year, by a couple of percentage points. That seems manageable, but it means more investment in utilities.
The other side off the electricity equation is oil. Oil demand could fall slightly compared with 2019, a pre-pandemic year, if the world’s pool of EVs grows faster than expected. There are roughly 2 billion light vehicles on the road and nearly all take gasoline.
The next step in this math class is to value the EV sector. That isn’t easy either.
Given the growth and accelerating penetration, figures for 2025, when EV companies should be making real money, seem like a reasonable place to start. Apple (AAPL), the world’s most valuable company, trades for about 19 times estimated 2025 cash flow of about $120 billion.
Tesla is trading for about 65 times estimated 2025 cash flows. That is triple the figure for Apple, although if Musk’s goals are met, Tesla’s annual sales will go from more than 4 million vehicles to about 20 million over the next five years—between 2025 and 2030.
China’s NIO (NIO) is another highly valued EV stock. Analysts haven’t made public projections for its 2025 financials. But its shares trade for about 30 times estimated 2024 cash flow. According to analysts, NIO vehicle shipments are expected to go from roughly 345,000 to about 800,00 from 2025 to 2030. That is less growth than Tesla is looking to produce, but it still implies sales would more than double.
The 2025 valuation math can’t tell investors to buy or sell the stock, or the sector, but it does offer context about the coming golden age of EVs. Tesla stock is up about 21% year to date. NIO shares are up almost 19%. The S&P 500 is up about 2%.
Investors expect a lot. Morgan Stanley’s Adam Jonas pointed out that January EV sales in the U.S. were still less than 3% of the total, but he isn’t an EV bear. He rates Tesla stock at Buy and has a target of $880 for the stock-price target.
The ICE Age is ending. If the switch to EVs is rapid, valuations for manufacturers might not be unreasonable. The effects on other industries are just starting to be felt.
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
AI-powered travel agents are challenging online booking platforms, but Airbnb’s exclusive listings and direct customer relationships could give it an edge. Its next challenge: turning repeat guests into loyal customers through stronger rewards and innovation.
3 min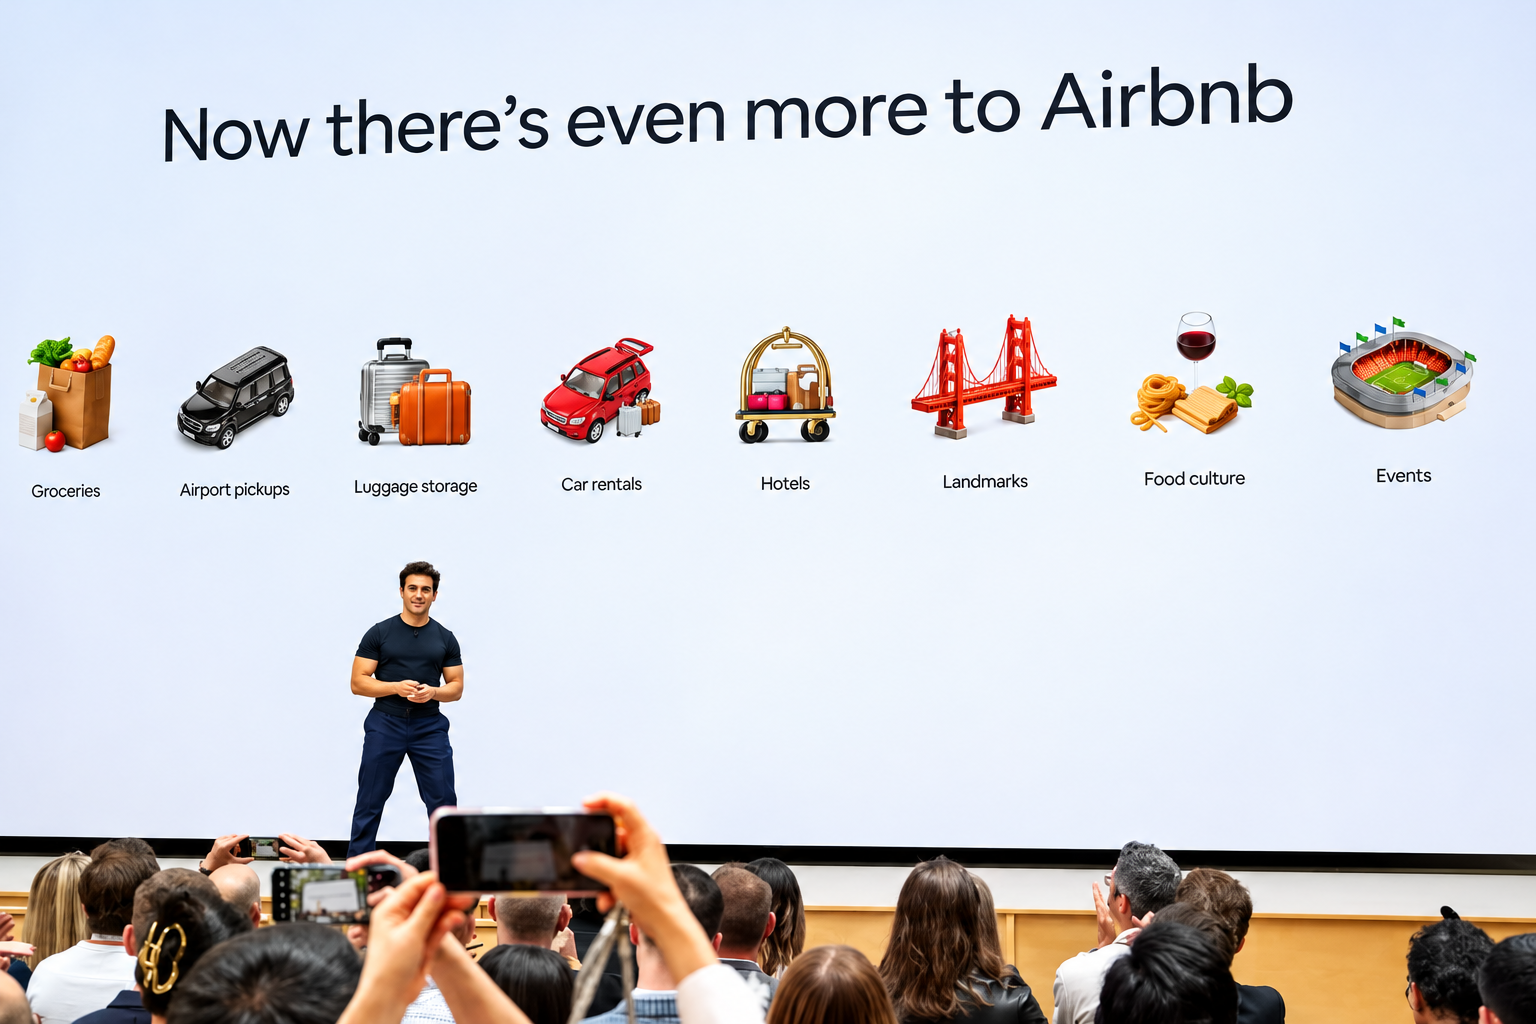
AI agents like Muse can already find you the cheapest hotel room in Paris. But they can’t locate a cheaper version of that Catskills cabin you’ve been eyeing, because it might only be available on Airbnb ABNB -1.43%decrease.
Investors should pay attention to that distinction. When Meta Platforms META 3.38%increase launched its Muse agent last month, travel stocks including Booking Holdings BKNG -1.19%decrease, Expedia and Airbnb all fell sharply.
Airbnb, though, has a real chance to emerge as a winner from the upheaval. The catch: Its stock already reflects above-industry growth. To justify its valuation, Airbnb will need to turn repeat customers into loyal ones.
Online travel companies make much of their money by simplifying search and collecting fees on bookings. AI agents threaten that model.
But not all travel marketplaces are equally exposed. Booking and Expedia largely sell hotel rooms that travelers can also book directly or through competing sites. If an agent can find the same room elsewhere, it has little reason to favor either Booking or Expedia.
Booking and Expedia also sell sponsored listings that steer travelers toward particular properties. Wells Fargo estimates those will account for about 8% of Expedia’s revenue and a much higher percentage of profit next year.
Airbnb has more ways to adapt. More than half its listings are available only on its platform, and more than 90% of its traffic comes directly to its app or website.
The customer relationship doesn’t end after booking, either. Bernstein analyst Richard Clarke notes that 90% of Airbnb guests go on to message their hosts about arrival times, keys or local taxes, giving Airbnb a connection to both sides of the transaction.
How the companies have responded to the possible agentic future is telling.
Expedia quickly signed on as a Muse partner. Airbnb hasn’t, and Chief Executive Brian Chesky says AI chatbots have so far been a boon, sending customers to Airbnb’s website.
Chatbots might work for buying paper towels, he quipped at a Skift conference last month, but people enjoy planning trips. He argued that browsing dozens of homes isn’t something a text-based chatbot is well suited for.
Still, the AI jitters arrived just as Airbnb was persuading investors it deserved its pricey multiple. For years after its 2020 initial public offering, the stock—which trades around 25 to 30 times forward earnings—went nowhere. Investors saw a mature operator trading at a growth premium.
This year, Airbnb growth seems to be accelerating. The stock jumped in August after the company raised its full-year revenue-growth guidance with its second-quarter results. Wells Fargo analyst Ken Gawrelski credits a run of product improvements under a revamped leadership team.
Among the changes: letting guests reserve now and pay later, adding hotels, and a redesigned home page and app. Investors were also betting on what comes next, including thousands more hotels, car rentals and, eventually, advertising.
The irony is that some of those growth drivers push Airbnb closer to the kind of business Booking and Expedia run—the kind of business AI agents could threaten. Even if AI agents capture a large share of travel planning and booking, Airbnb would capture the demand. But it and others would slowly lose control over how customers find and choose properties.
That would undermine the advertising opportunity investors are counting on. The bigger point for Airbnb and other marketplaces is that losing control of customer acquisition could mean surrendering some of their pricing power and margins.
To bulletproof itself, Airbnb might look to another e-commerce giant that has so far kept AI agents at arm’s length: Amazon.
Like Amazon, Airbnb has a loyal customer base and hard-to-match supply. But it has nothing like Prime membership to make customers think twice before taking their business elsewhere.
That is where loyalty comes in. Business travelers stick with Hilton or Marriott because enough nights earn them perks. Leisure travelers rarely accumulate stays with one chain. Airbnb has millions of listings and plenty of repeat customers, but no broad rewards program. It has begun experimenting with credits on hotel stays, but it should make loyalty a priority, not just a promotion.
Airbnb also plans to launch its own AI agent next year. But travelers using an agent might still want it to search Airbnb, Vrbo, Booking and hotel websites alike, rather than limit itself to one company’s inventory.
Eventually, Airbnb might have to strike deals with agent makers, using its unique homes as leverage to negotiate favorable terms, says Gawrelski. Such deals, along with rewards for loyal guests, could over the long term eat into the company’s roughly 13% take rate, he adds. But if they bring in enough additional bookings, the trade-off could be worthwhile.
History offers a reason not to panic. The shift from desktop to mobile unsettled investors in Alphabet and Amazon, but both emerged as major beneficiaries. Companies with valuable assets can come out of a platform shift stronger, if they adapt quickly enough.
Airbnb has homes the bots can’t easily replace. Now it needs to give guests a reason to insist on booking them there.
