In a Florida Town Ravaged by Storms, Homeowners All Want to Sell
Ballooning home insurance costs and the perennial threat of violent storms hit Tampa Bay housing market hard
By DEBORAH ACOSTA
Wed, Oct 2, 2024 9:06am 4min
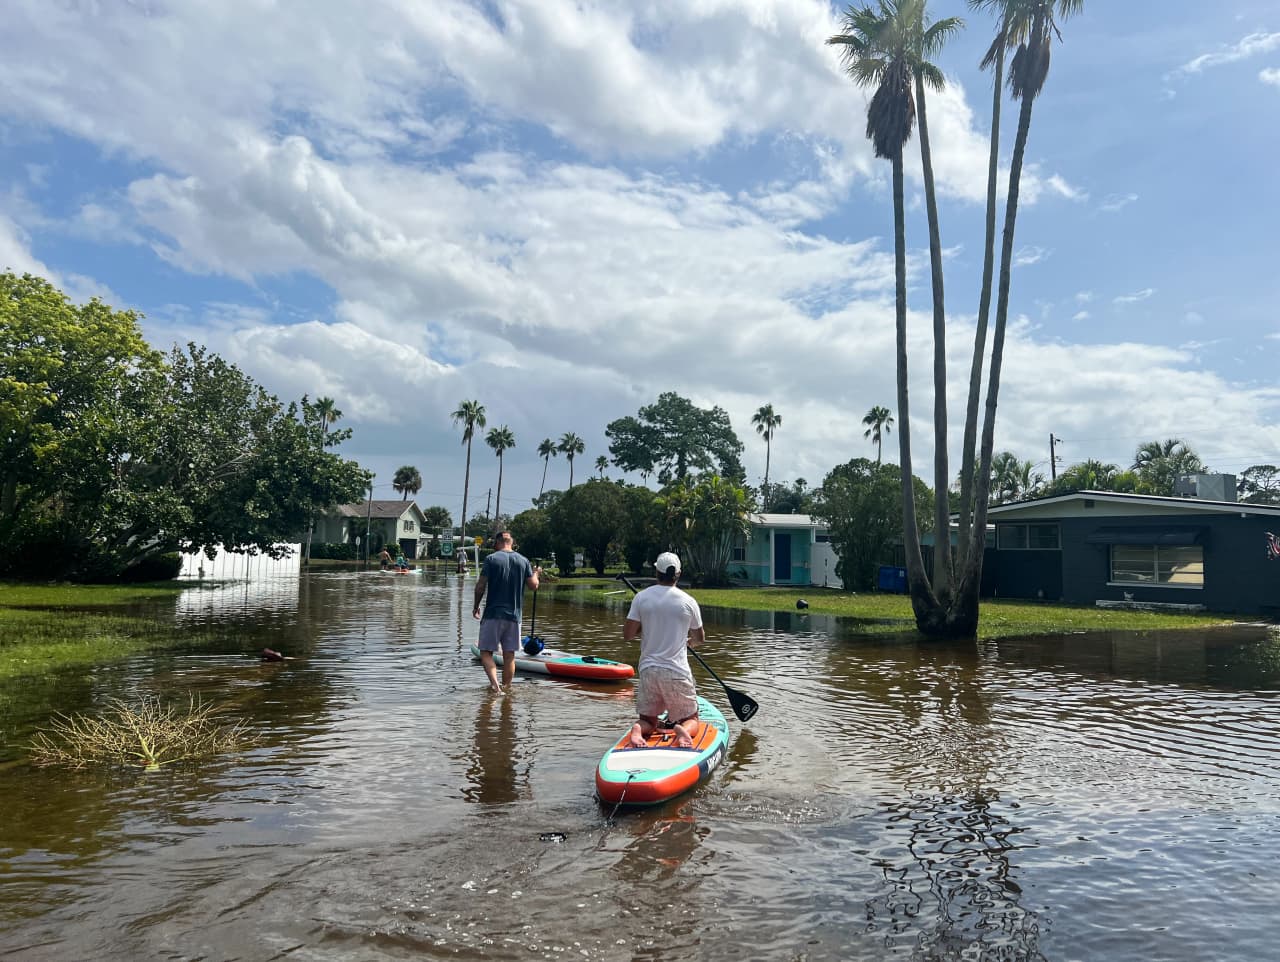
Dustin Pentz, kneeling, paddled to see his home for the first time in Shore Acres, a neighborhood that often floods in St. Petersburg, Fla. Photo: Deborah Acosta/WSJ
ST. PETERSBURG, Fla.—Kellen Driscoll bought his home here in 2019, settling in the coastal enclave of Shore Acres. It flooded for the first time four years ago after tropical storm Eta dumped more than 3 feet of water.
Hoping it was a fluke, Driscoll tore out the affected drywall and started fresh. After all, the four-bedroom home built in 1960 had no flood history.
But then it happened again, and again. Like many others in the community, he put his home up for sale in the spring of this year. After seeing little interest, he cut the asking price.
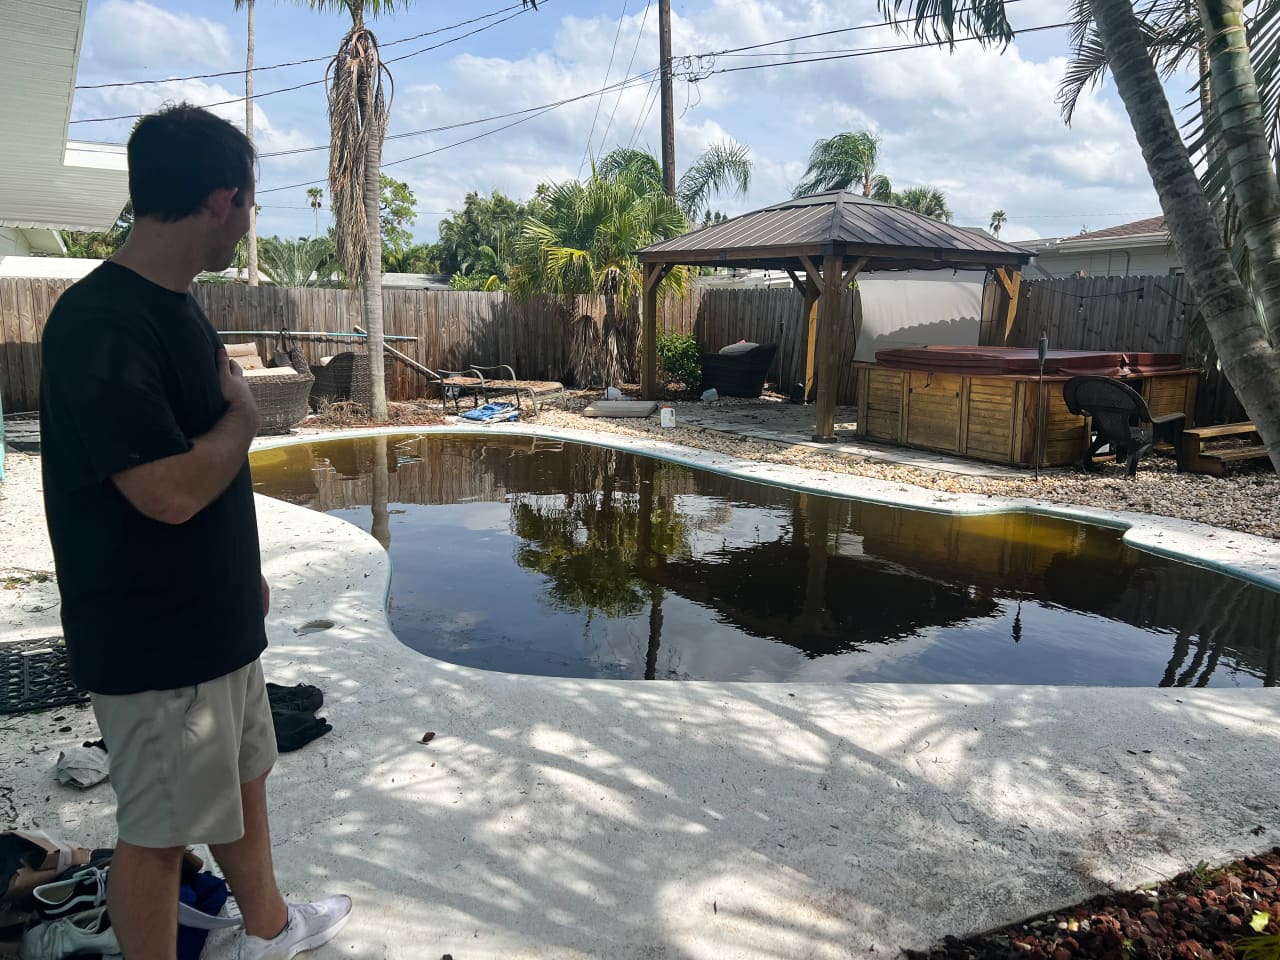
On Friday, Hurricane Helene deposited more than 6 feet of storm surge in the neighbourhood. The rushing waters ripped the “For Sale” sign off his front lawn, and etched a waterline that reached halfway up his front door, just underneath the doorbell. He reduced the asking price for a fifth time.
“We flooded here four times in the last four years,” said Driscoll, as he threw his television sets, furniture, appliances and other belongings to the curb. “I’m just hoping I can sell the house. It’s a good neighbourhood for sure, but dealing with the floods is horrible.”
When Kellen Driscoll purchased his home in 2019 it had no flood history. Since then his home, built in 1960, has flooded four times in the past four years. Photo: Deborah Acosta/WSJ
In the Tampa Bay metropolitan area, which includes St. Petersburg, a real-estate boom nearly doubled median home values from 2018 to June of this year, according to Redfin data. Young people flocked to the region, looking for a coastal lifestyle at a relatively affordable price.
The Tampa Bay metro area was the fifth most popular relocation destination in the country, according to an analysis by Redfin last year. The population has soared to more than three million.
But as Shore Acres’s young residents sorted through the storm’s wreckage, only one thing was on their minds: selling.
Ballooning home insurance costs and the perennial threat of violent storms are starting to undermine housing markets throughout much of the state. But in few places has the turnaround been more dramatic than in low-lying communities up and down the coast of Florida that frequently flood.
The Tampa Bay housing market had been softening even before Helene struck. While prices have been flat, the area experienced a 58% increase in supply in August compared with a year ago, and a 10% decrease in demand, according to Parcl Labs, a real-estate data and analytics firm.
About half the homes listed for sale in Tampa experienced price reductions as of Sept. 9, the third highest share of all U.S. major metropolitan areas.
“Tampa was already heading in this direction before the hurricane hit,” said Jason Lewris, co-founder of Parcl Labs. “This hurricane may compound the market dynamics that have been occurring there over the last few months.”
While Tampa escaped a direct hit from the eye of the hurricane, it was the worst storm to hit the area in a century. The hurricane also plowed into landlocked towns well north, causing heavy damage in the Carolinas where people were just beginning to absorb the scope of ruin.
‘Let’s roll the dice’
Bradley Tennant’s home flooded last year. But to avoid all the competition, he was waiting a year to put it up for sale.
“We saw the glut of homes for sale in the spring and thought, ‘What are the chances it’ll hit again the next year?’” said Tennant, as he cleared out the soaked contents of his waterfront home. “We went 50 years without a storm that flooded the house. So we thought, let’s roll the dice.”
While he paid around $350,000 for the house about seven years ago, Tennant says he received offers as high as $800,000 during the height of the market—before last year’s storm hit. Now he’s hoping to sell as soon as he’s able to renovate.
The area’s affordability, once a large part of its appeal, is also waning as insurance premiums soar. Jacob McFadden was paying $880 a year to insure his home when he bought it in 2020. That amount has since almost quadrupled, to $3,300.
Premiums will likely increase again now. Property damage from last week’s Category 4 storm could be as high as $26 billion, according to estimates from Moody’s Analytics.
“I don’t know how much longer I’m going to do this waterfront living,” McFadden said, standing in front of his home with a wheelbarrow and his home’s contents scattered around the front yard. “This may be the end.”
Dustin Pentz bought his home 10 years ago, and was one of the lucky few to avoid flooding. That is until Hurricane Helene. When police blocked his car from entering the neighbourhood, he paddleboarded his way home to assess the damage.
His fridge was knocked over, and the water reached up as high as his mattress. Unfortunately, his flood insurance doesn’t cover the contents of his home. A tree in his backyard fell over and hit the corner of his roof, but he was unsure that the damage would hit his $8,500 wind deductible.
“This neighbourhood’s amazing, great schools. But no one wants to deal with this all the time,” said Pentz. “It sucks because no one wants to live here anymore. There are so many houses for sale and no one’s buying.”
Working class squeezed
Down the street, Domonique Tomlinson and her husband, Leon Tomlinson, filed a claim for items they lost in last year’s flood. They didn’t want to go through the headache of filing another claim for the contents of their home this year, with a separate $5,000 deductible.
Two days before Hurricane Helene hit, they rented a moving van to haul many of their belongings to a storage unit. She bought her home four years ago for around $199,000. Because property values have increased so much in her area, she hopes to break even. But now she says she’s not so sure.
Tomlinson, who is a teacher, and her husband, who works as a manager at a grocery store, worry that people like them will be priced out of the area because they can’t afford the preventive measures and insurance.
“Basically the only people that are going to be able to live back here are rich people who can build up,” she said.
Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Following the successful launch of its Palais Collection, MAISON de SABRÉ has unveiled a new modular handbag system offering more than 720 styling combinations.
Related Stories
Property
A Modern Home in Silicon Valley Lists for $44 Million
By E.B. Solomont 24/09/2026
Property
$8.1 billion, 10,000-home community set for Dubai neighbour Sharjah
By Ruba Jaajaa 21/09/2026
Property
The 60-Year-Old Real-Estate Agent Giving History Lessons on Instagram
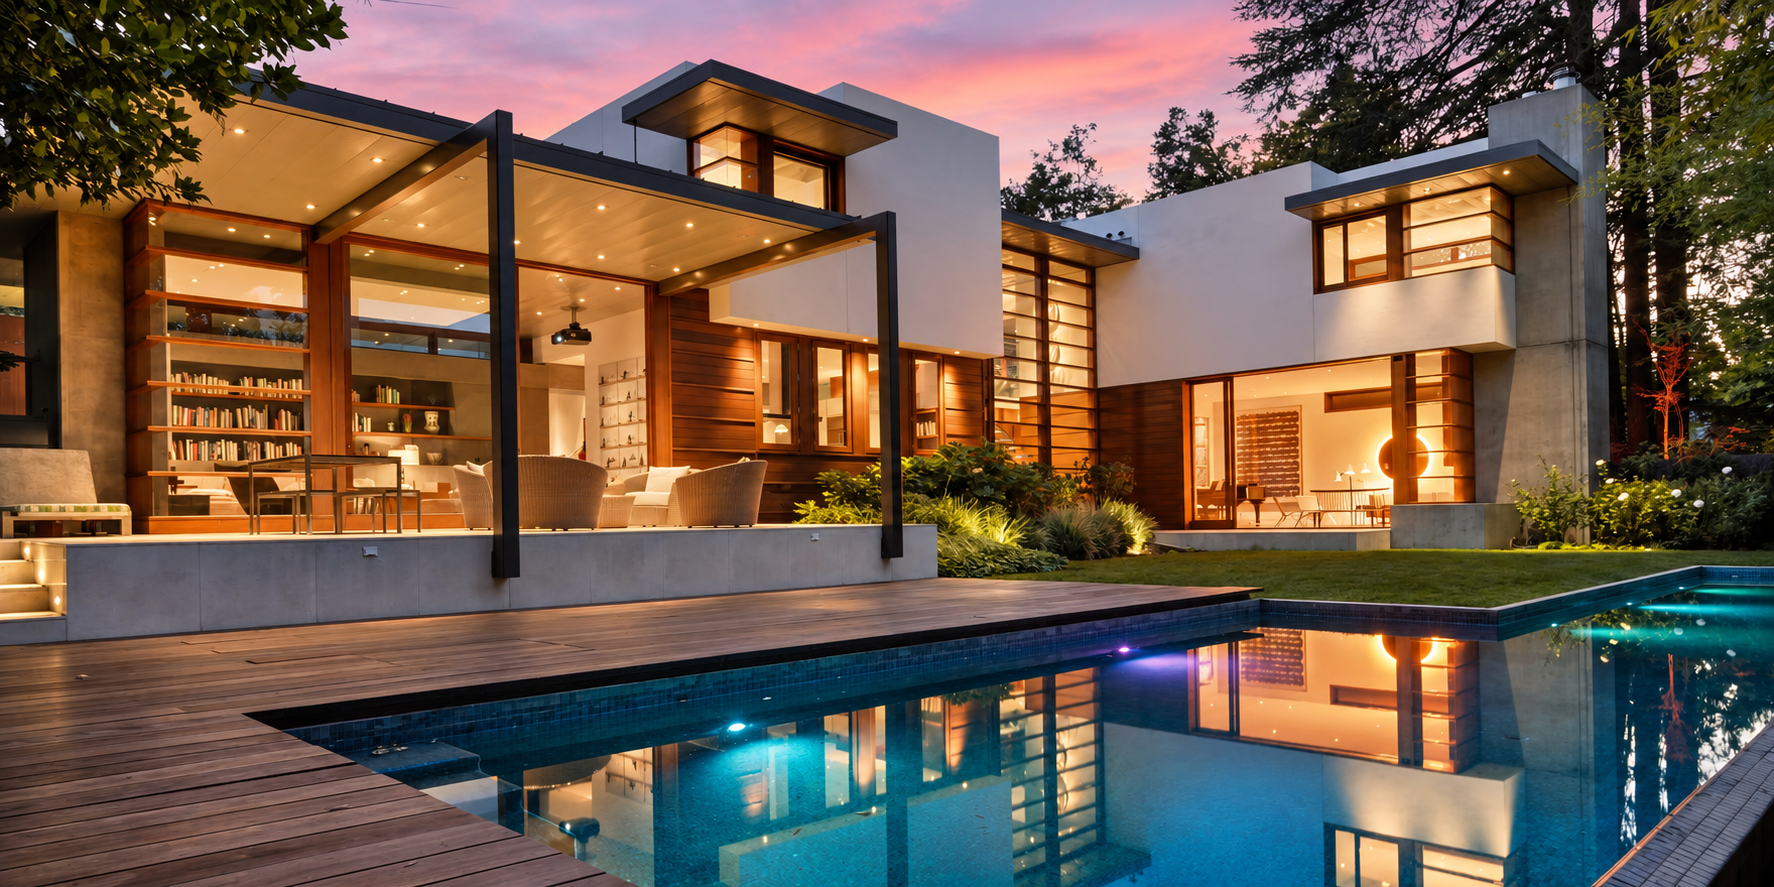
A five-bedroom Palo Alto home designed by Steven Ehrlich is listed for $44 million, making it the city’s most expensive listing. Built around a dramatic concrete spine, the home features four courtyards and a pool.
By E.B. Solomont
Thu, Sep 24, 2026 3min
For years, tech entrepreneur Asher Waldfogel and his wife, Helyn MacLean, dreamed of building a modern house in Palo Alto, Calif.
The couple, however, worried about clashing with the Mediterranean-style architecture typically associated with their neighborhood of Old Palo Alto.
So they tapped architect Steven Ehrlich to create a design that paid homage to its surroundings with stucco, mahogany and titanium zinc cladding. They spent $20 million over several years building the house, completed in 2005.
Designed for indoor-outdoor living, the house has matching mahogany paneling and limestone both inside and out. Arthur Sharif/Sotheby’s International Realty
The dining room is between an outdoor garden and the staircase. Arthur Sharif/Sotheby’s International Realty
Now looking to be closer to their adult daughter on the East Coast, they are putting the five-bedroom home on the market for $44 million—the most expensive listing in Palo Alto.
Waldfogel is an angel investor who co-founded Redback Networks, a telecommunications-equipment company. MacLean previously had a career in fundraising.
The kitchen and family room open to the garden and pool. Arthur Sharif/Sotheby’s International Realty
Cast alcoves and mahogany shelves house the couple’s books and ceramics. Arthur Sharif/Sotheby’s International Realty
The couple purchased the roughly 0.4-acre site for $7.1 million in 2000 and demolished a circa-1930s Spanish Colonial home. The house they built pinwheels around a central staircase. It has 7,900 square feet of livable space, with four distinct courtyards and a pool.
A key feature of the home is a cast-in-place concrete wall, or spine, that is two stories high and about 80 feet long. “There’s a little bit of controlled chaos in what comes out of the form,” unlike a perfectly uniform surface, Waldfogel said. “If you want that, you do it in plastic.”
Ehrlich said it took a few tries to get the concrete wall right. Arthur Sharif/Sotheby’s International Realty
‘It’s a really hard material to tame,’ Ehrlich said of concrete. Workers learned as they went, and Waldfogel and Helyn grew to appreciate the imperfect material. Arthur Sharif/Sotheby’s International Realty
A central staircase is housed in a glass tower. Arthur Sharif/Sotheby’s International Realty
Waldfogel said he and his wife are thinking about the next phase of life now that their daughter is grown, although they have not decided where they will move. They also have a home in Sun Valley, Idaho.
“Right now we’re just trying to emotionally let go and decide what to do next,” he said.
Arthur Sharif/Sotheby’s International Realty
Two wings of the house are connected by horizontal planes. Arthur Sharif/Sotheby’s International Realty
Palo Alto, an epicenter of venture capital and tech startups in Silicon Valley, is home to some of the country’s biggest tech titans. Sales volume and prices are rising, with a median sale price of $3.5 million for the three months ending in August, up 5.8% year-over-year, according to real-estate brokerage Redfin.
Arthur Sharif of Sotheby’s International Realty—San Francisco Brokerage has the listing.


 4 min
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide.