
Investing in Nature Is Gaining Traction. Will It Be Enough?

By ABBY SCHULTZ
Wed, Jan 10, 2024 9:57am 4 min
4 min

 4 min
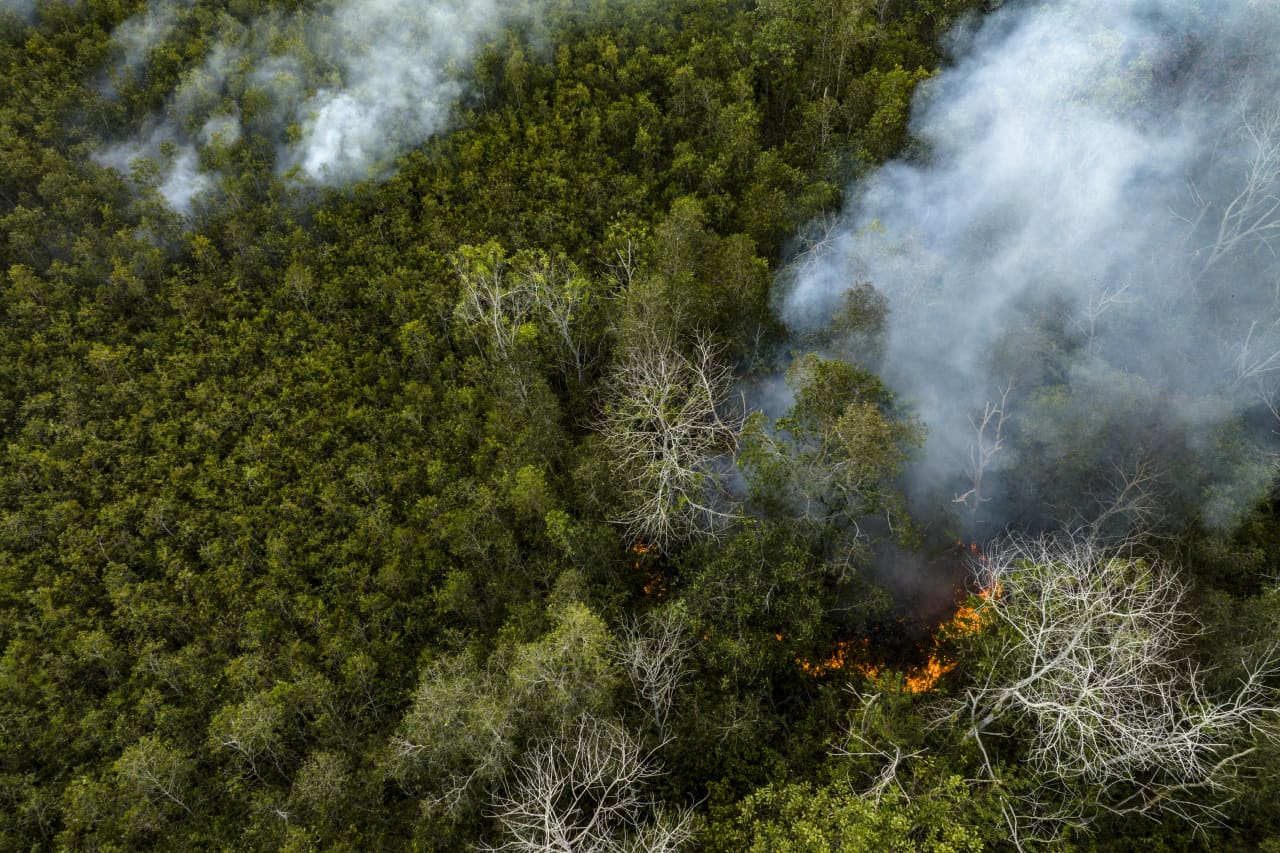
Investing in nature to address climate change, support biodiversity, and protect ocean health—and more—is expected to reach record levels this year in response to more regulation and market demand, according to Cambridge Associates, a global investment firm.
Still, the amount of private capital invested to support natural systems will fall far short of what’s needed, according to the annual “State of Finance for Nature” report published in December from the United Nations Environment Programme.
A big reason is that nearly US$7 trillion in public and private finance was directed to companies and economic activities in 2022 that caused direct harm to nature, while only US$200 billion was directed to so-called nature-based solutions, or NbS—investments that protect, conserve, restore, or engage in the sustainable management of land and water ecosystems, as defined by the United National Environment Assembly 5, or UNEA5, the report said.
“Without a big turnaround on nature-negative finance flows, increased finance for NbS will have limited impact,” it said.
But the report also said that the misalignment “represents a massive opportunity to turn around private and public finance flows” to meet targets set by the United Nations Rio Conventions on climate change, desertification, and biodiversity loss.
The conventions aim to limit climate change to 1.5 degree Celsius above pre-industrial levels, protect 30% of the earth’s land and seas by 2030, and to reach “land degradation neutrality” by 2030. Reaching those goals will require more than double the amount of current levels of nature-based investing by 2025, to US$436 billion, and nearly triple today’s levels to US$542 billion by 2030, the report said.
Most of the US$200 billion invested in NbS today is by governments, but private investors contributed US$35 billion—including US$4.6 billion via impact investing funds and US$3.9 billion via philanthropy. The largest source of private finance was in the form of biodiversity offsets and credits. [An offset is designed to compensate for biodiversity loss, while a credit is the asset created to restore it].
Many wealthy individuals and families concerned about climate change and the environment so far have focused their investment dollars on climate solutions and innovations in technology and infrastructure, or in technologies supporting food and water efficiency, says Liqian Ma, head of sustainable investment at Cambridge Associates.
But “increasingly there is growing awareness that nature provides a lot of gifts and solutions if we prudently and responsibly manage nature-based assets,” Ma says.
Investments can be made, for instance, in sustainable forestry and sustainable agriculture—which can help sequester carbon—in addition to wetland mitigation, conservation, and ecosystem services.
“Those areas are not in the mainstream, but they are additional tools for investors,” Ma says.
Finance Earth, a London-based social enterprise, is among the organizations working to make these tools more mainstream by creating a wider array of nature-based solutions in addition to related investment vehicles.
Finance Earth groups nature-based solutions into six themes: agriculture, forestry, freshwater, marine/coastal, peatland, and species protection. Supporting many of these areas are an array of so-called ecosystem services, or benefits that nature provides such as absorbing carbon dioxide, boosting biodiversity, and providing nutrients, says Rich Fitton, director of Finance Earth.
Each of these ecosystem services are behind existing and emerging markets. Carbon-related disclosure requirements (at various stages of approval in the U.S. and elsewhere) have long spurred demand for carbon markets, the most mature of these markets.
Cambridge Associates, for instance, works with dedicated asset managers who have been approved by the California Air Resources Board to buy carbon credits, Ma says.
In its annual investment outlook, the firm said California’s carbon credits should outperform global stocks this year as the board is expected to reduce the supply of available credits to meet the state’s emission reduction targets. The value of these credits is expected to rise as the supply drops.
In September, the G20 Task Force on Nature-Related Financial Disclosures released recommendations (similar to those put forward several years ago by the Task Force for Carbon-related Financial Disclosure) that provide guidance for how companies can look across their supply chains to assess their impact on nature, water, and biodiversity “and then start to understand what the nature-related risks are for their business,” Fitton says.
The recommendations will continue to spur already thriving biodiversity markets, which exist in more than 100 countries including the U.S. In the U.K., a new rule called “Biodiversity Net Gain” went into effect this month requiring developers to produce a 10% net gain in biodiversity for every project they create.
Though developers can plant trees on land they’ve developed for housing, for example, they also will likely need to buy biodiversity credits from an environmental nonprofit or wildlife trust to replace and add to the biodiversity that was lost, Fitton says.
This new compliance market for biodiversity offsets could reach about £300 million (US$382 million) in size, he says.
Finance Earth and Federated Hermes are currently raising funds for a U.K. Nature Impact Fund that is likely to invest in those offsets in addition to other nature-based solutions, including voluntary offset markets for biodiverse woodlands and for peatlands restoration.
The fund was seeded with £30 million from the U.K. Department for Environment, Food and Rural Affairs—money that is designed to absorb first losses, should that be needed. The government investment gives mainstream investors more security to step into a relatively new sector, Fitton says.
“We need the public sector and philanthropy to take a bit more downside risk,” he says. That way Finance Earth can tell mainstream investors “look, I know you haven’t invested in nature directly before, but we are pretty confident we’ve got commercial-level returns we can generate, and we’ve got this public sector [entity] who’s endorsing the fund and taking more risk,” Fitton says.
Since December 2022, when 188 government representatives attending the UN Biodiversity Conference in Montreal agreed to address biodiversity loss, restore ecosystems, and protect indigenous rights, several asset managers began “creating new strategies or refining strategies to be more nature or biodiversity focused,” Ma says.
He cautioned, however, that some asset managers are more authentic about it than others.
“Some have taken it seriously to hire scientists to do this properly and make sure that it’s not just a greenwashing or impact-washing exercise,” Ma says. “We’re starting to see some of those strategies come to market and, in terms of actual decisions and deployments, that’s why we think this year we’ll see a boost.”
Fitton has noticed, too, that institutional investors are hiring experts in natural capital, recognizing that it’s a separate asset class that requires expertise.
“When that starts happening across the board then meaningful amounts of money will move,” he says. “There’s lots of projects there, there’s lots of things to invest in and there’ll be more and more projects to invest in as more of these markets become more and more mature.”
 Copyright 2020, Dow Jones & Company, Inc. All Rights Reserved Worldwide. LEARN MORE


BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.
The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
AI-powered travel agents are challenging online booking platforms, but Airbnb’s exclusive listings and direct customer relationships could give it an edge. Its next challenge: turning repeat guests into loyal customers through stronger rewards and innovation.
3 min
AI agents like Muse can already find you the cheapest hotel room in Paris. But they can’t locate a cheaper version of that Catskills cabin you’ve been eyeing, because it might only be available on Airbnb ABNB -1.43%decrease.
Investors should pay attention to that distinction. When Meta Platforms META 3.38%increase launched its Muse agent last month, travel stocks including Booking Holdings BKNG -1.19%decrease, Expedia and Airbnb all fell sharply.
Airbnb, though, has a real chance to emerge as a winner from the upheaval. The catch: Its stock already reflects above-industry growth. To justify its valuation, Airbnb will need to turn repeat customers into loyal ones.
Online travel companies make much of their money by simplifying search and collecting fees on bookings. AI agents threaten that model.
But not all travel marketplaces are equally exposed. Booking and Expedia largely sell hotel rooms that travelers can also book directly or through competing sites. If an agent can find the same room elsewhere, it has little reason to favor either Booking or Expedia.
Booking and Expedia also sell sponsored listings that steer travelers toward particular properties. Wells Fargo estimates those will account for about 8% of Expedia’s revenue and a much higher percentage of profit next year.
Airbnb has more ways to adapt. More than half its listings are available only on its platform, and more than 90% of its traffic comes directly to its app or website.
The customer relationship doesn’t end after booking, either. Bernstein analyst Richard Clarke notes that 90% of Airbnb guests go on to message their hosts about arrival times, keys or local taxes, giving Airbnb a connection to both sides of the transaction.
How the companies have responded to the possible agentic future is telling.
Expedia quickly signed on as a Muse partner. Airbnb hasn’t, and Chief Executive Brian Chesky says AI chatbots have so far been a boon, sending customers to Airbnb’s website.
Chatbots might work for buying paper towels, he quipped at a Skift conference last month, but people enjoy planning trips. He argued that browsing dozens of homes isn’t something a text-based chatbot is well suited for.
Still, the AI jitters arrived just as Airbnb was persuading investors it deserved its pricey multiple. For years after its 2020 initial public offering, the stock—which trades around 25 to 30 times forward earnings—went nowhere. Investors saw a mature operator trading at a growth premium.
This year, Airbnb growth seems to be accelerating. The stock jumped in August after the company raised its full-year revenue-growth guidance with its second-quarter results. Wells Fargo analyst Ken Gawrelski credits a run of product improvements under a revamped leadership team.
Among the changes: letting guests reserve now and pay later, adding hotels, and a redesigned home page and app. Investors were also betting on what comes next, including thousands more hotels, car rentals and, eventually, advertising.
The irony is that some of those growth drivers push Airbnb closer to the kind of business Booking and Expedia run—the kind of business AI agents could threaten. Even if AI agents capture a large share of travel planning and booking, Airbnb would capture the demand. But it and others would slowly lose control over how customers find and choose properties.
That would undermine the advertising opportunity investors are counting on. The bigger point for Airbnb and other marketplaces is that losing control of customer acquisition could mean surrendering some of their pricing power and margins.
To bulletproof itself, Airbnb might look to another e-commerce giant that has so far kept AI agents at arm’s length: Amazon.
Like Amazon, Airbnb has a loyal customer base and hard-to-match supply. But it has nothing like Prime membership to make customers think twice before taking their business elsewhere.
That is where loyalty comes in. Business travelers stick with Hilton or Marriott because enough nights earn them perks. Leisure travelers rarely accumulate stays with one chain. Airbnb has millions of listings and plenty of repeat customers, but no broad rewards program. It has begun experimenting with credits on hotel stays, but it should make loyalty a priority, not just a promotion.
Airbnb also plans to launch its own AI agent next year. But travelers using an agent might still want it to search Airbnb, Vrbo, Booking and hotel websites alike, rather than limit itself to one company’s inventory.
Eventually, Airbnb might have to strike deals with agent makers, using its unique homes as leverage to negotiate favorable terms, says Gawrelski. Such deals, along with rewards for loyal guests, could over the long term eat into the company’s roughly 13% take rate, he adds. But if they bring in enough additional bookings, the trade-off could be worthwhile.
History offers a reason not to panic. The shift from desktop to mobile unsettled investors in Alphabet and Amazon, but both emerged as major beneficiaries. Companies with valuable assets can come out of a platform shift stronger, if they adapt quickly enough.
Airbnb has homes the bots can’t easily replace. Now it needs to give guests a reason to insist on booking them there.
