
2021: The Unexpected Is Expected
MSQ Capital’s Managing Director Paul Miron says it’s time to shirk any complacency and look beyond the unabated growth.
By Paul Miron
Wed, Feb 24, 2021 4:30am 6 min
6 min


MSQ Capital’s Managing Director Paul Miron says it’s time to shirk any complacency and look beyond the unabated growth.
6 min
—
For savvy investors, including property and mortgage investors, the new year traditionally starts by reading bold economic and property predictions penned by favourite fund managers and economists attempting to predict what lies ahead.
If 2020 taught us anything, it was to expect the unexpected. And while 2021 will be a continuation of the emotional roller coaster ride experienced the past 12 months, the difference is that the unexpected is now the expected.
It took me over a decade to truly appreciate and understand a quote from an old economics professor: “Economic forecasting is like trying to predict tomorrow’s weather whilst taking into account how people will collectively feel on that day”. There’s a big difference between economic forecasting and commentating, and those who are bold enough to forecast are (sadly) rarely right.
Despite uncertainty, Australia continues to earn its title as the The Lucky Country via leading virus control and a stable economy. The IMF’s latest predictions claim our economy will be powering towards 5.2% GDP growth this year and 4.1% GDP in 2022, much to the envy for the rest of the world. Despite what can be seen as one of the most significant trade wars in Australia’s history, the ongoing stoush with China, our aggregate exports are steadily growing, predominately off the back of mining.
Remarkably, there’s been no government support for continuing immigration during the pandemic — which traditionally is a significant economic driver— and my mind truly boggles as to how this is playing out.
When it comes to the Australian property market, we need to remember it was less than eight months ago that the general consensus of most respected economists and property commentators was that property would fall in excess of 10% – 20%. Some banks even predicted declines of up to 30%. Today, the RBA believes house values could increase by up to 30% over the next three years (so much for expert economic commentators).
Despite the overall positive property euphoria, we must not become complacent with the apparent advent of continued unabated growth and unwittingly underestimate the ‘iceberg effect’ – because we still don’t know what else could be lurking below the surface.
No one can be quite sure of the quantum of zombie companies still feeding off the Government’s life support which is due to abruptly end this March. Moreover, once the bank moratorium is over, banks will surely begin recovering on delinquent loans. And we are yet to see the full ramifications of both of these unfolding events.
We believe that the possible negative aspects of the aforementioned events have been significantly mitigated due to the Government’s generous support measures and swift actions enabling us to enjoy our current and favourable set of economic circumstances.
Prime Minister Scott Morrison last week announced that 90% of the jobs lost during the darkest hour of the pandemic have been clawed back — thus allowing our free markets to take over the economic recovery without further government support. Interestingly, we are now experiencing a tsunami of capital flow through our financial markets.
Despite current rhetoric, as a commercial mortgage fund manager, we need to look deeper than the high-level property headlines. For commercial mortgage funds managers to engage longterm success, they need to be consistent and disciplined in their risk and credit assessments.This ensures maximisation of capital preservation can be maintained and our investors (including SMSF trustees) can rely upon the consistency of regular stable monthly income distributions.
And so to some quick fire market insights …
Despite a large spike in local migration from Sydney and Melbourne to regional areas, our view has not changed on the risk in lending in regional areas. Just as quickly as the prices and demand have gone up, they can as easily revert due to an exodus of people back to the metropo areas once the COVID-19 crisis abates and the physiological desire to work face-to-face, rather than through Zoom, may once again prevail. The second reason is linked to regional areas having lower restrictions on creating new housing supply. In regional areas, undersupply of properties could turn to oversupply in a relatively short period of time as it doesn’t have the same land constrains as the metro areas of Sydney, Melbourne and Brisbane.
According to this week’s data, the inner-city vacancy rates are 8.6% — essentially double last quarter’s figures with the delivery of further supply expected in 2021. This was not unexpected due to the additional restrictions on both businesses and landlords as well as the weakening, but still prevailing, negative stigma of working in the city. To add insult to injury, many multi-national corporations have loosened work from home policies and are slowly giving up commercial space in the city. Despite this negative trend, we remain optimistic that this will reverse over time, however as it might take years, investors should be prudent on the gearing of investments secured against this asset class.
Most of the positive property headlines focus on houses prices rather than the entire residential property market, which prompts a question about price trends for units? Corelogic recently published that the difference between house and unit prices has never been wider with this gap only continuing to expand.
In saying this, there are a number of contributing factors to consider:
Despite all the odds, including decreasing demand, unit prices remain resilient. We believe that unit prices, which normally lag behind house prices, will catch up in the long term and eventually the gap will shorten.
Msquared Capital has identified a number of emerging gaps in the commercial lending market which has enabled us to introduce investors to unique opportunities.
Business owners who’ve been temporally impacted by COVID-19 are now requiring commercial funding and banks have been slow to adapt and are still trying to wrap their heads around how to provide businesses with the right access to cashflow during COVID-19. These business operators typically have quality real estate to offer as security and this creates a specific opportunity for our investors right now.
With the RBA recently making a strong public commitment that interest rates will remain unchanged until 2024, both business and consumer confidence around obtaining appropriate finance is high. On the flip side, those investors who have historically relied upon bank term deposits to provide them with a good regular income stream are losing out with TD rates hovering around a meagre 0.75%pa.. Accordingly, it’s a great time for those investors to look at alternate investments, including a registered first mortgage loan to a small business borrower (with target rates of return currently between 6.50%p.a. and 8.00% p.a).
Paul Miron has more than 20 years experience in banking and commercial finance. After rising to senior positions for various Big Four banks, he started his own financial services business in 2004.

The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.
Following the successful launch of its Palais Collection, MAISON de SABRÉ has unveiled a new modular handbag system offering more than 720 styling combinations.
A five-bedroom Palo Alto home designed by Steven Ehrlich is listed for $44 million, making it the city’s most expensive listing. Built around a dramatic concrete spine, the home features four courtyards and a pool.
3 min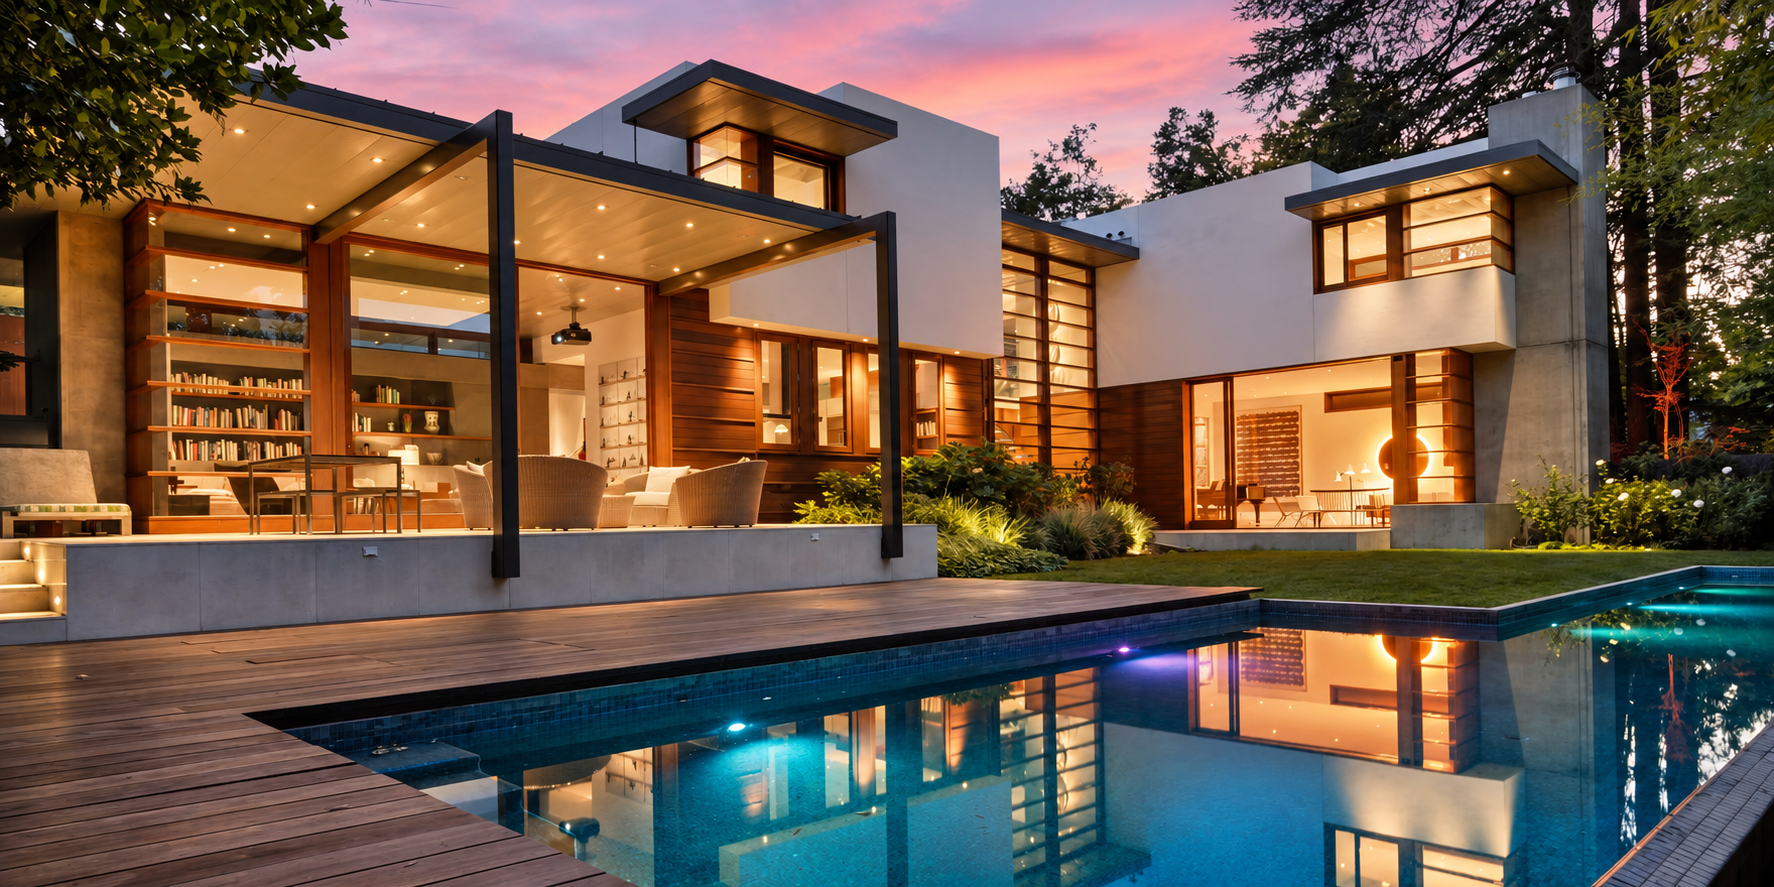
For years, tech entrepreneur Asher Waldfogel and his wife, Helyn MacLean, dreamed of building a modern house in Palo Alto, Calif.
The couple, however, worried about clashing with the Mediterranean-style architecture typically associated with their neighborhood of Old Palo Alto.
So they tapped architect Steven Ehrlich to create a design that paid homage to its surroundings with stucco, mahogany and titanium zinc cladding. They spent $20 million over several years building the house, completed in 2005.
Now looking to be closer to their adult daughter on the East Coast, they are putting the five-bedroom home on the market for $44 million—the most expensive listing in Palo Alto.
Waldfogel is an angel investor who co-founded Redback Networks, a telecommunications-equipment company. MacLean previously had a career in fundraising.
The couple purchased the roughly 0.4-acre site for $7.1 million in 2000 and demolished a circa-1930s Spanish Colonial home. The house they built pinwheels around a central staircase. It has 7,900 square feet of livable space, with four distinct courtyards and a pool.
A key feature of the home is a cast-in-place concrete wall, or spine, that is two stories high and about 80 feet long. “There’s a little bit of controlled chaos in what comes out of the form,” unlike a perfectly uniform surface, Waldfogel said. “If you want that, you do it in plastic.”
Waldfogel said he and his wife are thinking about the next phase of life now that their daughter is grown, although they have not decided where they will move. They also have a home in Sun Valley, Idaho.
“Right now we’re just trying to emotionally let go and decide what to do next,” he said.
Palo Alto, an epicenter of venture capital and tech startups in Silicon Valley, is home to some of the country’s biggest tech titans. Sales volume and prices are rising, with a median sale price of $3.5 million for the three months ending in August, up 5.8% year-over-year, according to real-estate brokerage Redfin.
Arthur Sharif of Sotheby’s International Realty—San Francisco Brokerage has the listing.


