Stocks Are at Record Highs, but Things Will Only Get Harder From Here - Kanebridge News
Share Button

Stocks Are at Record Highs, but Things Will Only Get Harder From Here

Expectations for interest-rate cuts are waning. Some investors say stock gains might be hard-won as a result.

By ERIC WALLERSTEIN
Mon, Jan 22, 2024 9:37amGrey Clock 3 min

Wall Street entered 2024 betting the year would go perfectly, but an up-and-down start for stocks and bonds suggests the going won’t be easy.

Stocks have climbed to records, driven by cooling inflation that has spurred investors to anticipate as many as six interest-rate cuts. Falling rates often boost share prices by reducing the relative appeal of bonds and making it cheaper for companies and consumers to borrow, lifting corporate profits.

But despite Friday’s record close in the S&P 500, the rally in major indexes has stalled in recent weeks—the benchmark index is up less than 2% from where it was a month ago—while the labour market and economy show few signs of slowing. Bond yields have ticked up in the new year after falling sharply at the end of 2023.

This dynamic is prompting some analysts and portfolio managers to warn that further stock gains might be halting because the rate cuts that are widely expected to power the market higher might not arrive as quickly as bullish investors had wagered.

“Clearly, the consensus is that inflation is under control and we’re heading for a soft landing,” said Doug Fincher, a portfolio manager at New York City-based hedge fund Ionic Capital Management. “It’s certainly possible—but a lot of that is priced in.”

The S&P 500 is up 1.5% this year, but analysts see more signs of caution under the hood.

Investors have retreated this year from shares of banks, smaller companies and real-estate firms that posted big gains during the fourth-quarter rally, which was kicked off by investor belief that the Federal Reserve had pivoted in November to a rate-cutting stance. Bond yields, which rise when prices fall, have climbed as traders have pared back bets that Fed officials will start cutting rates in March.

There is a greater than 50% chance the central bank keeps rates where they are at its March meeting, according to the CME FedWatch tool. At the start of the year, traders expected rates to end December around 3.85%. Now they expect closer to 4.1%, per futures contracts tied to the fed-funds rate.

Behind those moves: data showing persistent economic strength that could lift inflation. Treasury yields, a benchmark for borrowing costs, surged last week after Fed governor Christopher Waller cautioned against rushing to cut rates. Yields’ climb continued after data on retail sales, housing starts and unemployment filings all beat economists’ projections. The 10-year U.S. Treasury yield finished the week at 4.145% after starting the year at 3.860%.

Traders are now betting inflation will average above 2.4% over the next five years, the highest level since November, based on swap contracts tied to the consumer-price index.

The Russell 2000 index of small-cap stocks—which gained 22% in the last two months of the year—is down 4.1% in January. Speculative stocks have taken a beating; both Rivian and Coinbase have lost more than 25% after rising during the Fed-pivot rally. A KBW index of regional banks, which added 31% in November and December, has slid more than 3%. Shares of real-estate and utility companies are down even more, also having surged in those months.

The Bloomberg Barclays aggregate bond index, which soared in the final months of last year, is down 1.4% to start 2024.

“People tried to front-run the rate cuts by buying long-duration assets, like tech stocks and bonds,” said Nancy Davis, founder of asset management firm Quadratic Capital Management. “What if the Fed doesn’t cut that much or that quickly? Those people get hung out to dry.”

The Atlanta Fed’s GDPNow model shows the economy likely grew at a 2.4% inflation-adjusted pace in the fourth quarter. That is nowhere near the conditions that have historically necessitated rates coming down 1.5 percentage points—which traders were betting on heading into 2024.

The extra compensation investors receive for buying high-quality corporate bonds over Treasurys is slimmer than before the Fed began raising rates, now around a percentage point. Credit spreads on junk bonds are similarly tight, signaling little concern over company defaults. Leveraged loans—used to fund private-equity buyouts or finance poorly rated companies—are in such high demand that companies are slashing their borrowing costs.

Some investors believe a strong economy could still boost stocks.

Sophia Drossos, an economist and strategist at Stamford, Conn.-based hedge fund Point72, expects robust consumer spending—and a proactive Fed—to help avert a recession and prop up corporate profits. The strong underlying U.S. economy “means risky assets can benefit,” Drossos said.

Not everyone is optimistic. Some fear new sources of inflationary pressure, such as trade disruptions from the Houthi attacks in the Red Sea and a drought in the Panama Canal.

And technical factors also could undermine the market gains. Interest-rate bets often represent investors protecting their portfolios against the risk of a recession or crisis that requires sudden rate cuts. Without a major slowdown, investors might remove those hedges, raising market rates. That could tighten financial conditions and disrupt stocks without any fundamental changes to the economic outlook.

But considering the strength of the economy, many doubt rate cuts will be as aggressive as investors hoped just a few weeks ago, threatening one of the rally’s biggest pillars of support.

“You’d think the wheels would have to come off to see that number of cuts,” said Fincher.


MOST POPULAR

BNW Developments has established a Sydney presence, joining Arada and Sobha Realty among the growing number of UAE developers pursuing Australian buyers and development opportunities.

The Australian leather house has opened an immersive four-day pop-up in Manhattan, unveiling its Bloom Collection and redefining what a product launch can look like.

Related Stories
Lifestyle
AI Agents Are a Threat to Travel Businesses. Airbnb Could Still Be a Winner.
By David Wainer 13/10/2026
Lifestyle
Amazon in Talks to Buy AI Startup Decart for Around $7 Billion
By Kate Clark and Lauren Thomas 12/10/2026
Lifestyle
Dolly Parton’s Onetime Hollywood Hills Home Lists for the First Time in a Generation Asking $7.95M
By 06/10/2026

AI-powered travel agents are challenging online booking platforms, but Airbnb’s exclusive listings and direct customer relationships could give it an edge. Its next challenge: turning repeat guests into loyal customers through stronger rewards and innovation.

By David Wainer
Tue, Oct 13, 2026 3 min

AI agents like Muse can already find you the cheapest hotel room in Paris. But they can’t locate a cheaper version of that Catskills cabin you’ve been eyeing, because it might only be available on Airbnb ABNB -1.43%decrease.

Investors should pay attention to that distinction. When Meta Platforms META 3.38%increase launched its Muse agent last month, travel stocks including Booking Holdings BKNG -1.19%decrease, Expedia and Airbnb all fell sharply.

Airbnb, though, has a real chance to emerge as a winner from the upheaval. The catch: Its stock already reflects above-industry growth. To justify its valuation, Airbnb will need to turn repeat customers into loyal ones.

Online travel companies make much of their money by simplifying search and collecting fees on bookings. AI agents threaten that model.

But not all travel marketplaces are equally exposed. Booking and Expedia largely sell hotel rooms that travelers can also book directly or through competing sites. If an agent can find the same room elsewhere, it has little reason to favor either Booking or Expedia.

Booking and Expedia also sell sponsored listings that steer travelers toward particular properties. Wells Fargo estimates those will account for about 8% of Expedia’s revenue and a much higher percentage of profit next year.

Airbnb has more ways to adapt. More than half its listings are available only on its platform, and more than 90% of its traffic comes directly to its app or website.

The customer relationship doesn’t end after booking, either. Bernstein analyst Richard Clarke notes that 90% of Airbnb guests go on to message their hosts about arrival times, keys or local taxes, giving Airbnb a connection to both sides of the transaction.

How the companies have responded to the possible agentic future is telling.

Expedia quickly signed on as a Muse partner. Airbnb hasn’t, and Chief Executive Brian Chesky says AI chatbots have so far been a boon, sending customers to Airbnb’s website.

Chatbots might work for buying paper towels, he quipped at a Skift conference last month, but people enjoy planning trips. He argued that browsing dozens of homes isn’t something a text-based chatbot is well suited for.

Still, the AI jitters arrived just as Airbnb was persuading investors it deserved its pricey multiple. For years after its 2020 initial public offering, the stock—which trades around 25 to 30 times forward earnings—went nowhere. Investors saw a mature operator trading at a growth premium.

This year, Airbnb growth seems to be accelerating. The stock jumped in August after the company raised its full-year revenue-growth guidance with its second-quarter results. Wells Fargo analyst Ken Gawrelski credits a run of product improvements under a revamped leadership team.

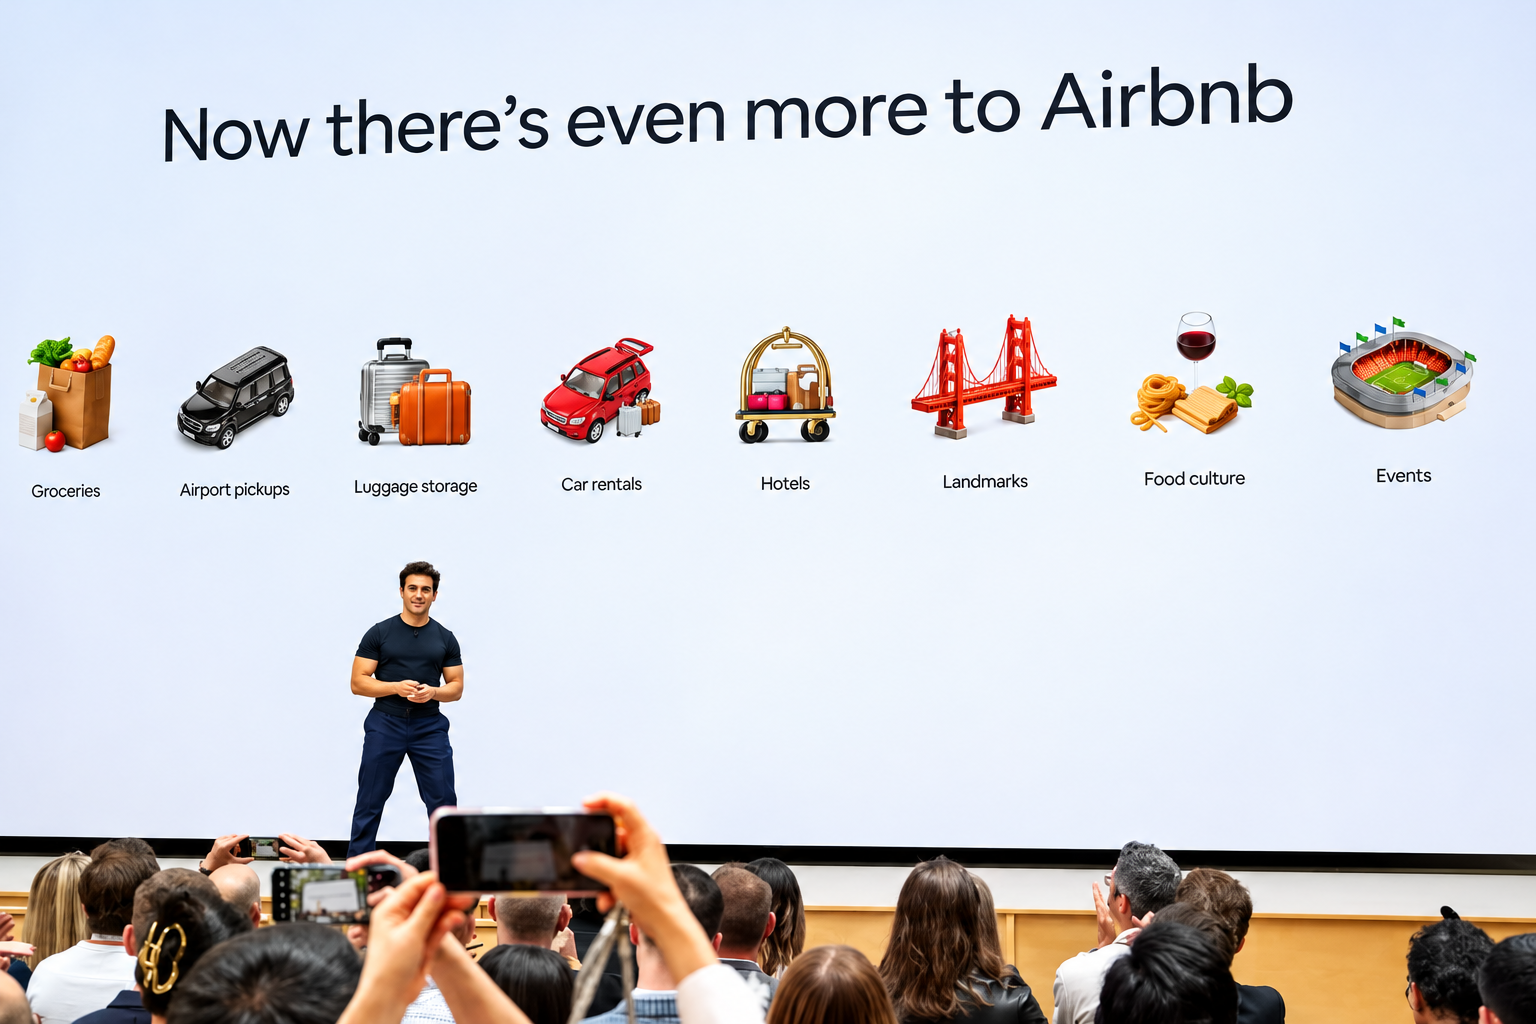
Among the changes: letting guests reserve now and pay later, adding hotels, and a redesigned home page and app. Investors were also betting on what comes next, including thousands more hotels, car rentals and, eventually, advertising.

The irony is that some of those growth drivers push Airbnb closer to the kind of business Booking and Expedia run—the kind of business AI agents could threaten. Even if AI agents capture a large share of travel planning and booking, Airbnb would capture the demand. But it and others would slowly lose control over how customers find and choose properties.

That would undermine the advertising opportunity investors are counting on. The bigger point for Airbnb and other marketplaces is that losing control of customer acquisition could mean surrendering some of their pricing power and margins.

To bulletproof itself, Airbnb might look to another e-commerce giant that has so far kept AI agents at arm’s length: Amazon.

Like Amazon, Airbnb has a loyal customer base and hard-to-match supply. But it has nothing like Prime membership to make customers think twice before taking their business elsewhere.

That is where loyalty comes in. Business travelers stick with Hilton or Marriott because enough nights earn them perks. Leisure travelers rarely accumulate stays with one chain. Airbnb has millions of listings and plenty of repeat customers, but no broad rewards program. It has begun experimenting with credits on hotel stays, but it should make loyalty a priority, not just a promotion.

Airbnb also plans to launch its own AI agent next year. But travelers using an agent might still want it to search Airbnb, Vrbo, Booking and hotel websites alike, rather than limit itself to one company’s inventory.

Eventually, Airbnb might have to strike deals with agent makers, using its unique homes as leverage to negotiate favorable terms, says Gawrelski. Such deals, along with rewards for loyal guests, could over the long term eat into the company’s roughly 13% take rate, he adds. But if they bring in enough additional bookings, the trade-off could be worthwhile.

History offers a reason not to panic. The shift from desktop to mobile unsettled investors in Alphabet and Amazon, but both emerged as major beneficiaries. Companies with valuable assets can come out of a platform shift stronger, if they adapt quickly enough.

Airbnb has homes the bots can’t easily replace. Now it needs to give guests a reason to insist on booking them there.