Stocks Are Crashing—That’s a Great Reason to Sit Tight

The red numbers in your 401(k) today might appear to vindicate warnings about an artificial-intelligence bubble and infirm economy. But don’t tilt your portfolio toward full pessimism just yet.

The S&P 500 was down 3% Monday, with the Nasdaq falling even further. Investors have been selling the year’s best performers, concerned that disappointing second-quarter results from big technology companies such as Alphabet , Tesla and Intel are a sign that the AI frenzy is a fad. Also, consumer discretionary stocks have become the worst-performing sector in the S&P 500, as lacklustre labour-market reports have raised worries that the Federal Reserve made a mistake by waiting until September to cut interest rates.
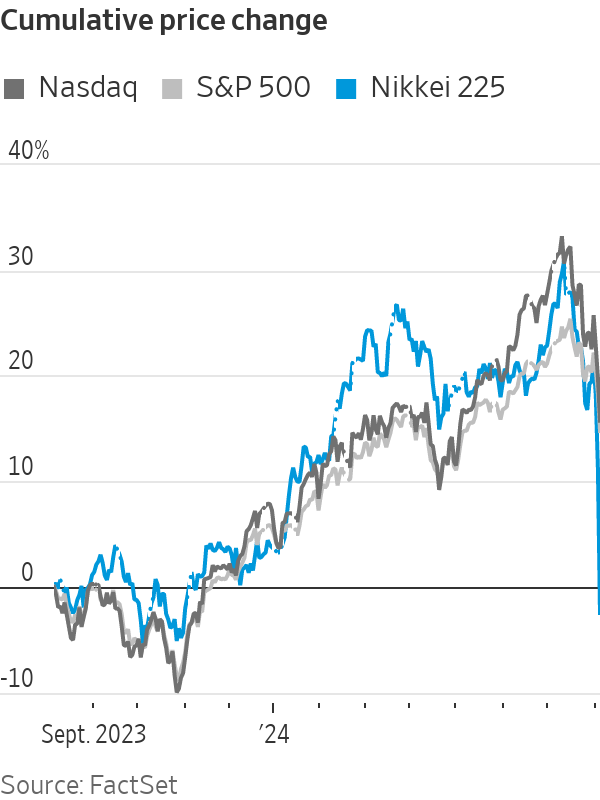
Overseas, the Stoxx Europe 600 closed almost 5% below where it was a week ago, whereas the Swiss franc, a common haven asset, is up roughly 4%. The most eye-popping moves happened in Asia, though, where the Nikkei 225 plunged 12.4% Monday in the worst trading session since Oct. 20, 1987—the day that followed Wall Street’s infamous Black Monday.

Yet it is precisely the breakneck speed with which Japanese equities tumbled that should give most investors a reason to remain calm.

As a guideline, sudden market selloffs are less dangerous than those that unfold progressively over time. This is because investors who rationally price in bad economic data often do so slowly, as it trickles in. Flash crashes, conversely, are often a sign that some tidbit of bad news made speculative bets go awry, triggering a cascade of trades, many of them automated.

Japan is particularly prone to such reversals because interest rates there are so low that many investors use them to fund higher-yielding investments in other currencies. Whenever markets get jittery, these “carry trades” tend to unravel, pushing up the yen and hitting Japanese stocks, many of which are diversified exporters that do better when global growth accelerates. Amplifying this tendency, Japanese stocks had this year become extremely popular among global investors.
The timing of the rout also points a finger at the Bank of Japan , which last week decided to tighten monetary policy for the first time in 17 years with the explicit goal of boosting the yen. Investors who rushed to cover their bets then triggered the reversal of stretched trades elsewhere, including in the U.S.

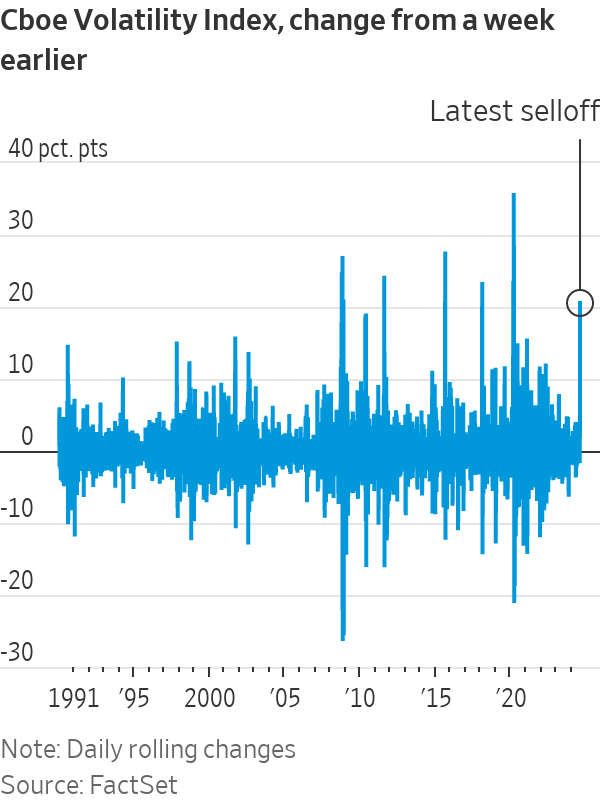
One of the most striking features of the S&P 500 for most of this year has been its extremely low volatility. Until July, the Cboe Volatility Index, or VIX, was at 2019 levels, and kept sliding lower even as investors made big changes to their monetary-policy forecasts.

While the VIX is often dubbed Wall Street’s “fear gauge,” the options contracts it is based on often themselves influence volatility. Whenever investors make bets against market swings, as they have recently in the U.S. by buying lots of structured products , the banks that sell those options are forced to take the other side. These hedges then suppress volatility in the stock market.

The flip side is that whenever a panic breaks through this feedback loop, volatility skyrockets. As the stock market opened Monday, the VIX hovered above 50, making it the highest weekly jump since the onset of the pandemic, though it later fell below 40.

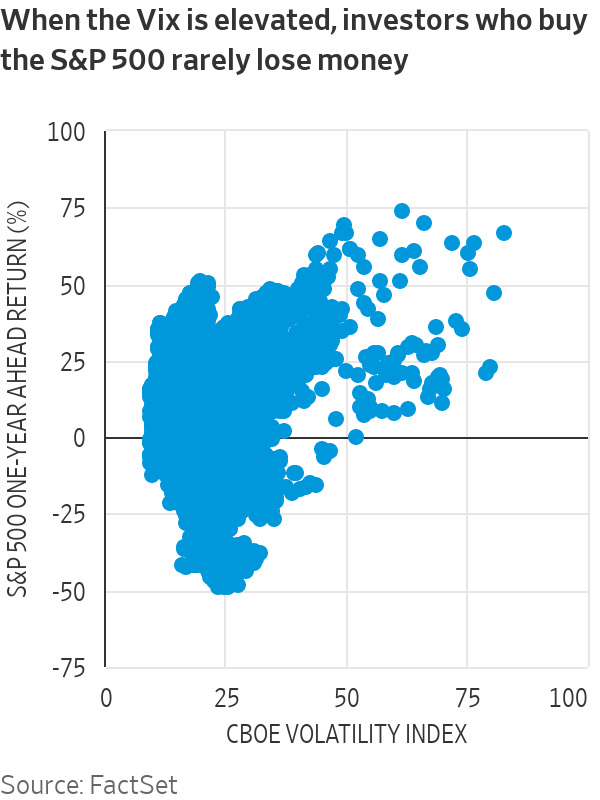
This suggests the selloff is disproportionate, especially looking at the historical record: 87% of the time, investors who bought the S&P 500 on days when the VIX closed at 30 or higher ended up making money a year later.

The second-quarter reporting season has brought mostly good news, with 78% of the S&P 500 firms that have reported so far beating analysts’ earnings estimates—compared with a 74% 10-year average. Both AI-related companies and the rest are reporting net income above what was forecast a month ago. Overall, the U.S. economy still looks robust: The unemployment rate has gone up because the labor force has expanded.

Also, looking at S&P 500 returns since 1994 shows that selling based on the previous day’s falls is a bad strategy. Electing to move into cash after large monthly declines fared better, but still less well than sitting tight.

This isn’t to say that concerns about an economic slowdown or high tech valuations aren’t warranted. Investors have reasons to diversify away from the AI trend or swap more cyclically exposed stocks for more “defensive” names. Indeed, selling out of stocks after particularly exuberant days and months has historically tended to be a winning move. But hindsight is a terrible guide to investing your savings.
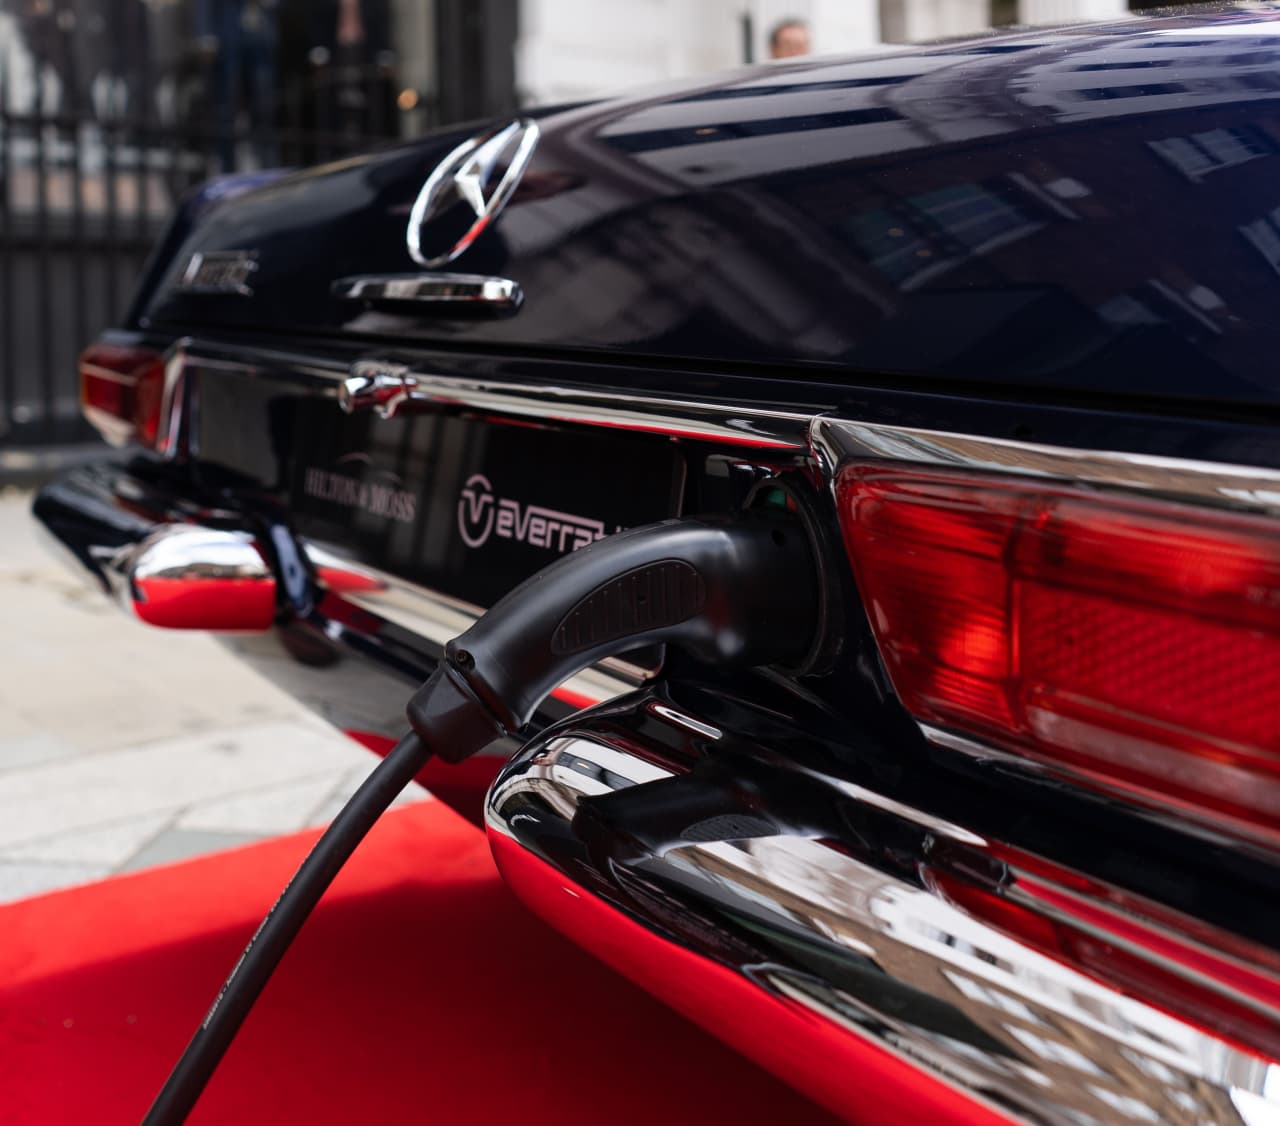
A Classic Mercedes Roadster Is Going Electric in a New Partnership

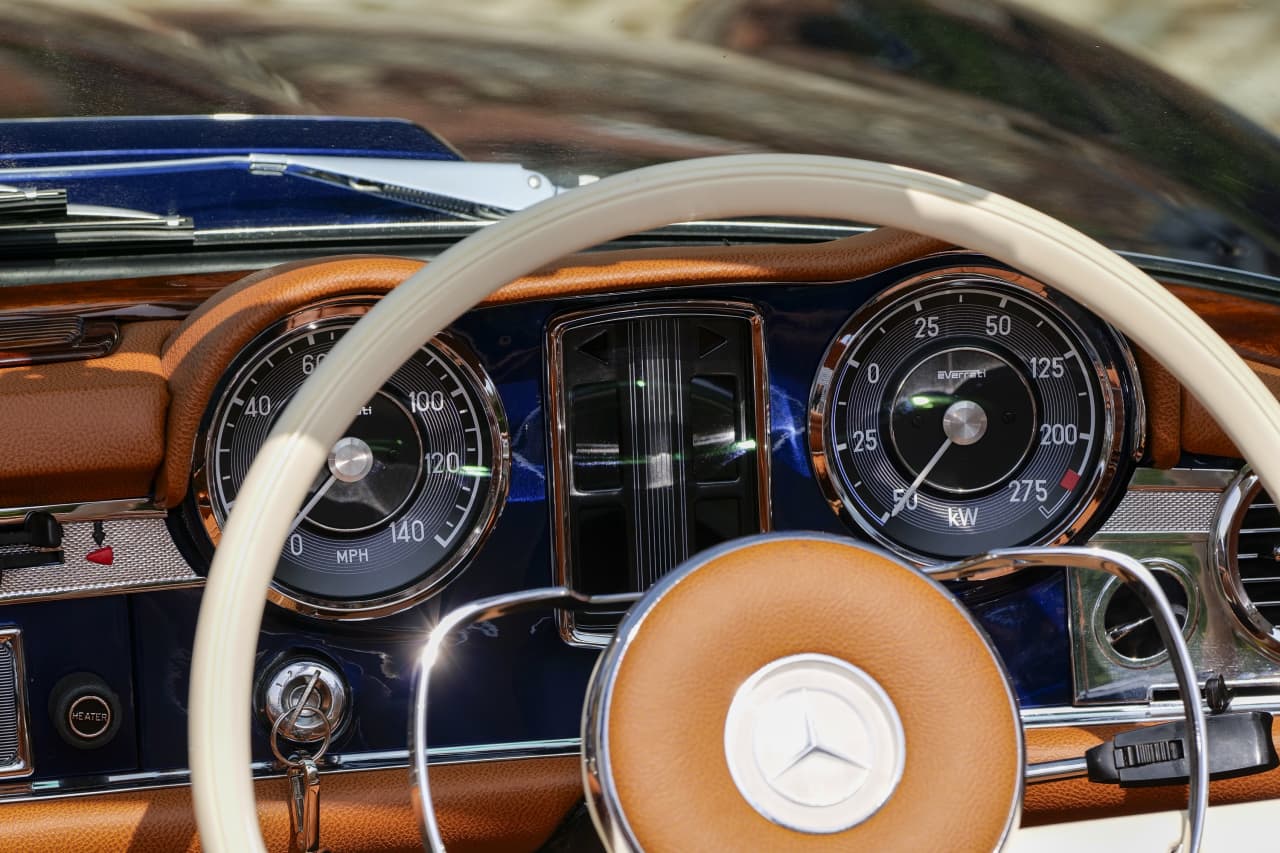
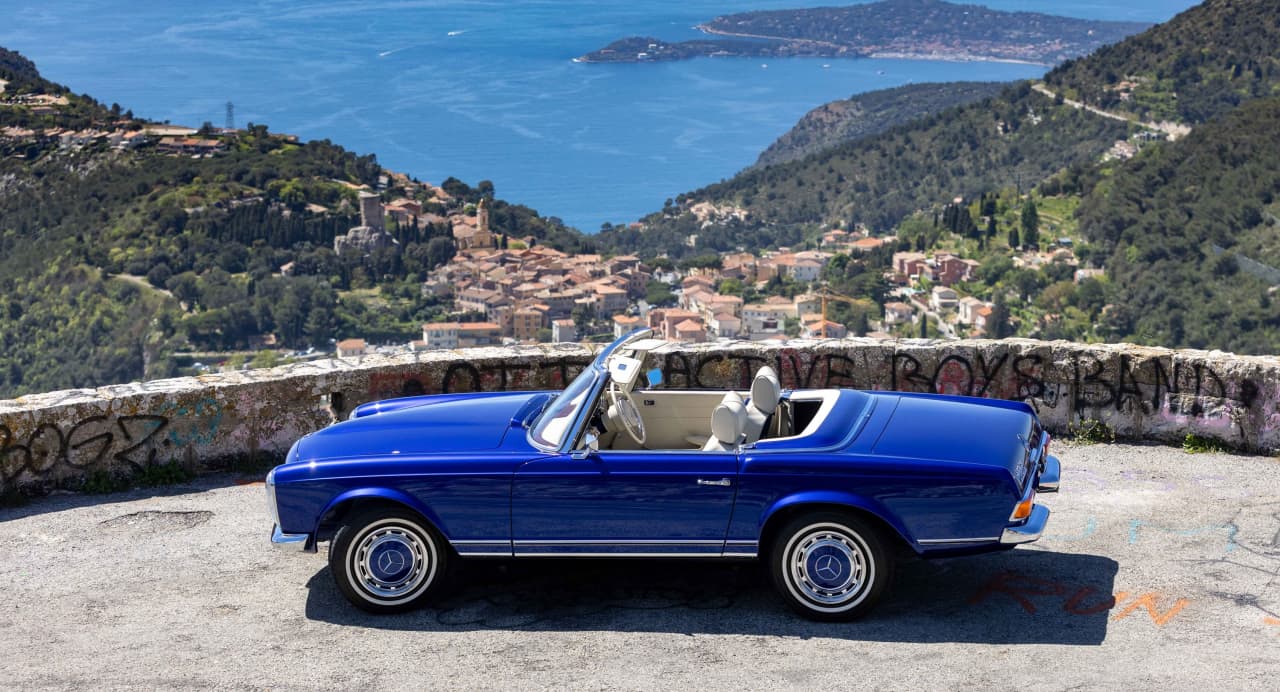
Hemmels, a Cardiff, Wales-based company that rebuilds Mercedes-Benz SLs, will soon offer an electric drivetrain for the W113 “Pagoda” models to the tune of half a million dollars through a new partnership.

The W113 SL is a glamorous two-seat roadster, which replaced the 190SL. It was introduced as the 230 SL at the 1963 Geneva Motor Show, then was gradually replaced by larger-engine models until the end of the line in 1971. The model was quite popular in the U.S., where nearly 20,000 were sold.

“We were on a route to develop a battery powertrain in-house at Hemmels, and we began to realise what a complex undertaking it is, given international regulations. That’s when we discovered that Everrati had already engineered a solution,” says CEO Tom Butterfield.

The result is a collaboration between Hemmels and Everatti—which restores and electrifies classic “icons” from Porsche, Mercedes, and Land Rover from its base in Bicester, Oxfordshire. Hemmels will restore the cars and Everrati will install electric powertrains. The partnership will be officially announced on Friday, and SLs from both companies will be shown at the upcoming Pebble Beach Concours d’Elegance during Monterey Car Week (Aug. 9-18). The first jointly produced car should be available to customers in November or December. Ordering a car and taking delivery will take eight to 10 months.

The price for a full Hemmels build, with the Everrati electric drivetrain, is £400,000 (US$513,000), excluding the donor vehicle that the company can locate for customers. The cars will be offered internationally.

The SLs will have 68-kilowatt-hour batteries, distributed to help maintain the car’s ideal front-rear balance.

“The bulk of the weight will be where the original engine and gearbox were located, and there will also be batteries in place of the fuel tank and a small pack in the boot [trunk] occupying about the space of the spare tire,” says Justin Lunny, Everrati’s founder and CEO. As battery technology evolves, Lunny says, it should be able to get a more powerful pack into the same locations, and upgrades can occur.

Another British company Helix, a Lotus supplier, will provide a power-dense but compact 300-horsepower motor that together with the battery pack should yield a range of 200 miles and a zero-to-60 miles per hour time of under seven seconds. The cars will use a limited slip differential for good grip, and will be equipped for regenerative braking—recapturing energy and allowing “one pedal” driving. “The end result is a very usable driving experience,” Lunny says.

“Our process in rebuilding the cars is very in-depth, and it’s what makes us stand out,” says Butterfield, whose family bought Hemmels in 2018. “We use brand-new and upgraded parts—we don’t restore what’s there unless we absolutely have to go that route.” The restoration process can take 4,000 worker hours, and bespoke buyers have wide latitude in colours, interior materials, and a choice of options. High-end audio and Bluetooth are available.

The cars will have already been rebuilt by Hemmels by the time they take their 130-mile journey to Everrati, where the drivetrains are—very carefully—installed.

Lunny says that the SLs will not be cut up or altered during the drivetrain installation. “We don’t damage the structure of the vehicle,” he says, “and everything is technically reversible. We retain the value of the original vehicle. The owners can keep the original internal-combustion engine, ensuring that it’s still with the car.” Butterfield adds that one of his clients is turning his engine into the base “for a glass table that will be installed in his man cave.”

Lunny describes the SLs as “art pieces that happen to have wheels. We love them like our babies, and everything we do is to a replicable standard, on par with what an [original equipment] manufacturer would do.”

The W113 SLs may be more than 50 years old, but their styling—and appeal across generations—remains timeless.

“It’s not just a certain age or demographic,” Lunny says. “The new audience is the ultra-high-net-worth individuals who adore beautiful iconic cars, especially the Pagoda, but want a clean-air powertrain, with modern air conditioning, that is enjoyable to drive.”

Butterfield intends to keep production relatively low, producing perhaps 10 to 12 electric Pagodas annually. “To stretch to 25 cars per year would risk the quality of our builds,” he says. Some 60% to 70% of Hemmels’ output has gone to U.S. buyers, and that’s one reason the Monterey appearance—the company’s first—is important to the brand.

Hemmels also works its magic on the earlier 190SL, and electric conversions of those models, through the partnership, are possible in the future, Butterfield says.

Mallorcan Megamansion That’s Set to Break Ground This Fall Lists for €42.5 Million

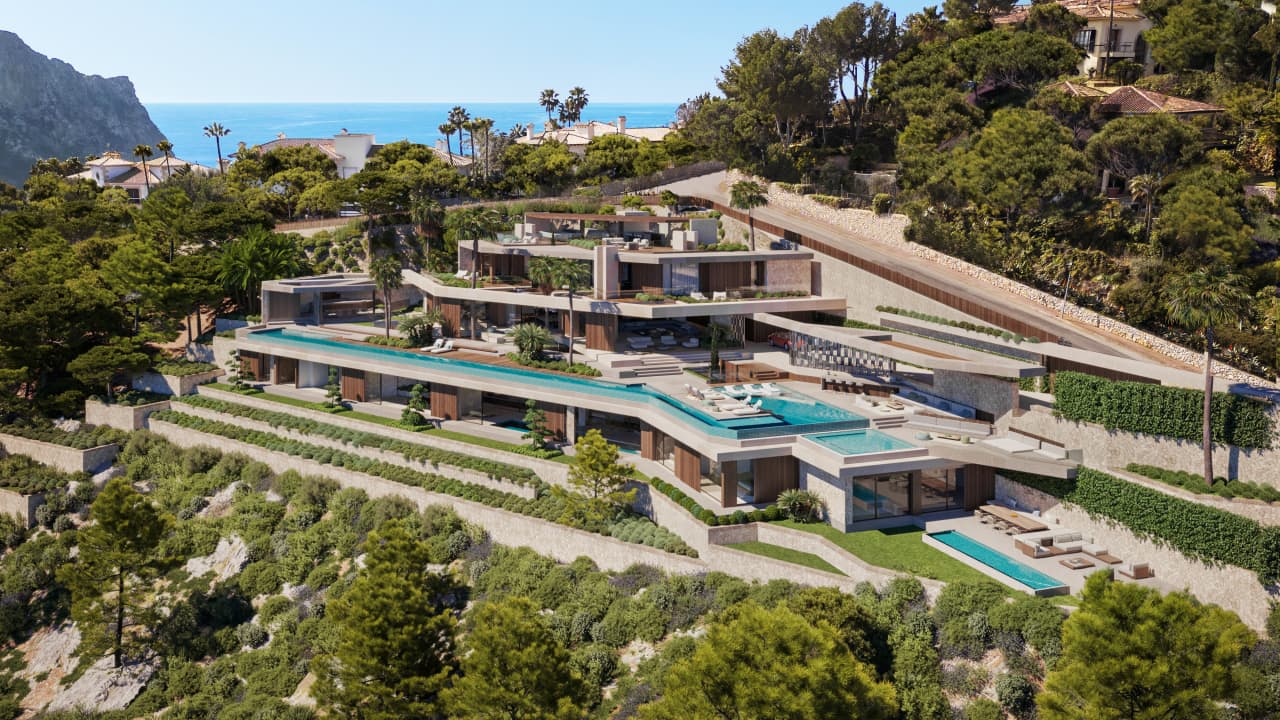
What will be a sprawling villa in Mallorca has hit the market for €42.5 million (US$45.8 million) making it one of the most expensive offerings currently available on the bucolic Spanish island.

Work on the almost 19,000-square-foot residence is set to begin in September, and construction is expected to take somewhere around two-and-a-half to three years, according to Alby Euesden, managing partner of the Agency’s Mallorca office, which brought the home to the market at the end of June.

Surrounded by Port d’Andratx and the scenic mountain ranges of the Tramuntana, “Villa Pura has been designed to frame its surrounding environment at every opportunity, using space, light and form,” Euesden said.

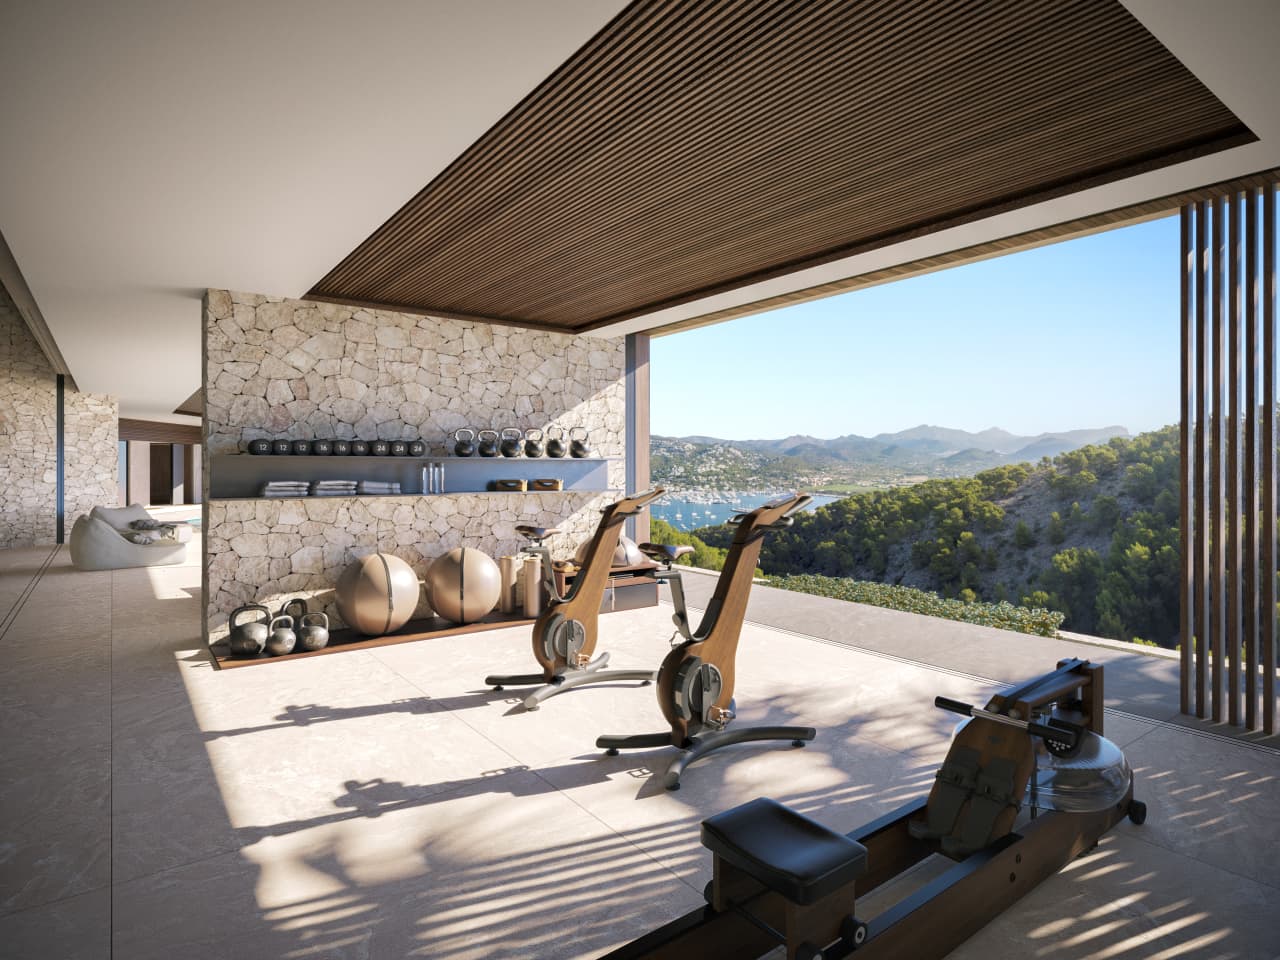
Renderings show the home’s planned gym.
Nacho Riutort at PH Mallorca

“In many ways the central feature of the space is its unique pool, which acts as its main focus point, providing a rich source of visual interest,” he said.

The sizeable infinity pool, which will run the length of the home, will be joined outside by multiple terraces, a lounge area, an outdoor bar and dining space.

Inside, the open-plan home is set to boast a sleek and organic palette, with walls of windows, exposed stone and wood details.

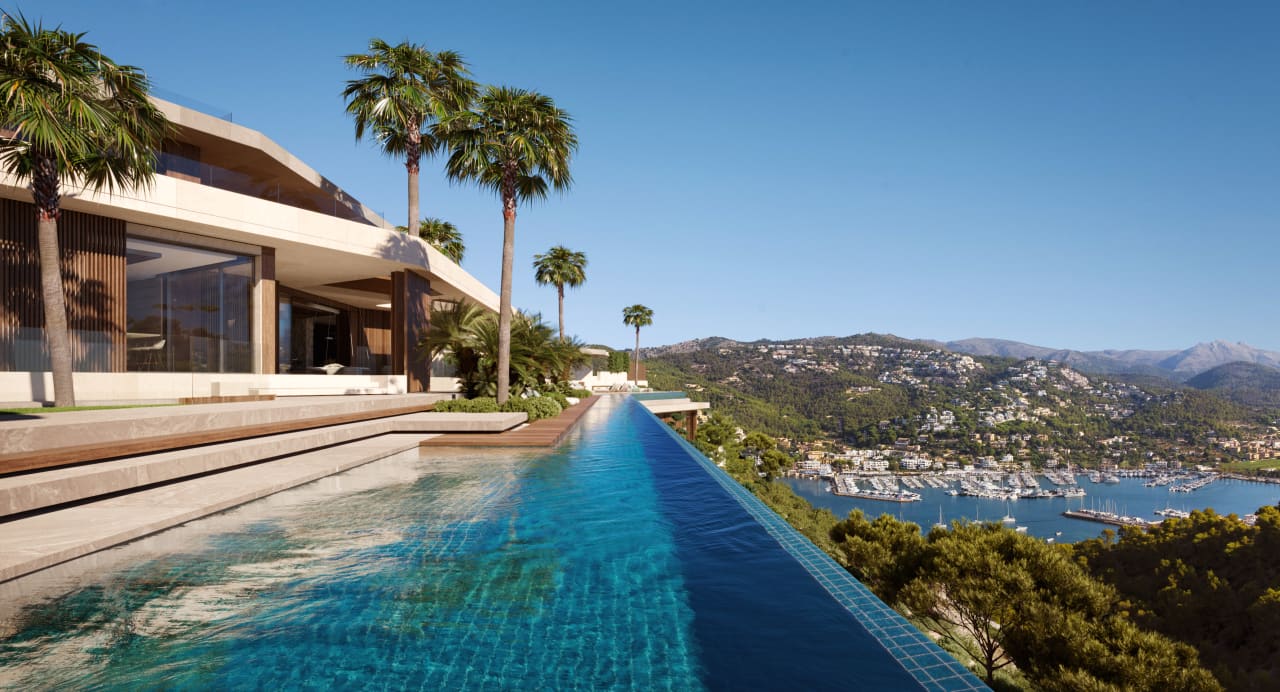
There will also be multiple living areas, a kitchen with two islands, a double-sided fireplace, a formal dining room, a gym and nine bedrooms, including a primary suite with a private terrace and hot tub. And of course, far-reaching Mediterranean views.

The property will have far-reaching views.
Nacho Riutort at PH Mallorca

The seller is one of the leading developers on the island, according to Euesden. “They acquired the land site over five years ago and have been meticulously planning the project, which initially consisted of various lots,” he said.

Euesden declined to comment on how much was paid for the underlying property.

Mallorca’s luxury market is “very buoyant right now,” he explained. “Spain has much lower mortgage rates than the rest of Europe and the U.S., with fixed rates [currently] from 2.15%.”

With Mallorca “being a destination market which attracts buyers from all over Europe, and with an ever-growing interest from U.S. investors, the market has remained stable and even seen an increase in pricing within new developments,” he added.

Eurozone Inflation Picks Up Pace in Blow to Rate-Cut Hopes

Inflation unexpectedly heated up in the eurozone this month, presenting a fresh challenge to policymakers looking for signs that eurozone price rises are easing sustainably.

Consumer prices were 2.6% higher on year in July, picking up pace from in June, according to EU figures released Wednesday. That defied economists’ expectations for a slight decrease in inflation over the month, and leaves the rate further from the European Central Bank’s elusive 2% target. Inflation heated up over the month in Germany, France and Italy, the eurozone’s three largest economies.

Core inflation, which strips out the often volatile effects of food and energy prices, meanwhile stayed stable, against expectations for a slight decrease. But services, a key focus for policymakers at the European Central Bank, did fall slightly.

That decline makes a cut to interest rates the most likely outcome in September, said Franziska Palmas, an economist at Capital Economics.

Still, the higher headline rate may give pause to the central bank as it mulls its next steps on the direction of interest rates in the 20-member eurozone.

The ECB cut interest rates in the currency union for the first time in five years last month, but has refused to be drawn on when and how quickly it will continue to lower rates from their current heights. Markets still expect a second cut to rates at the bank’s next policy meeting in September, but with less certainty than earlier in the summer.

“Until services inflation falls more significantly, the ECB is likely to continue to ease policy only slowly,” Palmas said.

Inside ‘Billionaires’ Bluff’: Why Paradise Cove Keeps Drawing the Superrich

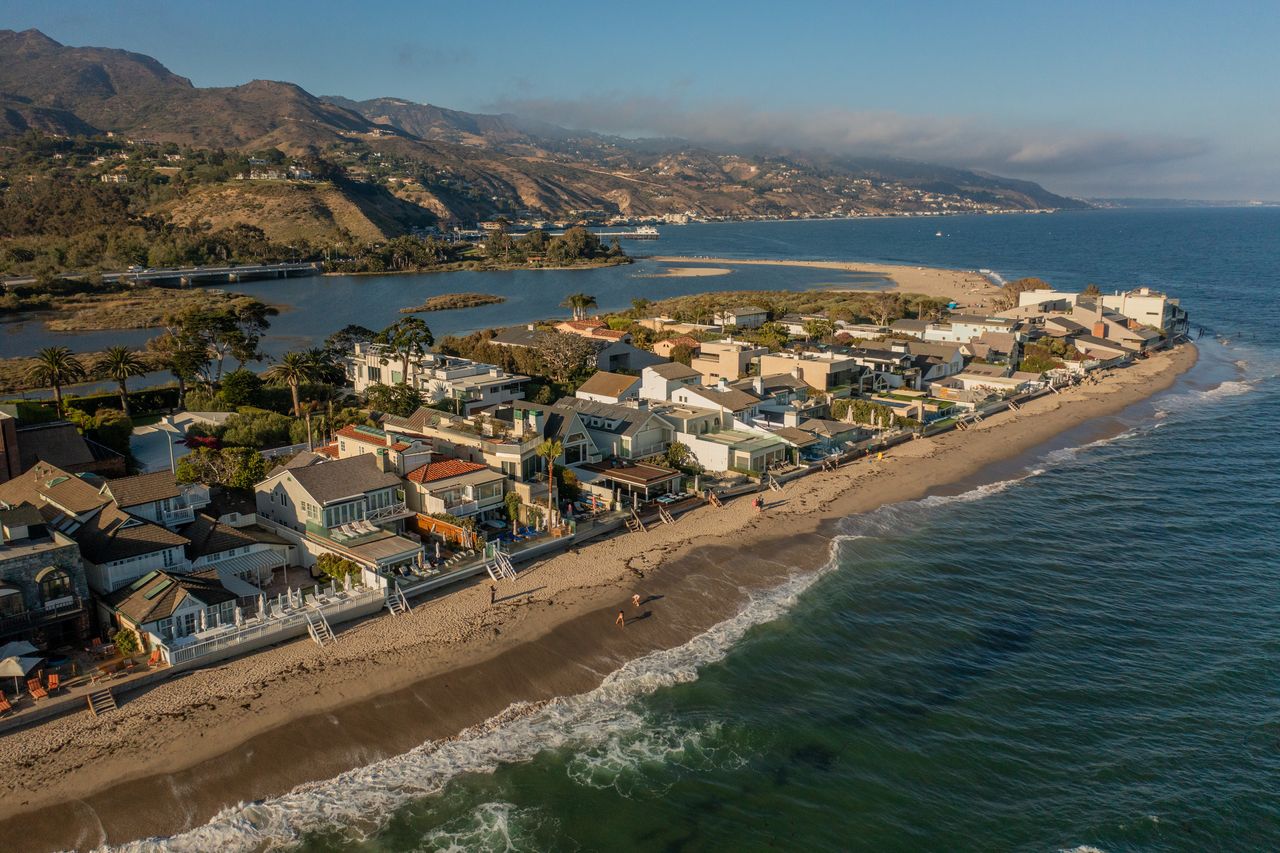
Driving north in Malibu, Calif., on the famed Pacific Coast Highway, there is a spot where the road veers away from the ocean, and the views are replaced by a hillside, thick foliage and, in some places, a man-made barrier. Many drivers have no idea they are driving past some of the world’s most expensive homes, including a recently-expanded compound owned by the widow of Apple visionary Steve Jobs.

Beyond that hillside sits a roughly 1-mile stretch of beach known as Paradise Cove, known to local realtors as “Billionaires’ Bluff.” It is so exclusive that, since 2020, three of the approximately 25 homes there have sold for $100 million or more, making up a third of the deals that closed at that price point in the Los Angeles area during the same period. Two have broken the record for the most expensive home ever sold in California at the time of each sale.

They include transactions by household names such as Beyoncé and Jay-Z, as well as technology heavyweights such as venture capitalist Marc Andreessen , WhatsApp co-founder Jan Koum and Laurene Powell Jobs . Some buyers have gone to great lengths to piece together their blufftop Paradise Cove compounds over time.

“Rich people like to congregate and they’ve congregated here,” said local agent Leonard Rabinowitz. “It makes them feel safe and more comfortable.”

In some ways, the location, roughly 35 miles from Downtown Los Angeles, seems like an unlikely destination for the country’s wealthiest people. To the north is Paradise Cove Mobile Home Park, widely regarded as the most expensive trailer park in America. Dating to the 1950s, when the then-owners allowed commercial fishermen to park campers there, the park is a throwback to the days before Malibu was brimming with the super rich. Its roughly 250 trailers and manufactured homes have since drawn celebrities such as Stevie Nicks and Matthew McConaughey, who have helped drive prices of the trailers into the millions of dollars. A casual beachfront cafe sits at the base of the bluff.

On the other side of the trailer park, on the cusp of Paradise Cove, sits an estate long owned by Barbra Streisand. To the south is the iconic Geoffrey’s restaurant, which has been serving surf and turf from its oceanfront patio since 1983.

Local realtors say the appeal of the Cove is obvious. Rather than a beach house on the sand or a blufftop mansion with more far-reaching views, homes in Paradise Cove offer the best of both worlds. Sitting behind gates off the highway, the houses are largely shielded from public view and occupy multi-acre parcels much larger that those typically available in nearby Point Dume or in the neighbouring celebrity-filled Malibu Colony. Most of the homes are also shielded from the view of their neighbours. “If you do see them, you’re seeing the corner of a roof in the distance,” said local agent Kurt Rappaport , who has sold many of the homes on the cove.

A lot of the homes also offer direct beach access via private pathways and some include beachfront cabanas or smaller homes on the sand. One formerly owned by singer Kenny Rogers has a private funicular, a type of cable railroad, that leads from the blufftop house to the ocean.

While publicly accessible, the beach at Paradise Cove is rarely busy, since there is limited parking, though it is a draw for local surfers, local agents said. Some might recognise it from the 1970s television hit “The Rockford Files,” starring James Garner, which was filmed at the cove.

A steady drumbeat of big-ticket deals in recent years has helped cement the stretch’s reputation as the most sought-after beachfront enclave in California.

Most famously, entertainment power couple Beyoncé and Jay-Z paid $190 million for a mansion designed by Japanese architect Tadao Ando. The blufftop house, measuring about 42,000 square feet, was designed by Ando for prominent art collectors Bill and Maria Bell, who spent a dozen years constructing what Maria Bell has said is a “sculpture as much as it is a building.” The deal, which closed in May 2023, was briefly the most expensive ever in the state.

Before that, a deal by venture capitalist Marc Andreessen and his wife, Laura Arrillaga-Andreessen, on the same blufftop held the record. In 2021, they paid $177 million for a 7-acre compound formerly owned by fashion mogul Serge Azria and his wife, Florence Azria. That property includes a roughly 10,000-square-foot main residence, two guesthouses, a cinema and a spa.

More recently, Powell Jobs, founder of philanthropic and investment company Emerson Collective, added a $94 million property to her private Paradise Cove compound, bringing her total aggregate spending in the cove to more than $170 million. The assemblage has involved separate transactions with four sellers spanning from 2015 to 2024.

Other major transactions include WhatsApp co-founder Jan Koum’s purchase of two neighboring compounds for a combined $187 million in 2020 and 2021, as well as movie producer Edward H. Hamm Jr’s $91 million deal to buy a home from British videogame designer Jonathan Burton and his ex-wife, Helen Musk, in 2023. In 2022, billionaire media mogul Byron Allen also paid $100 million for a Malibu estate formerly owned by self-storage billionaire Tammy Hughes Gustavson.

These wealthy newbies join a string of well-known names on the bluff. They include tennis legend John McEnroe, “The Apprentice” creator Mark Burnett, and Kari Clark, the wife of the late television host Dick Clark.

Leonardo DiCaprio is also doing construction on a home on Paradise Cove; he bought the site, which is next to the home owned by Burnett, for $23 million in 2016, according to property records and a person familiar with the deal. His property was formerly owned by director Ridley Scott.

Values in Paradise Cove have shot up so significantly thanks in large part to the lack of available inventory, Rappaport said. Since prices there are so high, the cove doesn’t typically draw speculators. Owners there are so rich they usually don’t need the money and don’t typically sell, unless they have had a significant change in circumstances, he said. One of the few available homes on the cove is an $85 million Greek-inspired estate owned by Peter O’Malley, the former owner of the Los Angeles Dodgers. O’Malley has owned the 2.5-acre property since around 2000 and is selling following the death of his wife, Annette O’Malley, last year.

When properties do come up, “there’s usually a neighbour to buy it,” Rappaport said.

Homeowners such as those on the cove don’t always start out with a plan to assemble a larger compound. Those plans shape up over time as opportunities arise, Rappaport said. The larger footprints mean increased privacy and protected views and limit the chance that homeowners will have to deal with construction on the neighbouring lot. “They think, ‘Oh, it would be nice to have the house next door,’ ” he said.

Even as the broader Los Angeles luxury market has been hobbled by interest rate increases, a drop in demand from foreign purchasers and an exodus of high-net worth individuals to lower-tax states, the Paradise Cove market has continued to post record deals.

“It reminds us that these home sales have nothing to do with the broader market they sit within,” said appraiser Jonathan Miller of Miller Samuel. “It’s a very specifically designed submarket and its success doesn’t wash over onto the whole housing market.”

Miller said it isn’t uncommon in ultrahigh-end communities for transactions to happen in clusters as they have in Paradise Cove.

“There is one big transaction and then a lot of copycats around it. I think it’s FOMO,” he said, using the popular acronym for “fear of missing out.”

In the overall L.A. market, the slowdown in deals has been compounded by a new mansion transfer tax, which applies only to the city of Los Angeles. It has “killed off excess demand,” particularly from developers and property speculators who plan to flip the properties, Miller said. Previously, that represented a significant portion of the buyer pool and the market fed on itself, he said. The new tax, enacted last year, requires sellers to pay 4% on sales of homes priced between $5 million and $10 million, and 5.5% on sales of properties at $10 million or above.

While sales are up 15% year-over-year in the overall luxury Los Angeles market, eight-figure sales are rare. None have closed in the city of Los Angeles since the introduction of the tax, according to data from Stephen Shapiro, co-founder of Westside Estate Agency.

The tax has only made sellers more resolute about their pricing, local agents said.

“Our problem [in Los Angeles] has been that the buyers think that it’s a buyer’s market and the sellers have been feeling like they’ll get their price if they hold out,” said agent Jade Mills of Coldwell Banker Realty.

In Paradise Cove, buyers are under no such illusion that the market favours them.

“They are willing to step up,” Mills said.

Affluent Home Buyers Are Driving up Prices in Southern European Cities

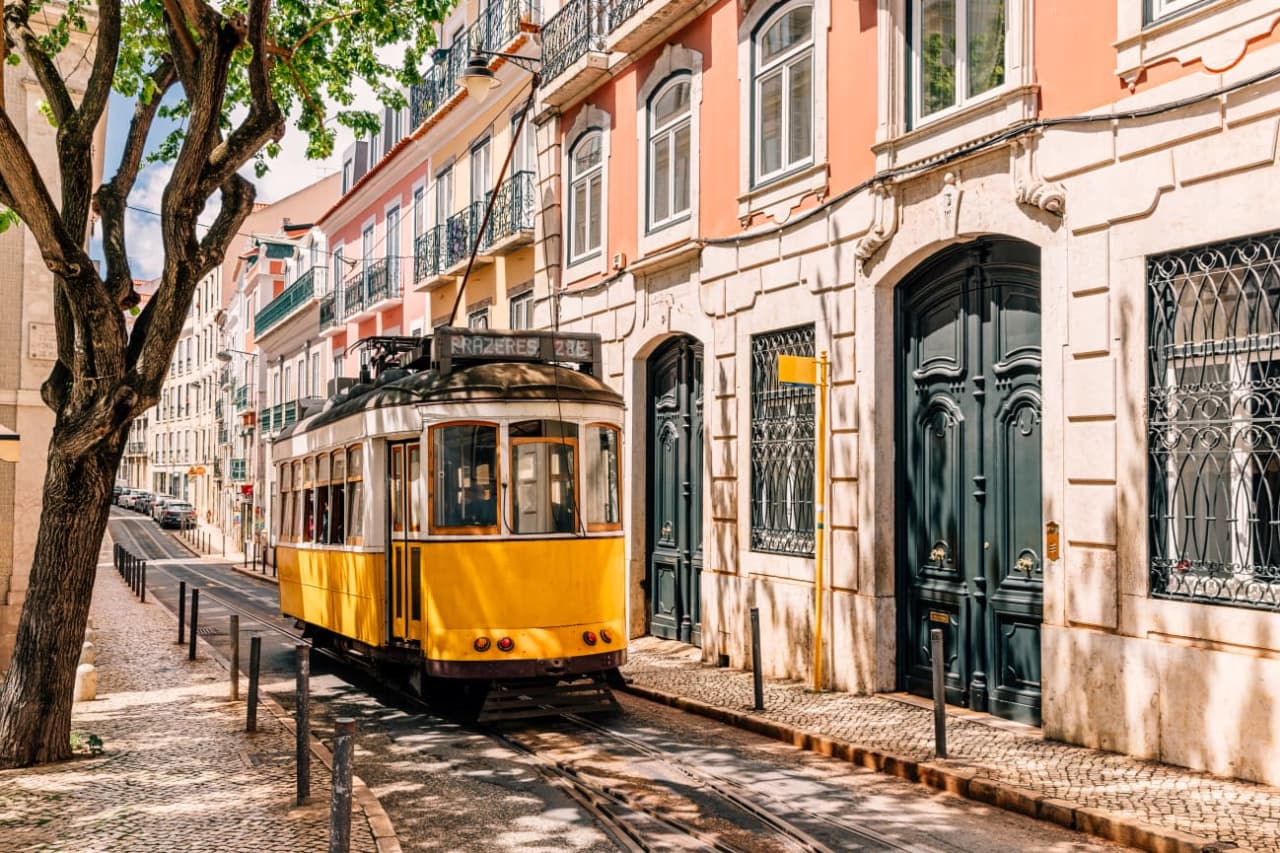
Lisbon was home to the fastest growing luxury-home prices in the first half of this year, according to a report Monday from Savills.

With gains of 4.2% in the six months through June, the Portuguese capital bested the performance of any of the other 29 prime property markets globally analysed by the property firm.

Cities in southern Europe and the Middle East saw their high-end home sectors perform best, with Lisbon followed by Amsterdam, Madrid and Athens, which all logged capital value increases above 3% over the same time. Dubai rounded out the top five with growth of 2.9%.

In southern Europe in particular, prime prices are being driven by a lack of supply, and American buyers have become a “key prospective buyer base,” Savills said, “thanks to a comparatively strong dollar and a growing interest in the lifestyle on offer.”

In the U.S., meanwhile, persistently high interest rates have impacted demand across the. housing market, and as a result, prime residential prices have fallen in three of the four U.S. cities monitored in the report, with only San Francisco seeing positive growth of 0.7% for the first half of the year.

Los Angeles ranked at the bottom of the list, with luxury prices falling roughly 4%.

Across all 30 cities analysed by Savills, prime residential property prices “remained resilient over the first half of 2024,” recording an average growth of 0.8% and outperforming the 0.6% growth predicted for the year as a whole, the report said.

More than half (60%) of the cities recorded positive capital growth, “reflecting a level of relative confidence in the asset class,” according to Savills.

Looking ahead, “we predict an average capital value growth of 0.5% for the second half of the year, which would bring total 2024 growth to 1.3%,” said Kelcie Sellers, associate director at Savills World Research in the report.

“The ongoing supply-demand mismatch for high-end residential product is projected to fuel price growth in European cities such as Amsterdam, Lisbon and Barcelona, where 2% to 3.9% is forecast in the second half of 2024.”

This article first appeared on Mansion Global

How AI Could Keep Young Workers From Getting the Skills They Need

Whenever people talk about the dangers AI holds for the workforce, they usually have one thing in mind: technology stealing jobs. But artificial intelligence poses a much more subtle threat than that—one that will have consequences for business unless we address it.

Simply put, the way we’re handling AI is keeping young workers from learning skills.

For more than 12 years, I have been studying how work changes as a result of intelligent technologies like robots and AI. Across a number of industries, I’ve seen the same thing over and over: This new, sophisticated technology makes it easier for experts to do their jobs. Seasoned surgeons can operate more quickly and efficiently, for instance, when they use robots in the operating room.

But the efficiency comes at a cost. The technology allows experts to do more, independently, so they don’t need younger, less-experienced workers to help them out anymore—so those novices are left without mentors to teach them the skills they need to do their job. Looking at operating rooms again, it takes two people to perform most complex procedures with traditional tools. The senior surgeon generally provides “exposure” by retracting tissue while the resident does what most of us think of as surgery—incisions, suturing and so on. Residents are on task the entire time. Focused. Learning.

Now the residents mostly sit around during operations and watch veteran surgeons get the job done thanks to help from a robot. Limited work. Limited learning.

As learning opportunities like these are lost throughout more industries, the results could be profound for both individual workers and the economy. We are sacrificing skill building and human bonds of mentoring on the altar of productivity. No matter our role, tenure, occupation or industry, if we can’t collaborate with someone who knows more, we’re not going to learn effectively, and we won’t be able to keep up. And our organizations will struggle where they might otherwise race ahead—because workers won’t have the deep knowledge they need to innovate and step into senior roles.

Turning history on its head

We have decades of research showing that this situation is the opposite of what we want. We build skill by collaborating across the expert/novice divide, so novices get to see the work, help out at the edges and earn the privilege of doing more next time.

Now that mechanism is being lost. My observations, combined with primary data from other field researchers, show a destructive dynamic at work, across a range of industries. In industrial-process engineering, I have seen experts use software to do modeling on their own, instead of involving a junior engineer. In warehousing, I’ve watched area managers rely on dashboard analytics to understand staffing and process flows, instead of uncovering those things collaboratively with less-experienced line leads and workers.

My collaborator Callen Anthony at New York University found that junior investment-banking analysts were being separated from senior partners as those partners started to use algorithms to help create company valuations for mergers and acquisitions. Junior analysts—instead of collaborating with the senior partners as they had before—essentially just pulled data for the algorithms to use in their valuations.

The rationale for this arrangement was twofold: reduce errors by junior people in sophisticated work and maximise senior partners’ efficiency. Explaining the work to junior staffers pulled partners away from higher-level analysis.

This setup produced short-run productivity improvement, but it moved junior analysts away from challenging, complex work, making it harder for them to learn the entire valuation process and diminishing the firm’s future capability. Junior bankers become senior bankers, after all.

Less time at the table

One of the most striking examples of the widening skill gap is surgery. I observed hundreds of procedures at some of the top teaching hospitals in the country, where robots deeply reshaped how work was done. Surgery, as I said, used to take four hands; minimally invasive surgical robots can supply three, all controllable from a single console. They make things so much easier for surgeons that the million-dollar tools have become the de facto standard for many complex procedures.

Most important, robots make it possible for surgeons to perform operations solo, no residents needed. And, since residents are slower and make more mistakes than an experienced surgeon would, those surgeons are opting to cut residents out of the action. Before, residents might operate for four hours during a 4½-hour procedure. In my nationwide data, their robotic average time hovered in the 10- to 15-minute range. And residents got less operating time in 88% to 92% of cases.

In this situation, we end up with much-less-capable surgeons. My data shows that many newly minted surgeons struggle mightily when they get their first jobs—not just because they don’t have robotic skill, but because their failed quest to learn robotics took so much effort they lost key learning opportunities in other procedures and practice areas, from ureteroscopy to kidney stones to vasectomies, that they would be expected to handle in most new surgical jobs.

The long-term loss

The consequences of poor training go beyond day-to-day competence. Consider what happens to the culture of a hospital when it loses healthy expert/novice collaborations. Less teaching and learning, to be sure, but also more-limited career advancement as experts advocate less for trainees. What about hospitals’ ability to innovate in surgical practices? Limits there, too, as discoveries made by colleagues get tamped down by increasingly focused, efficient, expert-driven surgical performance. The ability to service skyrocketing surgical demand? In the short run, you serve more patients, but in the medium term you scramble to keep up as the pool of new talent dwindles.

Of course, different organisations, industries and professions in different places will feel the pinch on different time scales. They will also compensate in different ways. But in general, organisations will not sense the problem directly: Instead, they will incrementally accumulate a larger cost base—in areas such as (re)training and reduced billable or applied time—and build a bureaucracy to manage this skills gap. At law firms, new attorneys might take longer to ramp up to normal caseloads, while senior attorneys would have to spend more non billable time to handhold them.

Now imagine the consequences of similar skills gap across all types of companies, throughout the economy. Without a firm, immediate correction, this is what we can expect. This is our trillion-dollar skills problem.

A way forward?

Solving the problem is vital, but how should we do it? My collaborator and I found evidence of one approach that can work.

Remember, the problem right now is that senior workers are learning new technologies, such as robotic surgery, that make junior workers unnecessary. In our research, though, we found cases where junior and senior workers teamed up to learn about new technologies together .

By working closely with seniors in this way, the juniors didn’t just learn about the new technologies, they ended up collaborating with seniors on other aspects of the job. Since the older and younger workers were figuring out how the tech worked, they also needed to figure out how to integrate it into vital day-to-day tasks. So, the novices got to see firsthand how those jobs were done while performing actual work.

For instance, in my research, I saw some residents and senior urologists team up to learn robotic techniques in live surgical procedures. In those cases, the residents got much more actual hands-on operating time than residents who mostly just watched robotic procedures—10 times more. And the quality of that time was far better: Expert and novice were jointly figuring out how to use the tech, just as they had a patient on the table.

Granted, this process isn’t easy. In our research, we found that these collaborations often failed. But when they did work, they were powerfully effective. We need more companies to take the chance and implement this strategy, to figure out how to make it most effective and serve as examples.

It will not only help close the skills gap, it will give old and new workers a new sense of purpose on the job—through strengthened relationships. Research shows very clearly that we get motivation for our work when it builds trust and respect with those who share our values. Progressing to more competence therefore involves questions of the heart, like, “Have I earned this expert’s trust and respect?” or “Does this novice look up to me?”

We often treat these issues as unconnected with hard-nosed skill and results, when they are a core part of why we try at all in the first place. They are the animating force for the journey.

Matthew Beane is an assistant professor at the University of California, Santa Barbara, and author of  “ The Skill Code: How to Save Human Ability in an Age of Intelligent Machines.”

Can You ‘Unboss’ Yourself Without Ruining Your Career?

Sick of managing people? Maybe you should stop.

So many of us stumble into being the boss, or raise our hands because it feels like the only way to get ahead . We’re attracted to the cachet of the title, the promise of more money or the comfort of having a ladder to ascend.

Then come the performance reviews to write, the team drama to adjudicate, the meetings to attend . The job keeps getting harder. Managers oversee nearly three times as many people today as they did in 2017, according to data from research and advisory firm Gartner . Nearly one in five managers says that, given a choice, they’d prefer not to oversee people.

“That’s what we call buyer’s remorse,” says Swagatam Basu , a senior director in Gartner’s human-resources practice.

You can switch back. And your company might be amenable. More are “unbossing” their workplaces by shrinking middle-management layers .

The trick is figuring out a way to maintain your pay and influence. In some companies, the number of people you manage is a proxy for your power. Others now use special individual-contributor tracks, meant to ensure that technical experts have a set path to climb.

You might have to give something up. Making the shift could still feel like a relief.

“It was like, oh, I don’t have to deal with the people issues,” says Suzet McKinney , an executive at Sterling Bay, a Chicago real-estate company. She’d served in leadership positions before. When she started her current role in 2021—no pay cut required—she figured she’d eventually hire direct reports and build out a team. Then she realized she didn’t miss it.

“Managing people would be more of a distraction,” she says.

Making the ask

Dennis Henry , an engineering director overseeing about 45 staffers, was hungry to move to the next managerial rung at software company Okta last year. Then his supervisor explained that would mean even less time to do the technical work he loved. It made the 38-year-old wonder: Did he want to be a boss at all?

“What would hurt more?” Henry asked himself. Giving up managing or giving up coding? The latter felt unfathomable.

He pondered what he’d want if he left management entirely and became an individual contributor, ranking priorities. Maintaining his base salary—just shy of $300,000—was tops. He told his boss that he was happy to stay in his current role if a new opportunity didn’t pan out.

“You have to be ready to hear ‘no,’ ” the Orlando, Fla., resident says.

He got a yes: The company created a new job for him and preserved his pay. After 15 years as a manager, carving out a new kind of authority has been a transition.

As a boss, “I could just say, ‘Do this,’ ” he says. Now he spends more time amassing evidence for his ideas, making his case.

“It is so much harder to convince people that something is the best option,” he says.

The stress of managing

Jenny Blake ’s mental health took a dive after she was promoted to team lead at Google at age 24. She felt stressed and emotionally drained, deeply responsible for her team but beholden to decisions from above, like a department reorganisation ordered up by executives.

A 2024 survey from SHRM, a lobby for human-resources professionals, found that 40% of respondents said their mental health declined when they took on a managerial or leadership role.

Blake switched to an individual contributor job, spending several years rolling out new programs she felt had a much bigger impact than her management. Now an author and speaker focused on careers and business, she recommends broaching the transition conversation by laying out your unique strengths and how they can better serve the company in a new role. Don’t dwell on your distaste for managing people.

Want to ensure the shift isn’t a demotion? Make sure you’re staying close to parts of the business that are directly tied to revenue, she says. Build your reputation externally, speaking at conferences and publishing papers.

“Become an industry expert,” she says.

The reality of switching

Just because a company touts opportunities for individual contributors to grow doesn’t mean you’ll be able to rise to the top unimpeded. A former consultant at a professional-services firm told me that partners who didn’t have their own teams were treated like second-class citizens.

At Launch Potato, a digital-media company based in Delray Beach, Fla., the individual-contributor track tops out several levels below the executive level. Even on the lower rungs, managers have the opportunity to make higher salaries and bonuses than commensurate individual contributors, says Kristopher Osborne , the company’s senior vice president of talent.

“You are getting paid a premium to deal with a lot more issues and challenges,” he says of managers. “People have to be realistic.”

He recommends ambitious individual contributors show they’re bringing leadership to the company in different ways. Can you run strategy initiatives, coach teammates or get swaths of the organization on board with new initiatives?

Letting go

In a previous job, Sheri Byrne-Haber liked managing people and being a “one-stop shop” for her 20-person digital-accessibility department, even as the workload ballooned. So when her boss suggested splitting her role in two, she initially said no.

She reconsidered when performance-review season arrived. She had to write 19.

The company hired a new counterpart for her, charged with managing, and Byrne-Haber focused on strategy. Letting go was harder than she expected. It took her three months to unsubscribe from all the manager-only Slack channels, email lists and meetings she had been looped in on. When colleagues reached out with questions, she’d pause to determine whether the queries were still related to her responsibilities. If not, she forced herself to forward them to the new manager, even when she knew the answer.

“It felt awkward,” says Byrne-Haber, now at work on her own startup. “But that’s not my job anymore.”

Luxury Brands Are in a Winner-Takes-All Phase

Louis Vuitton’s owner designed the medals for the Paris Olympic Games. It can’t be easy to see rival Hermès make off with gold in the second-quarter sales heat.

France’s three most powerful luxury-goods companies reported very mixed second-quarter results last week. On Tuesday, LVMH Moët Hennessy Louis Vuitton said sales in the three months through June rose by a disappointing 1% compared with the same period last year. Gucci owner Kering followed with an 11% fall for the quarter and issued a profit warning. Hermès left its competitors in the dust with a 13% increase in sales over the same period.

Hermès captured more than 100% of the incremental growth in the industry in the latest quarter. Luxury shoppers spent €440 million—equivalent to $477.6 million at current exchange rates—more in the French brand’s stores than they did in the same period of last year. They spent €400 million less on all other luxury brands combined, based on analysis by Bank of America .

This points to a double whammy for high-end brands, which face challenges at both ends of the consumer spectrum they serve.

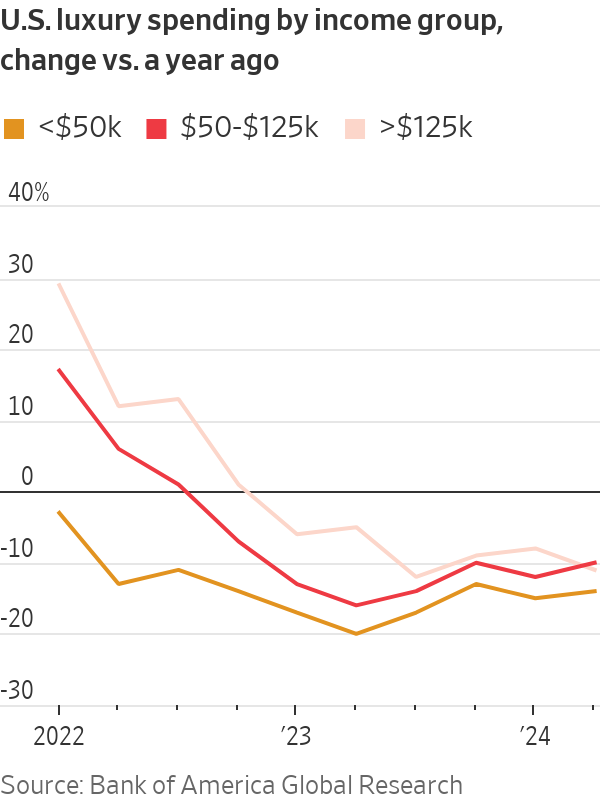
It has been clear for months that middle-class shoppers in the U.S. and China, the luxury industry’s two most important markets, have reined in their purchasing.

Chinese consumers are saving rather than spending because the value of their homes is falling. Lower-income and middle-income Americans who developed a taste for luxury during the pandemic have pulled back sharply as they have burned through excess savings.

Now, wealthy consumers, too, seem to be getting choosier about which brands they will and won’t buy. Hermès Chief Executive Axel Dumas said there is a “flight to quality” under way in the luxury industry. This shift is benefiting the Birkin handbag maker , which has a reputation for timeless designs.

Chinese buyers in particular are avoiding flashy and logo-heavy brands as worries about the country’s economy and real-estate challenges grow.

Jewellery sales are also holding up as shoppers look for goods that are more likely to hold their value than clothing or handbags. Cartier’s owner Richemont said its jewellery sales rose 4% in the quarter, although the company’s overall sales were weighed down by weak demand for its watch and fashion brands. Kering jewellery labels Boucheron and Pomellato were rare bright spots in its portfolio.

The outlook is harsh for brands such as Gucci and Burberry that are in turnaround mode. The latter issued a profit warning earlier this month and replaced its CEO in an admission that a years-long push to make the British trench-coat maker more exclusive had failed. Its shares have fallen to levels not seen since 2010.

Both brands face an uphill battle to lure shoppers. Neither Gucci nor Burberry is known for the classic designs now in vogue. The labels might also have exacerbated the slump, as the sharp price increases that luxury brands implemented in recent years have sidelined aspirational shoppers.

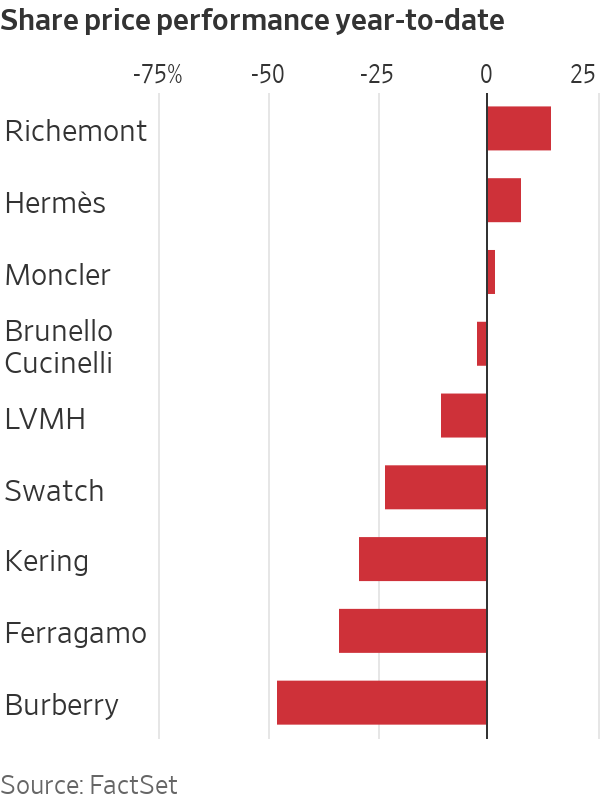
Luxury stocks are diverging. Shares in Richemont and Hermès have gained 15% and 8% respectively so far this year, with everyone else in the red.

Investors are taking their cue from wealthy shoppers: In troubled times, the most exclusive brands are the safest bet.

Driving Lamborghini’s $600,000 Ultra-Powerful Plug-In Hybrid

No longer are supercars powered strictly by muscular V8 and V12 engines, producing a mighty roar as they burn gallons of gas at a ferocious rate. Today’s entries can have hybrid, plug-in hybrid, or pure electric drive. But they’re still awesomely fast, with neck-snapping acceleration.

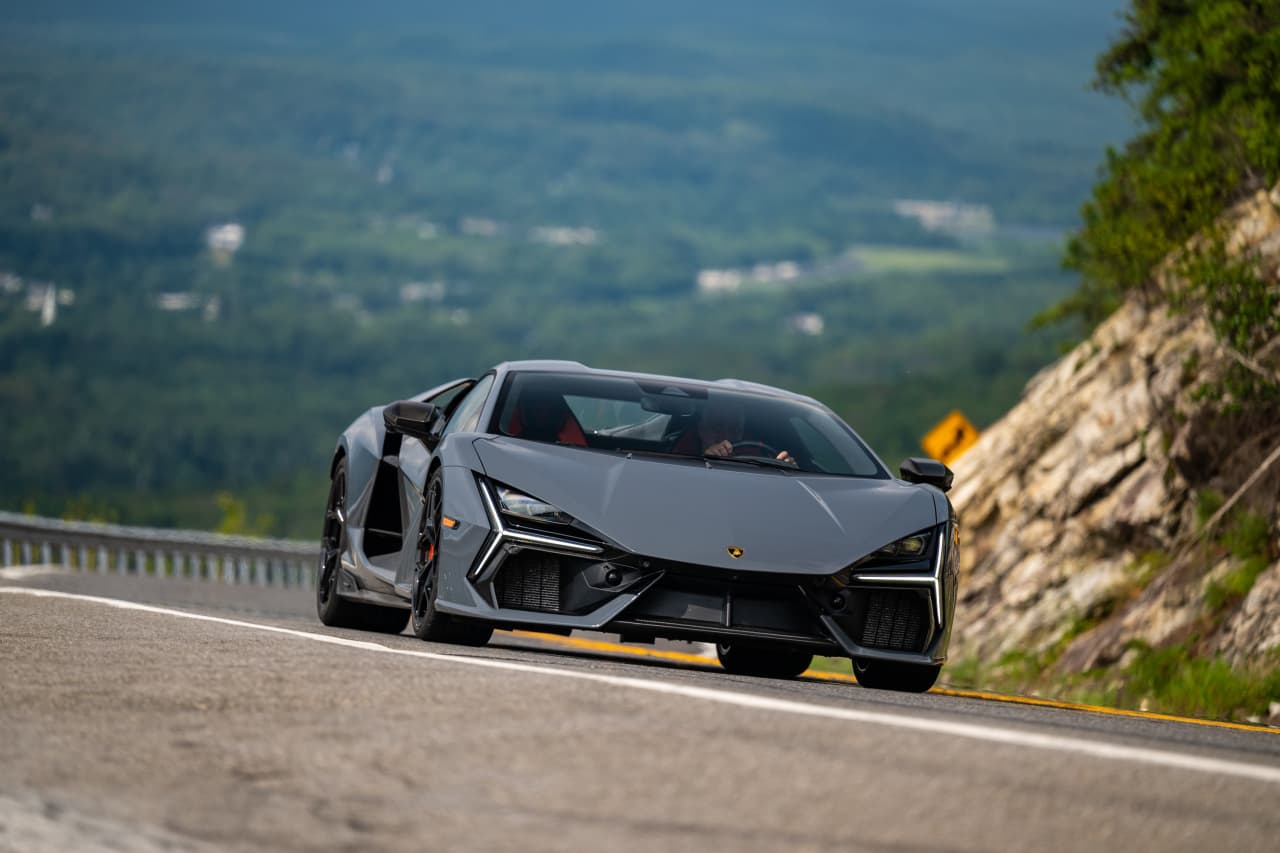
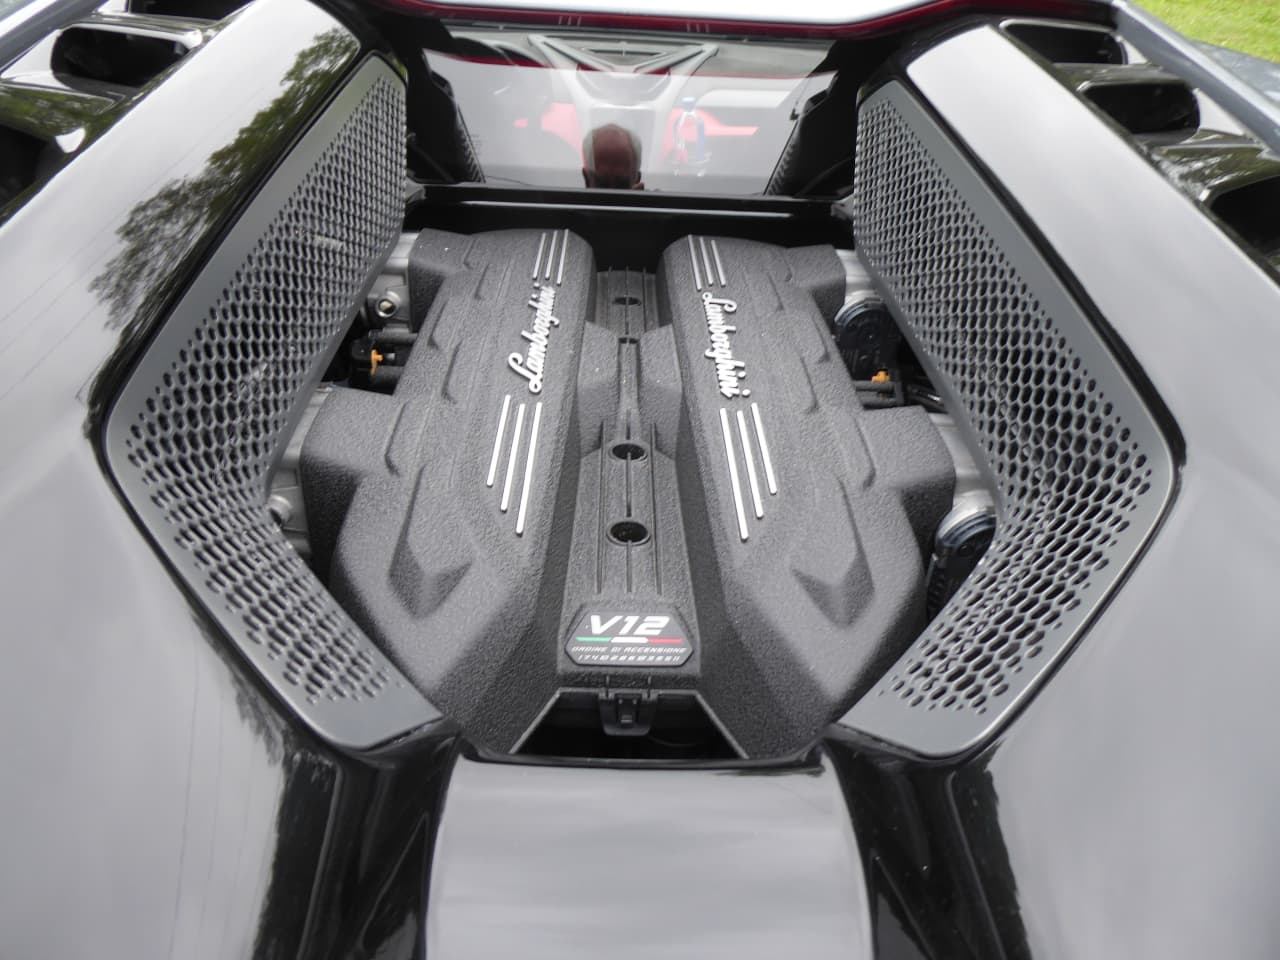
The new Lamborghini Revuelto, a novel form of plug-in hybrid, puts out an eye-opening 1,001 horsepower (with 739 pound-feet of torque) via a combination of three electric motors (two on the front axle) and a mid-mounted—and exposed to the elements—V12 that, by itself, produces 825 horsepower. It manages to produce more power with some beneficial weight loss. That’s coupled to an eight-speed dual-clutch automatic (with manual paddles) and a 3.8-kilowatt-hour battery pack (with LG cells) that gives the Revuelto five or six miles of all-electric travel.

Hybrid drive in the Revuelto is not so much to achieve better fuel economy, though that’s one result, but is primarily a way of boosting power output as needed. It also yields all-wheel drive. Sales started early this year, and Lamborghini plans to produce about 1,500 to 1,600 Revueltos annually (with the supply limited by the company’s ability to produce its carbon-fiber structure). The inventory is sold out until 2026. As is true of many supercar companies, the SUV is the biggest seller—Lamborghini produces about 5,000 Urus SUV models each year.

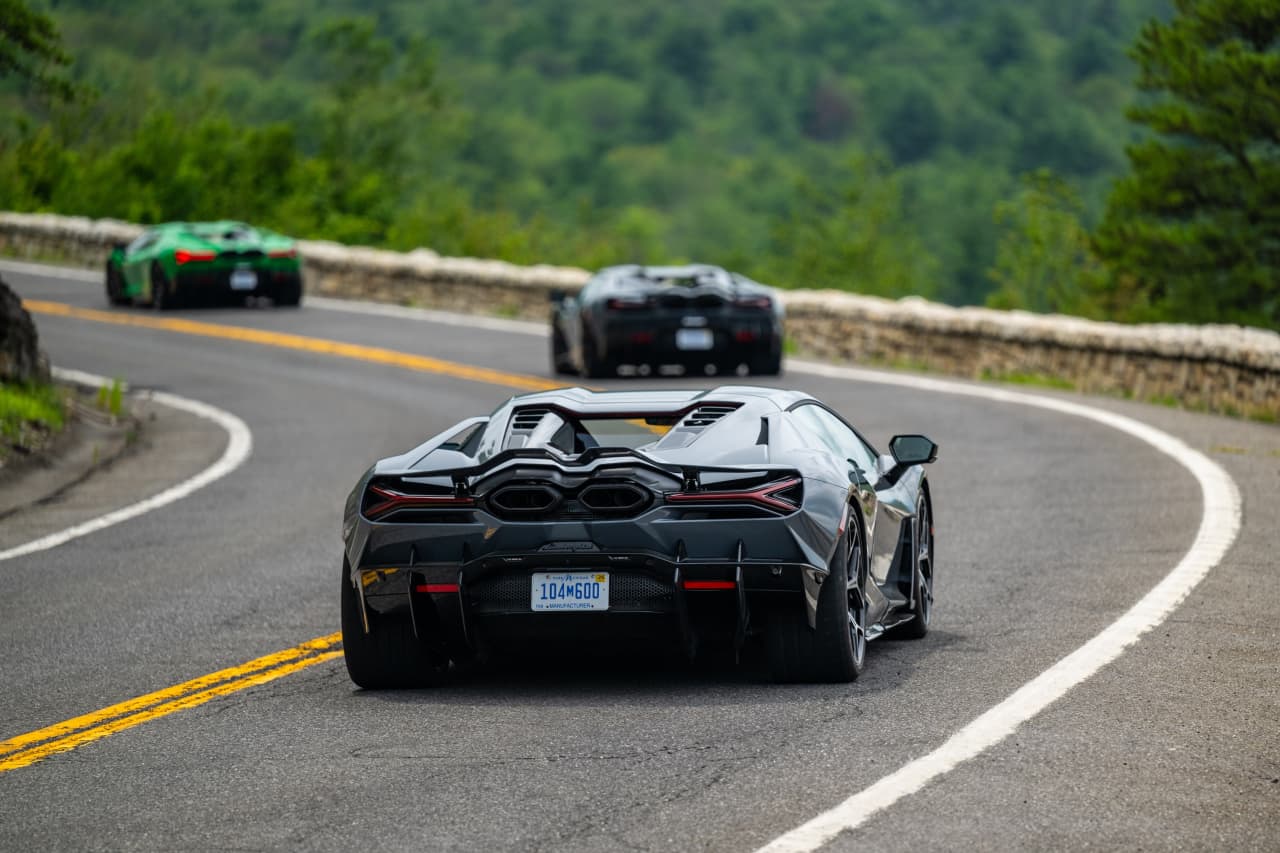
The Lamborghini Revueltos in convoy in the Hudson Valley.
Lamborghini photo

The list price of the 2024 Revuelto is US$604,363. As tested, with the biggest option being US$13,100 for the special greyish paint, the bottom line was US$681,258. Lamborghini handed over the Revuelto keys at the 140-acre Wildflower Farms resort in Gardiner, N.Y., for a 90-minute drive around the scenic Hudson Valley. Although the car is capable of a stated 217 miles per hour in the right context, it was still huge fun to drive it at much more moderate speeds on the curvy local roads.

Matteo Ortenzi, product line director for the Revuelto, explained that having two motors up front increases the opportunity for effective torque vectoring, which improves handling by delivering power to the individual wheels as needed. “The feel is of a lighter and more powerful car,” Ortenzi says. “We didn’t build the Revuelto just to say we did a hybrid.”

As in other hybrids, the Revuelto returns power to the battery on deceleration, a process called “regenerative” braking or in Ortenzi’s words, “using negative torque.” After the 90-minute drive, the Revuelto still had a 90% charge. Lamborghini doesn’t think owners will need to plug it in often, though it provides a charging cord. The charge portal is actually under the front hood, a “frunk” where the car has its limited luggage space.

A row of Revueltos with scissor doors up.
Jim Motavalli photo

Entering through the vertically opening scissor doors requires some agility, but soon becomes second nature. Leg room is good, and the bolstered seats hold the driver in firmly—a good thing considering the speeds and g-forces the car can achieve. The gauges are brightly digital, with huge single-digit numbers for the gear selected. There’s an 8.4-inch touchscreen mounted centrally, and a third 12.3-inch unit for the passenger. The start-stop button is under a military-grade protective cover.

The drive started in EV mode, yielding a quiet getaway that didn’t disturb resort guests. Small dials on the dash control the driving modes. Città (city) is for city electric, Strada (street) for comfortable cruising, Sport (self-explanatory), and Corsa (race, for total performance).

All the modes were sampled, but Strada was a nice balance of performance and driving pleasure. Sometimes using paddles seems not worth the bother, but in the Revuelto the big flippers provided instant gear changes and a nice feeling of control. Slowing down, the transmission acts on its own to downshift. Everything works together: the tight steering (with rear-wheel steering, too), the firm but not harsh suspension, and the hugely reassuring carbon-ceramic brakes. The engine barks out a very Italian song. It’s quite a driver’s car, though not one that can take the family to Disneyland.

The Revueltos engine is exposed to the elements.
Jim Motavalli photo

In the classic muscle car, huge V8 engines were stuffed under the hoods of regular passenger vehicles, sometimes without much thought as to how the powerful result would get around corners or stop. The Revuelto, despite that fearsome 1,001 horsepower, seems to have been fully engineered to handle what it puts on the ground. It can reach 62 miles per hour in 2.5 seconds, with the driver in firm control.

Plug-in hybrids like the Revuelto are a big step toward battery EVs. Lamborghini showed the Lanzador, a fully electric concept car, during Monterey Car Week in 2023 . Exactly when a production model will appear is unclear. “It’s not when, but how,” Ortenzi says. “The world doesn’t need just another electric car; it needs an electric Lamborghini.”