Central Banks Are Stuck in a Rinse-and-Repeat Cycle of Crises

Central banks may be accidentally subsidizing government borrowing through their efforts to prevent a repeat of past market blowups, and policymakers are starting to worry that anticrisis lending facilities could even be interfering with their own monetary policy.

The source of the problem is the switch from central banks being the lender of last resort to, in 2008 and 2020, also being market makers of last resort, ensuring corporate—and government—debt markets keep functioning. During a crisis, support is often essential to prevent a downward spiral that destroys the financial system.

But backstopping markets removes a key risk and encourages more borrowing—especially for the hedge funds that now own trillions of dollars of U.S. Treasurys.

“Ironically, vulnerability is created by mechanisms that were introduced to reduce vulnerability,” said Huw Pill, the Bank of England’s chief economist, one of those growing concerned, in an interview. “So, it’s a bit like a whack-a-mole kind of story.”

Offering either an explicit or implied guarantee that government-funding markets will remain open and liquid means hedge funds have less risk of being unable to finance highly leveraged trades. This is particularly true for the overnight repurchase, or repo, market, where borrowers pledge bonds for cash. The result has been a huge expansion of two popular government bond trades, arbitraging Treasurys or British gilts against bond futures or swaps.

The scale is extraordinary: The Dallas Fed estimates hedge funds ended last year with $2.4 trillion of Treasurys, up from $600 billion a decade earlier. Because the profits on each trade are tiny, hedge funds have to leverage as much as 100 times to get worthwhile returns, creating new risks.

This might sound abstruse. But in 2020, it was the Treasury basis trade blowing up that forced the Fed to intervene. In 2025, signs of trouble in the swap trade pushed President Trump to retreat from his tariff plan.

Pill worries that the reassurance central-bank policy provides bleeds into monetary policy by boosting borrowing. This, in turn, keeps government-debt yields lower than they otherwise would be.

“There’s lots of gilts to be bought,” he says. “How do you support that buying of gilts? You make it attractive. How do you make it attractive? Well, there are some imperfections in the market. So those imperfections create profit opportunities, but they’re not very big. So how do you make them more meaningful? You allow leverage to build up.”

“That’s good for the government because it gets to sell the gilts at a lower [yield] than it otherwise would. It’s good for the financial sector because they’re able to extract these rents effectively. And it’s good for the central bank because the market seems to be liquid and functioning. But all of those things are true until they’re not true.”

When it goes wrong, the more leverage, the worse the problem. And the worse the problem, the more likely it becomes that central banks have to create yet more special tools to address it. That then spurs the next buildup of leverage.

Pill thinks more effort is needed to come up with a modern version of the Bagehot Doctrine. Walter Bagehot, the 19th-century editor of the Economist magazine, summed up the role of the central bank as being to lend to banks freely, against good collateral, at a penalty rate. Access to instant cash helps banks withstand runs. The fact the central bank is offering a backstop should make the run less likely, and shareholders are penalized, through the penalty rate, if it is used.

Illustration of economist and journalist Walter Bagehot in profile.
English economist and journalist Walter Bagehot. Hulton Archive/Getty Images

Tools for saving markets from drying up are more haphazard. In 2020 the Fed, BOE and others just bought lots of government debt to inject liquidity into markets. That worked because, even though quantitative easing is also a monetary policy tool, they also wanted easier money.

Unfortunately, that created what Pill described as a tinderbox, ignited by the energy crisis after Russia invaded Ukraine. The excess money creation from left over from emergency QE then fanned the flames of inflation. This made it much harder to calibrate monetary policy when central banks decided to tighten (although policymakers were also, in my view, far too slow to recognize inflation).

Pill points to the “temporary, targeted” BOE buying of gilts amid the forced selling by leveraged pension funds after Britain’s botched tax-cut plan in September 2022 as a successful model. At a time when the BOE was trying to tighten monetary policy, it intervened in a way that stopped the pension fund selling spiral and stabilized gilts. Yet the central bank maintained tight monetary policy.

Bagehot would recognize the goal: Reduce the encouragement to take risk, known as moral hazard, that offering guarantees in advance creates, but retain the ability to mount a rescue in a crisis.

Unfortunately, much of central banking is going backward on this. Moral hazard is increasing, even for banks. In the 2023 bank bailout, the Fed accepted less-than-full collateral, recognizing Treasury bonds at face value rather than their (much lower) market value.

The emergency rescue facility then became a funding facility that even healthy banks chose to tap—in effect easing monetary policy by the back door and prompting the Fed to tighten the terms before it ended. Something similar could be under way with Japan’s plans to use an emergency Fed loan facility to raise cash to prop up the yen without having to sell its hoard of Treasurys.

I don’t know how to break the cycle of crises needing rescues that lead to more leverage and new crises. And I’m concerned we’re firmly into the added-leverage phase of the latest cycle.

At least central bankers are still thinking about it, even if they don’t, so far, have good answers.
Meta PR Goes Back to Playing Offense

“Call us optimists. Call us dreamers. Call us whatever the hell you want, but we’re betting on people, and we like those odds. The future is for everyone.”

That ad copy is from the voice-over of a July Meta Platforms META -3.38%.

 spot that’s been part of a public-relations blitz to position Meta as the humanist AI company. The message was undercut by the ad’s inclusion of David Bowie’s “Five Years,” a brooding 1972 song about an impending apocalypse. But this week CEO Mark Zuckerberg left no ambiguity, publishing a 6,500-word manifesto—about 10 times the length of this newsletter—with a title that echoed the ad: “The Future is for Everyone.”

That seems to be Meta’s new tagline. In light of sinking public opinion and the company’s thousands of lawsuits from states, school districts, parents, and users, Meta’s public relations have been defensive. This push represents a return to offense, with a chance to distinguish Meta’s approach to AI from other labs like OpenAI, Anthropic, or SpaceX SPCX +9.65%.

“It is surprising that the discourse from many developing AI is so filled with doom,” Zuckerberg wrote. “I do not understand why anyone who believes that AI will eliminate most jobs and much of humanity’s relevance would rush to build that future.”

Zuckerberg frames what sort of future we build with AI as the central issue of our time. “We believe that delivering superintelligence to everyone is the way to answer this question,” he says. “This has the potential to begin a new era of personal empowerment where individuals can use this powerful new capability to reach their full potential, pursue their interests, and improve their lives and the world more than ever before.”

The flood of words belies the situation on the ground in mid-2026. Americans, at least, have a love-hate affair with social media. A November Pew Research Center poll reported that 71% of U.S. adults used Facebook, and 51% used Instagram. Worldwide, 3.6 billion people use at least one Meta app every day.

But in a Reuters/Ipsos poll conducted in July and August, 61% of respondents said they wanted more government oversight of social media, and two-thirds supported laws to keep children under 16 years old off the platforms. When it comes to Meta in particular, in the 2026 Axios Harris 100, an annual poll about corporate reputation, Meta placed 96th out of 100. It’s only above two other social media companies, Chinese ultracheap retailer Temu, and Spirit Airlines, a defunct air carrier. Regarding ethics, Meta came in last, and it was only ahead of TikTok in trust.

The steady drip of headlines in the teen social media trials isn’t helping. Last week, Meta lost a judgment in New Mexico state court that raised their liability in that relatively small jurisdiction to nearly $1 billion dollars. On Wednesday, jury selection began for a federal case with four states suing Meta over addictive product design, and false marketing that said its platforms were safe for teenagers. In July, Meta claimed that the states are asking for a total of $1.4 trillion in damages, in addition to design changes in the apps. This is part of a multidistrict litigation, where thousands of federal trials with social media defendants are coordinated in Judge Yvonne Gonzalez Rogers’ district courthouse in Oakland, Calif.

There is a separate such group of thousands of cases in California state court, mostly with individual plaintiffs. The steady drip of bad headlines from the courts will continue unless Meta decides to settle en masse.

Meanwhile, in the second quarter, Meta booked “$2.40 billion of charges related to legal proceedings,” according to its quarterly filing. That may be just the beginning.

Zuckerberg spent 6,500 words getting his utopian message out, but I can sum it up in two: Trust us. The evidence is that Meta has a long way to go to win back that trust.

Why Apple Stock Just Got Downgraded to Sell

Apple AAPL -1.53% stock was downgraded by a major Wall Street firm on Monday, as an analyst predicted that a radical iPhone redesign has been scrapped.

Jefferies analyst Edison Lee cut his rating on Apple to Underperform—generally graded as a moderate Sell rating—from Hold. He also slashed his price target to $263.66 from $285.56, placing it among the lowest on Wall Street.

The downgrade hinges on the suspected cancellation of Apple’s all-glass iPhone. Although the project was reported to be in development as far back as 2025 and rumored to launch as early as 2027, Apple never commented on the speculation. However, the company quietly filed a patent application for a “six-sided glass enclosure” in 2019.

While Jefferies once viewed the release of an all-glass iPhone as plausible, Lee believes development has come to a halt. According to the analyst, supply-chain checks suggest the project was canceled due to “poor production yield.” This refers to the percentage of defect-free units successfully generated during manufacturing.

Lee views the decision as “a major setback to efforts to bring in higher-priced iPhones amid soaring memory costs.” Had it launched in September 2027 to commemorate the iPhone’s 20th anniversary, the device would have carried an estimated blended retail price of $2,060—higher than the average price of any previous model.

“More importantly, we believe the plan was to extend the all-glass features to future iPhone Pro and Pro Max models, further raising their average selling price and margin,” Lee wrote. He believes an all-glass model would have been a crucial defense against soaring memory costs, warning that Apple otherwise faces lower prices for years to come.

In the same breath, the analyst provided a conservative outlook on both Apple’s AI strategy and component costs for the iPhone 19 Pro Max, which is slated for release in 2027. Other supply-chain checks suggest that Apple is considering an upgrade for the iPhone 19 Pro Max, potentially increasing its memory to 16 gigabytes from 12 gigabytes.

In Lee’s view, the slow rollout of Apple Intelligence makes it difficult for Apple to justify the expense of equipping its phones with more memory. Extra RAM is needed to run complex AI models directly on a device.

Apple shares dropped 1.5% on Monday as the tech-heavy Nasdaq Composite COMP -0.32% index fell 0.3%. Heading into the session, Apple had gained over 15% in 2026, marginally outperforming the index.

The stock’s momentum stalled last month when underwhelming fiscal third-quarter earnings triggered a selloff that erased $359 billion in market capitalization, allowing Nvidia  NVDA -2.86% to overtake Apple as the world’s most valuable company.

Lee isn’t the only analyst to sour on Apple stock in recent weeks. KeyBanc analyst Brandon Nispel downgraded shares to Underweight from Sector Weight in July, arguing that Apple’s growth was beginning to stall following a boost in 2025. Sluggish iPhone sales could drag down other hardware categories, Nispel wrote, making the stock look “too expensive” over time.

Even with this recent shift in sentiment, Wall Street hasn’t lost faith in Apple. Of 51 analysts surveyed by FactSet, 32 rate the stock a Buy or the equivalent. Fourteen maintain a Hold rating, while just five—Lee and Nispel included—have issued a negative opinion on the shares.

Mortgage Rates Are All Over the Place—and That Could Be Good for Buyers

The typically busy spring season for the housing market was a dud, and the summer isn’t looking much brighter.

Housing services companies like Zillow Group and Rocket RKT +3.78% were loud and clear last week on earnings calls: Rocket CEO Varun Krishna called the quarter through June “one of the toughest spring housing markets in years.”

Jeremy Hofmann, Zillow’s chief financial officer, said on a conference call that the company predicted earlier this year that the market for mortgages would be flat. “We actually now think it’s going to be down low-to-mid-single digits,” he said.

The rest of 2026 will remain challenging for mortgage origination volume, says KBW analyst Bose George. The question now is what happens in 2027. “If mortgage rates remain [around] 6.75%, I think that’s going to be challenging even for next year,” he says.

But what’s bad news for mortgage companies could be a positive for bargain hunters. Buyers can expect prices to grow more slowly—or mildly decline—with less competition as long as mortgage rates remain unpredictable.

Mortgage rates at the beginning of the year were solidly below year-ago levels, notes Zillow senior economist Kara Ng. But they surpassed last year’s levels recently, she adds, referencing Freddie Mac’s weekly survey of 30-year fixed mortgage rates. Last week’s reading, at 6.69%, was higher than year-ago levels for the first time in 2026.

“From the affordability point of view, it’s going to get more challenging in the second half of the year,” she says. “And when affordability gets more challenging, that impacts sales and home price appreciation.”

Mortgage application data tracked by the Mortgage Bankers Association has cooled since the beginning of the year. The trade group expects that the number of mortgage originations in the remaining two quarters will lag behind last year’s levels, after exceeding 2025 levels in the first half.

Rocket’s early-stage data—which the company told Barron’s it derives from its brokerage Redfin, demand for its mortgage products, and signs in its servicing portfolio that a homeowner is preparing to refinance or move—“leads us to expect the third quarter mortgage market to be smaller than the second,” Chief Financial Officer Brian Brown, said on the company’s call. He added that such an occurrence is “something the industry has not seen since 2022.”

Prices will be about flat nationally, Ng says. Zillow’s most recent forecast, which shows how values are expected to change in the year ending June 2027, show them dropping in roughly half of the 100 largest U.S. metros for which data is available.

Buyers aren’t rushing in at a time when mortgage costs are rising and unpredictable. But those with the right combination of patience and cash could stand to benefit. “If you are financially qualified to buy a starter home, you are facing less competition and you’re more likely to get a price cut,” Ng says.

Why These Bargain Stocks Can Outshine Gold

Gold is one of the market’s go-to hedges in rocky times. Don’t forget that gold miners’ stocks are too.

The stock market’s gains in 2026 belie the rocky macroeconomic picture: elevated inflation, heightened geopolitical tensions, and jitters about the artificial-intelligence trade. That backdrop, in theory, should be the time for gold to shine. Instead, the price of the yellow metal has tumbled more than 5% so far, after last year’s blistering 65% rally. In part, the U.S. dollar’s recovery has stymied gold, which benefited from the greenback’s weakness in 2025.

Even with the precious metal’s recent weakness, gold mining stocks could be the best way to profit from this year’s uncertainty.

Gold miners “are a valuable hedge against macro risks that would likely be damaging for equities,” BCA Research’s Noah Weisberger and Rishabh Shah wrote this week.

Concerns about the Federal Reserve’s next moves to tackle inflation, the increasingly crowded AI trade, and steep valuations for tech stocks are just some of the drivers that could help gold’s price get on even footing— and lead to even bigger gains for miner stocks.

These stocks’ prices tend to outpace gold’s moves, because the companies have fixed operational costs. So when gold’s price rallies, their profit margins soar, and vice versa. For instance, the VanEck Gold Miners GDX +7.39% exchange-traded fund has fallen 11% this year as the metal has slumped.

Now, gold’s price just needs to stabilize to help miners’ stocks take off, and that seems to be happening. The precious metal has recently found support above the $4,000 level, and has stuck in a narrow range since the end of June. But its price rose ever so slightly in July, ending a four-month losing streak for the metal. Technical analysis also suggests that gold is due for a comeback.

Barron’s recently wrote that the pullbacks for both gold miners and the metal itself are overdone. Senior technical analyst Doug Busch noted that the VanEck ETF is on the “verge of a breakout” and has the potential to hit $11o in early 2027, up more than 40% from its current price.

Gold miners also have more than their role as a market hedge going for them. Their fundamentals are solid, too, says Chris Mancini, portfolio co-manager of the Gabelli Gold Fund.

“Precious metals miners are generating substantial amounts of free cash flow given profit margins of over $2,000 per ounce, and are returning this cash to shareholders through buybacks and dividends,” he said in an email.

“Buying the miners is a cheap way to get exposure to the price of gold,” he added. His fund owns Newmont NEM +6.71%, a Barron’s stock pick last year, and Agnico Eagle Mines as top holdings, as well as miners Northern Star Resources, Endeavour Mining, and Kinross Gold K+8.59%.

Miners are better businesses than they used to be, the BCA team added.

“Capex is more disciplined, margins are high and rising…and they are largely independent of the AI story,” Weisberger, BCA’s head of equities, and Shah, a senior analyst, wrote.

That last part is key. AI is disrupting the software industry and many other services and information-oriented businesses, and investors have piled into AI stocks. But ChatGPT, Claude, Grok, and other large-language models aren’t going to replace the need to mine for metals.

“Equity portfolios can benefit from exposure to quality that is uncorrelated to AI risk, and gold miners fit the bill,” the BCA team said.

They recommend that investors buy the VanEck Gold Miners ETF, which owns top miners such as Agnico, Barrick Mining ABX +7.24%, and Newmont.

An important bonus for big gold miners’ stocks is that their valuations are attractive after the gold’s pullback, too. The VanEck ETF is now trading at just a little more than nine times next year’s earnings estimates. That’s a big discount to its five-year average price-to-earnings ratio of 14, according to FactSet.

What’s more, the ETF is currently valued at a more than 50% discount to the S&P 500 SPX -0.17%, which is trading for about 19 times earnings estimates for 2027. Mining stocks have typically traded at just a 25% discount to the broader market over the past five years. So there is significant upside for the group if valuations move back toward normal levels.

One factor that complicates mining stocks as a market hedge, of course, is if stocks bounce back, which has been the case so far in August.

But both the market and economic outlooks remain cloudy, and investors remain nervous about the Fed’s next moves and AI stocks. Gold miners should do just fine, even if the anxious mood on Wall Street persists.

This High-Powered Real-Estate Fund Is Run by College Students

On a recent summer Sunday afternoon, Brooks Hiller was hunkered over his laptop at his apartment in Chicago, dialing in to hour three of a marathon series of conference calls on real-estate deals.

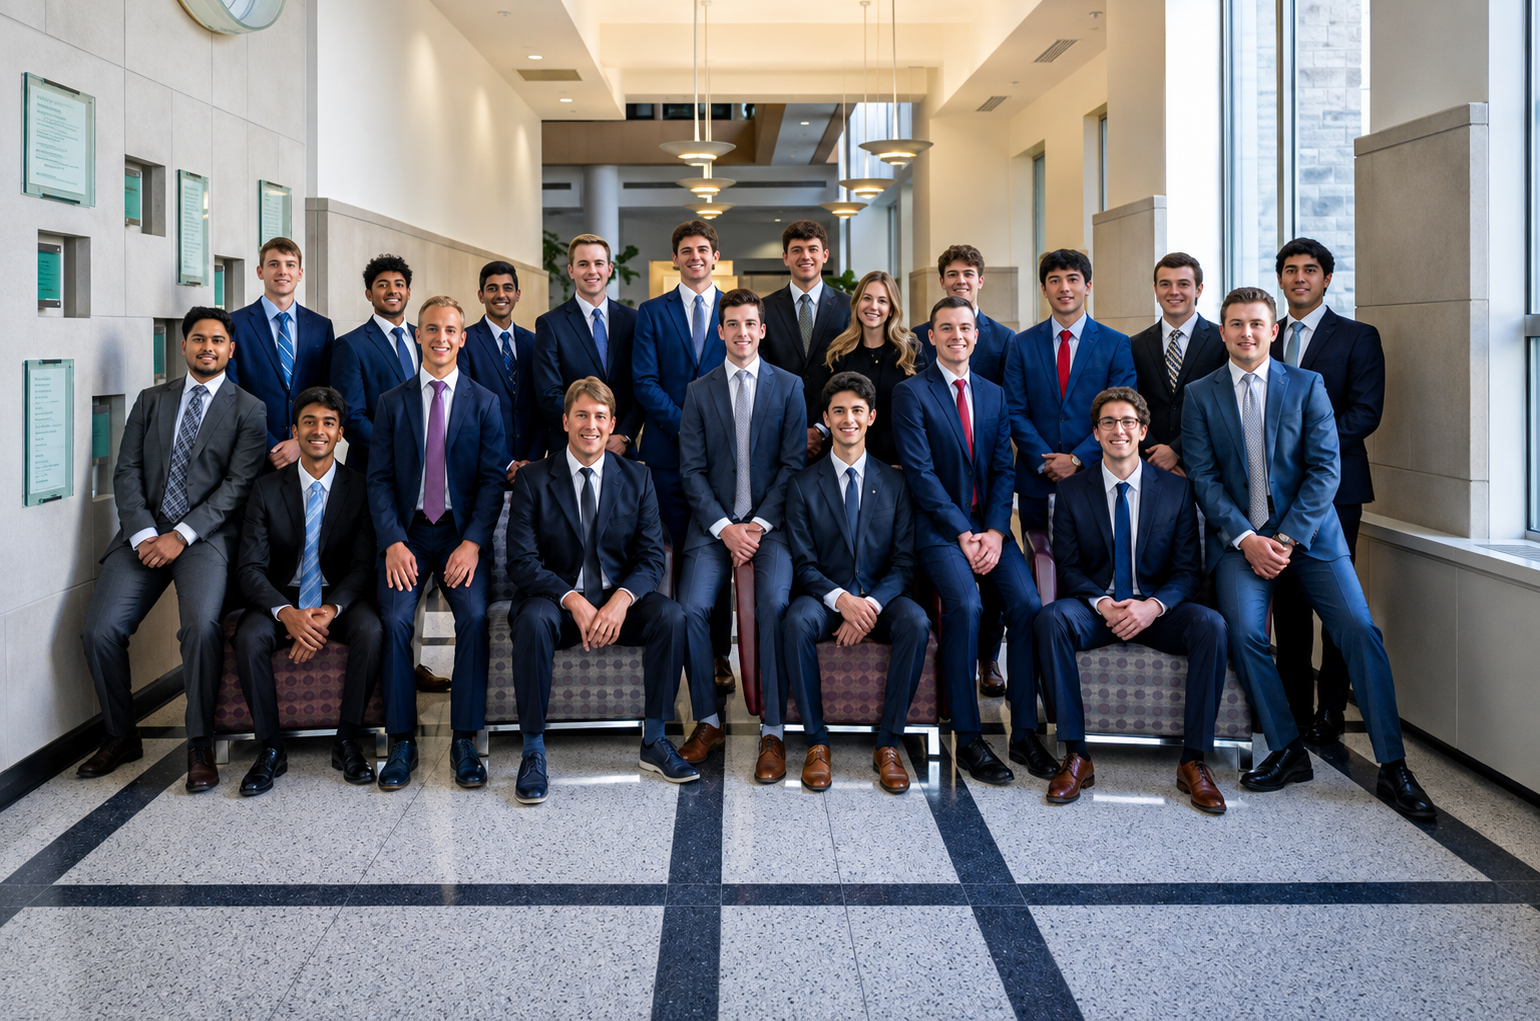
The 21-year-old isn’t a professional, and he doesn’t make a dime from this work. He is a rising senior at Indiana University’s Kelley School of Business, where he leads a team of 20 undergraduates who manage about $12 million in equity.

Those students operate their own real-estate investment business, called Sample Gates Management, named for the Gothic-style limestone arches that are the gateway to the Bloomington campus.

Unlike the many student investment clubs that deploy university money or rely on donations, the Indiana group raises funds from third parties and invests in properties across the country, such as apartment developments and industrial parks.

As a high schooler, Hiller was so enamored with the program—by most accounts, the undergraduate-run real-estate investment group that manages the most capital—that he chose to attend Indiana with hopes of being a part of it.

Brooks Hiller with his parents Jeff and Heather Hiller at the Sample Gates on Indiana University Bloomington's campus.
Brooks Hiller, with his parents Jeff and Heather Hiller, at Indiana University’s Sample Gates in Bloomington in 2023.

“Students get the experience, the school gets a better education for their students, and the investors are making their money back and get to be a part of the program again,” Hiller said. “I really wanted to be part of that.”

The group’s success is emblematic of changes transforming both higher education and the real-estate industry.

An industry that once revolved around information shared at private clubs or events has become a highly digitized landscape. It’s now flooded with standardized public-market data, so much so that undergraduates can readily peer inside and participate on nearly equal footing.

Meanwhile, colleges in recent decades have championed what is called “experiential learning,” encouraging students to do the hands-on work that will teach them the practical job skills they can’t learn in traditional classroom settings. Plus, dozens of universities now offer real-estate degrees, minors or concentrations for undergraduates.

“At its core, this program wouldn’t have existed 30 years ago,” said Harvard University real-estate professor Avis Devine.

This summer, Sample Gates Management sold its first investment, an industrial warehouse development in Indianapolis. In about 16 months, the fund earned a 65% gross profit on that property.

“That’s a really fantastic return in this environment,” one that would be “good for sort of any professional firm, not just students,” said Tim Morris, a member of the board responsible for approving the students’ investments, who is a founder and co-managing partner of the real-estate firm Proprium Capital Partners.

That property was an “easy yes” investment, Tom Peck, the students’ faculty adviser, recalled. It would diversify the group’s investment portfolio, and a reliable tenant was committed to leasing the building once it was finished, Peck said.

Most of the fund remains tied up in investments, making it difficult to gauge exactly how well it is performing overall.

Aerial view of a large industrial warehouse building under construction with dirt lots and a few trucks.
Sample Gates Management sold its first investment property, an Indianapolis warehouse development, this summer. Gershman Partners/Citimark

A decade ago, there were only a few student-managed real-estate funds in the country. Today, there are at least 18, and two more are set to launch this school year, according to Mariya Letdin, a real-estate professor at Florida State University who has researched student-managed investment funds and advises one herself.

And yet, although a program like Sample Gates is an attractive resume line that provides unique experience among undergraduates, it isn’t necessarily a launching pad to help students secure jobs. Because of Wall Street’s summer-internship pipelines and early recruiting timelines, many of the 20 seniors in the group have already secured full-time jobs at global giants before they even touch Sample Gates funds.

In fact, the students’ professional experience—some of them participate in internships all three summers of college—is often a boon for Sample Gates. Students’ stints at institutional shops have left them with a “networking mindset” that “snowballs very quickly into a really, really good Rolodex,” Morris said.

At the Kelley School, where currently 278 students are majoring in real estate, faculty picked only 20 to manage the private-equity fund. The rising seniors were selected from Kelley’s already competitive roughly 60-student commercial real-estate workshop, in which students analyze deals and pitch them to mock committees.

In 2022, for the group’s first round of fundraising, Sample Gates raised $4.2 million from 46 investors, 40% more than their goal of $3 million. Last year’s cohort raised $7.8 million from 74 investors in the second round of fundraising, with one investor forking over $700,000. Some investors put money into both funds.

Construction site with two workers walking past new buildings.
The construction site of another project that Sample Gates Management invested in. Thanasi Georgiadis

Many of the investors are Indiana alumni now working in the real-estate industry themselves. They expect the students to return a profit, but they are also enthusiastic about fostering the young program and meeting standout students.

The student managers screen between three and eight deals each week, which could mean they evaluate up to 400 potential investments a year. However, between 2023 and 2025, they selected only 12 investments, ranging in location from Indiana to Arizona.

Once a potential investment passes an initial screening, a team builds financial models and meets with prospective partners to pressure-test the viability of a deal.

For students to move forward with an investment, they must present it to their investment committee, a board of 10 seasoned real-estate executives. The committee has to sign off on all deals, and they reject roughly a third of the ones the undergraduates bring to the table.

And if the students think they can pitch an investment without getting their eyes on the physical property—regardless of where it is located— they would best think again.

Some observers predict that students might be disappointed when they start their full-time jobs because of the shift from doing the highest-level work of managing a fund to being a lowly analyst at a large firm.

“To have all of these skill sets in a short period of time and then to go be an associate for Blackstone would be mentally defeating,” said Rhett Trees, an investor in Sample Gates and Indiana alum who is the chief executive of a Denver-based real-estate private-equity firm.

Helicopter Parents Are Co-Piloting Their Adult Children’s Careers

Steven Clark had the unpleasant task of firing a 24-year-old—twice. Once was in a brief conversation with the new hire, who’d showed up late or not at all four times in his first week at a construction job.

Then Clark had to do it all over again, this time with the guy’s mother.

She called him a few hours later, pleading to give her son another chance. When Clark told her no, things got heated before he ended the call.

“I said, ‘Look, you know, this is between us and your son. He’s the employee,’” says Clark, who is chief operating officer of a Fairbanks, Alaska-based staffing firm.

Gen Zers make up nearly one-fifth of the adult workforce, and bosses and recruiters say it often feels like the nervous parents who hovered over them through childhood and college are right alongside them. What began as the occasional parent ride-along to a job interview coming out of the Covid era is now full-on career “co-piloting,” said Jasmine Escalera, head career coach at résumé templates service Zety.

More parents are calling up hiring managers, applying for jobs on their adult child’s behalf, and even showing up—or lurking just off-screen—on Zoom calls to help navigate difficult conversations or go over benefits packages.

“The first time it happened, I was appalled,” says Clark, who has fielded calls from parents asking why their child didn’t get a job. “Since then it’s become more of a here-we-go-again reaction.”

Human resource professionals have expressed outrage on social media.

“Parents should not be calling employers to check on their application status or ask questions on behalf of their child,” says Lynne Alba, a director of talent acquisition and physician recruitment at a large health system on Long Island, who vented about the phenomenon in a Tik Tok video she reposted on LinkedIn.

Lynne Alba
Lynne Alba Lynne Alba

At a recent job fair, a mother approached Alba with her daughter’s résumé, explaining that she wanted to work as a nurse. “While I appreciated that she was trying to help, I intentionally shifted my attention to her daughter. No matter what Mom said, I wanted to hear directly from the candidate,” says Alba.

Some parents who step in say it’s a challenging job market for young people, and that they would only intervene in extreme circumstances—social anxiety, a toxic boss, unfair treatment. There’s also a gray area of intervention that some see as an extension of the parental advice and networking help that’s been happening for generations.

Rick Wainschel last year published a post on LinkedIn asking his network to help his daughter, a recent college graduate, find a corporate entry-level position.

Wainschel, a vice president at an automotive marketing technology company, says he doesn’t think his outreach qualifies as helicoptering. “Well, maybe a little,” he said, before quickly adding he was being half tongue-in-cheek. “It was really merely just to help her get a network established. I just think the work world is a challenging place.”

Wainschel’s post, which was OK’d by his daughter on the condition he didn’t embarrass her, didn’t lead to a job but did result in productive conversations, he said. She found a job with a credit union on her own shortly after.

Recruiters and other HR types say aggressive parental involvement signals a lack of independence and raises fears that mom and dad will be checking in regularly if their kid gets hired.

What’s more, they say, such interference rarely, if ever, works.

The phenomenon is becoming so commonplace it made the agenda of human resources organization SHRM’s national conference in June. When James Harrell asked a room of 250 professionals if they ever had a parent calling on behalf of a young employee or coming to an interview, more than half raised their hands.

“The first time it happened to me, I got high up on my soapbox and I shook my fist,” Harrell says. “The 15th time I said, ‘OK, well, I gotta figure out how to do something differently.’”

Harrell helped run an apprenticeship program for high-school students while he was the human capital management chief for the San Antonio Independent School District. To run interference, the district introduced a “signing day” when parents could come and ask questions.

After a Gen Z employee at Nation’s Best Holdings, a chain of hardware and home goods stores, didn’t get an “exceeds expectations” designation on his performance review last year, HR chief Amber Little got a call asking why.

Amber Little
Amber Little Amber Little

It was one of a number of calls from parents her office has picked up recently about issues ranging from negative feedback to understanding which health insurance plan to choose. Little has even noticed parents are now calling in sick for their adult kids.

“Instead of coaching them, they do it for them,” Little says. When it happens, she adds, “we encourage them to tell their child to come talk to us and we will walk them through it.”

A Zety survey of more than 1,000 Gen Zers found 20% had a parent attend a job interview with them.

“You get a sense it’s all hands on deck for some families,” says Keith Wolf, managing partner of recruiting firm Murray Resources in Houston. His office has received emails from parents seeking jobs for their children, and Wolf says he’s always wondered if the kids even knew.

Paul “PB” Branson, who graduated from the University of Missouri-Columbia in May, bristles at the thought. The 22-year-old says while he understands their anxiety, parents shouldn’t be joining their children’s job interviews or contacting employees on their behalf.

“That trend,” he says, “has really hurt my generation by creating this kind of stereotype that we need our hands held.”

The Rise of Million-Dollar Companies With Just One Employee

Ben Broca launched a company last December that offers AI tools to entrepreneurs. He’s already added 10,000 paying customers and is on track to bring in $10 million in revenue this year.

One thing he hasn’t added: any other employees.

The 40-year-old is part of a class of entrepreneurs who are launching, and then often running, new companies on their own. Artificial intelligence tools answer Broca’s emails, help write and debug code, field requests from customers, sign up new subscribers and grant refunds when issues arise.

Broca relishes his ability to make whatever decisions he wants on his own, often from his sun-drenched Sausalito, Calif., living room. “I think compromises make lukewarm results,” he said.

Once upon a time, running a business of a certain size required a team. AI is turning that assumption upside down, and more aspiring entrepreneurs are going it alone.

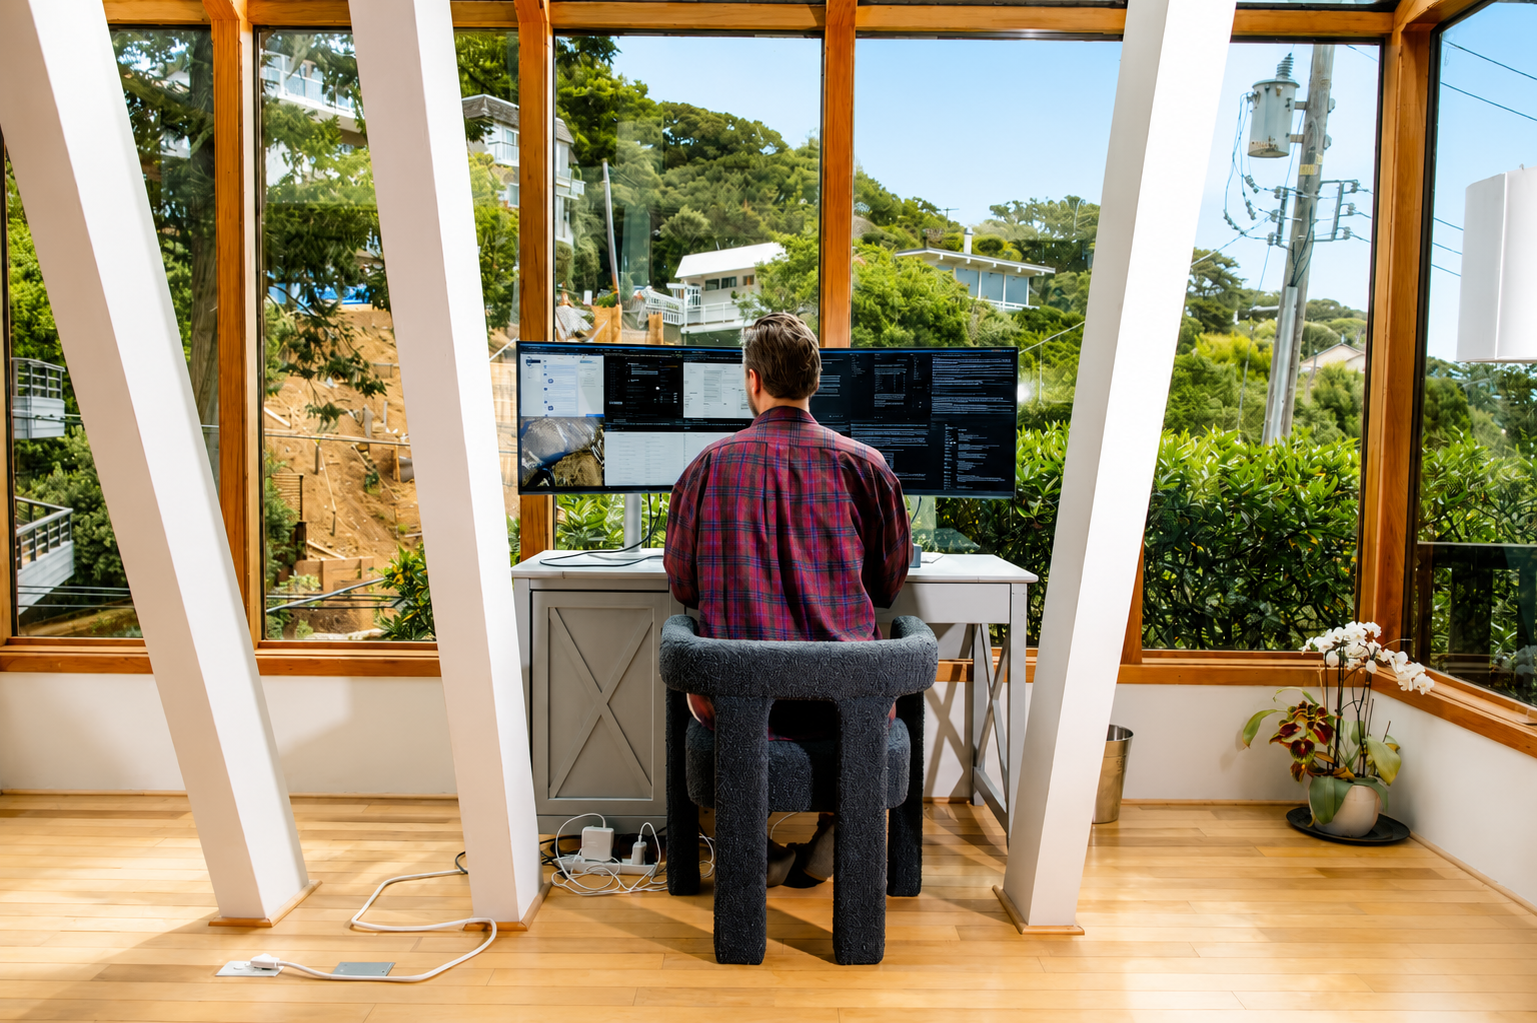
Ben Broca sitting in his home office.
Tech has seen an explosion of solo founders in the past year. Broca said he likes being able to work at his own speed, unencumbered by a team. Jonah Reenders for WSJ

An analysis by the payments company Stripe shows there are thousands of solo operators on the company’s platform that are generating over $1 million in revenue, with their ranks doubling between 2023 and 2025. The number of solo operators crossing the $10 million threshold nearly tripled in that same span.

In the past, people without business contacts or particular savvy might not have known how to get their ideas off the ground, said Ernie Tedeschi, Stripe’s chief economist. “Now, AI can be a built-in business partner,” he said.

AI’s ability to handle various administrative tasks makes it potentially useful for launching solo businesses in many fields. But the technology’s ability to also handle key tasks in tech, like coding, make that field a particular hot spot.

Analyzing Census Bureau data, Bank of America Institute economist Taylor Bowley found that among all industries, new business applications in the information sector have seen the biggest percentage increase—nearly 45%—over the past year. At the same time, the rate of information-sector applicants saying they plan to hire workers has experienced the sharpest decline of any measured industry.

This Census dataset doesn’t track solo-operated businesses. But the numbers broadly show—in tech and beyond—that applications are flat among businesses likely to hire workers, but generally rising elsewhere. Economists say that’s a strong sign that solo operators are on the upswing.

“The bar for getting started has never been lower,” said Julian Weisser, who runs a San Francisco-based accelerator for solo founders working in tech. The accelerator—which offers founders seed money and mentorship in exchange for an equity stake—attracted 4,500 applicants for 10 slots made available in its most recent cycle, nearly five times the number it drew when it launched last May.

Going it alone with AI can still be surprisingly expensive. Broca said he was losing money on many customers’ accounts while paying to access Anthropic’s Claude to run his clients’ requests—that AI company, as well as others, charges based on usage. He has since switched to free open-source AI models from China.

Broca said he has raised $30 million from investors and, at the same time, has saved millions in salary since he hasn’t needed a team of software engineers.

Another risk: If it’s easy for one entrepreneur to launch an AI-assisted business, copying them can be easy, too. This creates anxiety for founders like Troy Johnston, who runs an AI-assisted business alone in Orlando, Fla.

“Everybody has the sword and we all have the ability to unsheathe Excalibur now,” said Johnston, 40, who used AI to code an app that helps people get the most out of credit card benefits. The company makes around $3,000 a month in profit, with no employees, and is continuing to grow.

Headshot of Troy Johnston.
Troy Johnston said AI’s power and ease of use is an incredible boon for entrepreneurs like him—and also a double-edged sword. Luann Koerper

What one-person businesses will mean for the labor market remains to be seen. Polling has shown Americans are worried that AI will replace jobs, and top economists are wrestling with that possibility, too. But AI is also creating lots of new jobs, and the go-it-alone entrepreneurs show how the technology can both open doors and limit employment opportunities.

“If everyone’s hiring less, but you get four times more firms, what does that do to head count?” said Rembrand Koning, an associate professor at Harvard Business School who studies entrepreneurship. He co-authored a recent study that found that among 50,000 startups the researchers examined, those focused on AI tended to operate with 25% fewer employees.

Koning also believes a soft hiring environment that’s left some people mired in long job searches has encouraged more to try their hand at launching businesses.

Some founders cite different motives. “It’s a perfect storm of post-pandemic burnout and a re-evaluation of one’s priorities, and also booming AI and a sense of what’s possible,” said Samir Ahmad, 39, who lives in Breinigsville, Pa.

Two years ago, Ahmad decided to leave the corporate job he had worked at Verizon for almost two decades to start a solo coaching and consulting business. He had been seeing social-media posts touting the ease and virtues of AI, which he used to chart a business plan and help with marketing. “It was like my chief of staff, a second in command,” he said.

The business ultimately petered out within months, though, and Ahmad is now back to a full-time corporate role with a utility company.

For Claire Vo, 41, AI helped her turn a passing impulse into a business. She was working full-time as a tech executive when she tapped AI in late 2023 to help code an app that would help her manage documentation and design for new products, with customers ranging from financial services to healthcare firms.

“I was copying and pasting from ChatGPT,” said Vo, who lives in San Francisco.

Claire Vo smiling into the camera while recording a podcast.
Claire Vo used AI to code an app that’s on track to make seven figures in profit this year. Claire Vo

She put the app online for $1 a month, and within weeks people downloaded it thousands of times. Nearly three years later, Vo’s company—which she ran solo for nine months before hiring an engineer—now has 100,000 users and is on track to make seven figures in profit this year. AI handles the company’s marketing, sales and customer support.

While AI is a shortcut, Vo said her network and credibility in the industry were key. “I think people over-index on how easy AI is and under-index on how much I did to get to this point,” she said.

MAISON de SABRÉ turns luxury shopping into theatre with New York’s Floral Atelier

Product launches used to mean a store window and a press release. MAISON de SABRÉ has other ideas.

The Australian-born luxury house, founded in 2017 by brothers Omar and Zane Sabré, has opened a four-day Floral Atelier in the heart of New York City, transforming a stretch of Manhattan into what it calls an “overgrown botanical landscape” of craftsmanship, floristry, hospitality and music.

It’s the brand’s most ambitious physical activation to date, and the setting for the launch of its new Bloom Collection.

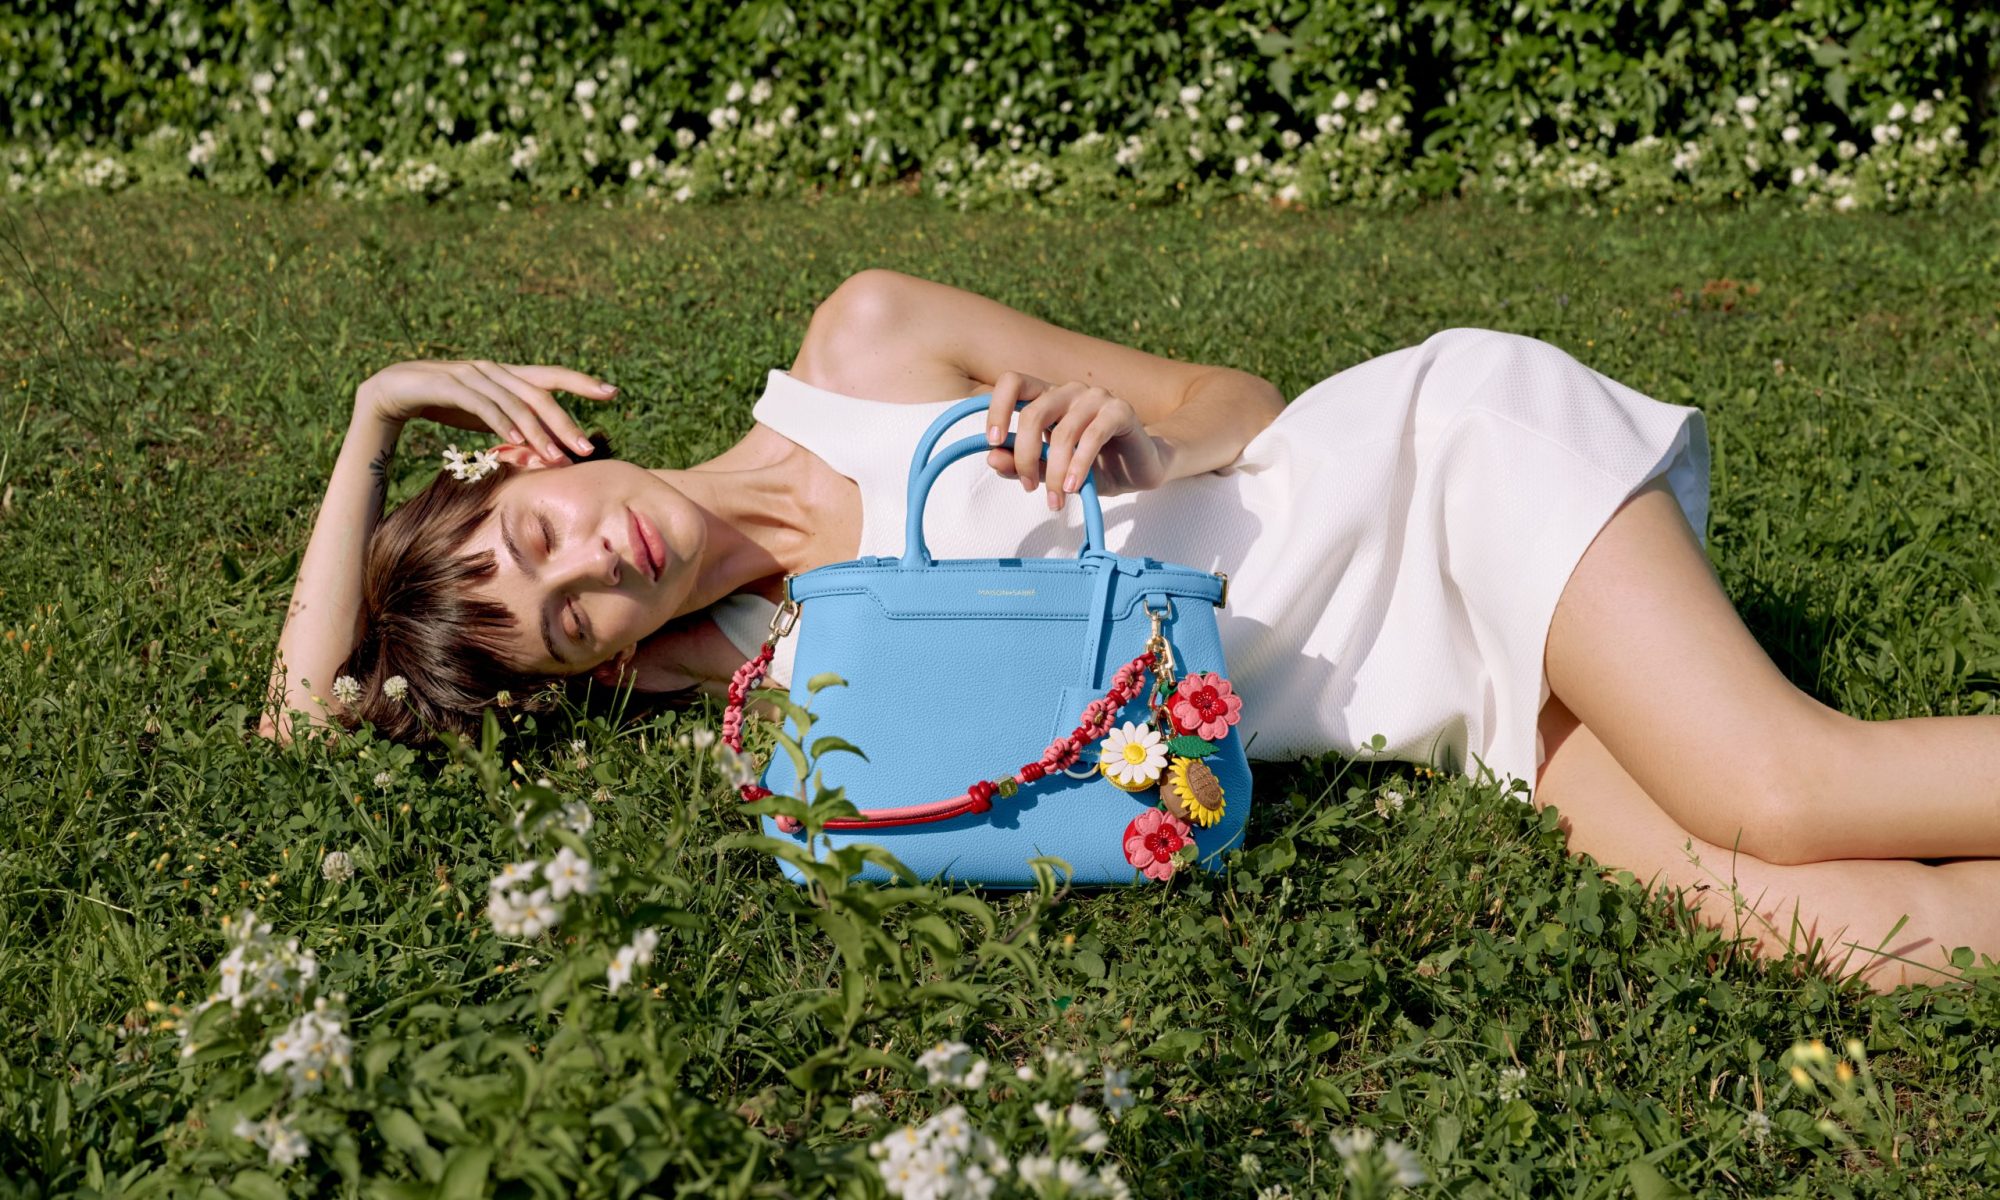
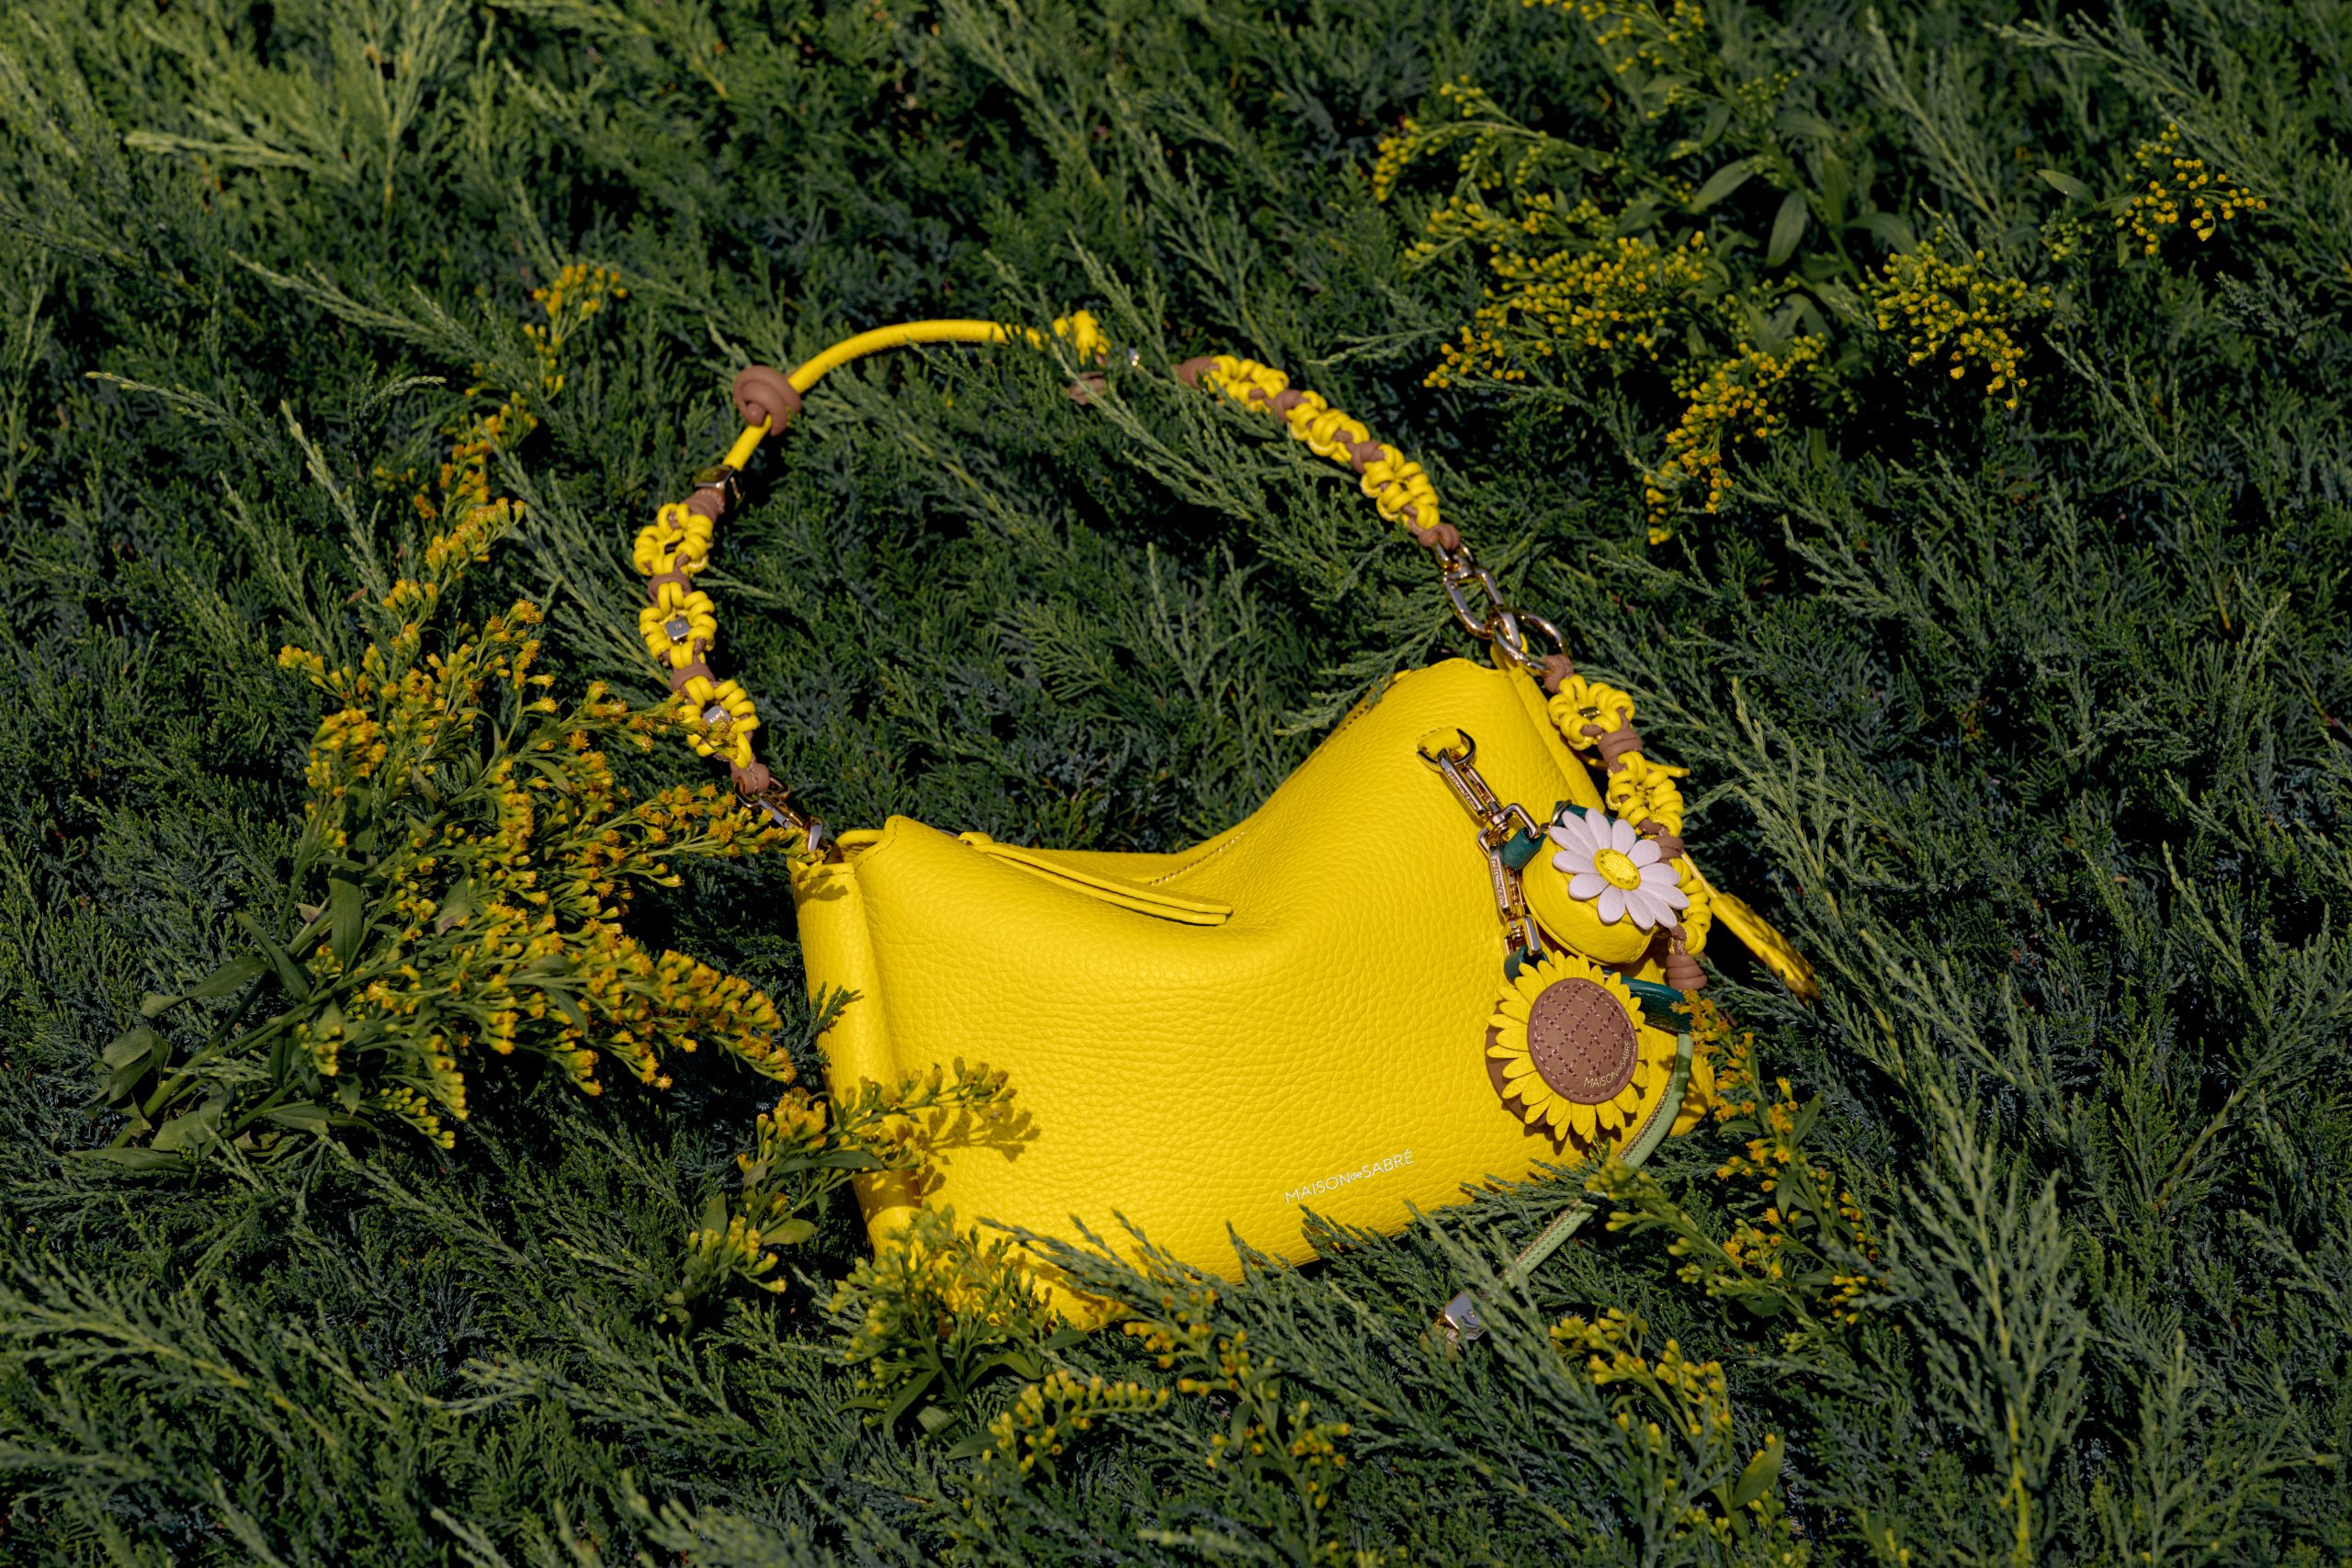
At the centre of the collection are three new SABRÉMOJI flower charms, named Wild Daisy, Sunflower and Cherry Blossom, each made entirely from upcycled leather offcuts and finished with ultrasonic embossing and embroidery.

There’s also the Floral Twist Handle, arguably the house’s most technically demanding piece yet, which takes 36 individual hand-tied knots to form six leather flowers, plus another ten structural knots that let it convert from a hand-carry to a shoulder strap.

A new Floral Wristlet debuts a leather-knotting technique developed specifically for the collection.

Between them, the pieces bring the brand’s product ecosystem to more than 10,000 possible styling combinations, all built from what would otherwise be manufacturing waste.

“Bloom is the latest evolution in the MAISON de SABRÉ product ecosystem, reimagining the handbag as a living canvas,” said co-founder and creative director Omar Sabré. He points to the smaller pieces as proof of intent rather than afterthought: “The smallest products demand extraordinary precision.”

It’s a strategy with numbers behind it.

The brand’s connected styling platform, of which Bloom is the latest chapter, has helped push MAISON de SABRÉ past $100 million in annual revenue and lifted average order value by 45 per cent, evidence that designing products to be added to and reinterpreted has become a genuine commercial engine rather than a marketing line.

The SABRÉMOJI charm platform alone has sold more than 500,000 units globally, with sold-out collaborations including Pokémon, Hello Kitty and Mr Men Little Miss.

For co-founder and managing director Zane Sabré, the Atelier is really about where the relationship with a customer begins.

“Retail is no longer just about selling products; there’s been a structural shift toward experience and participation,” he said.

“With Bloom, we wanted to create an environment where clients can experience our craft, understand our styling system and explore what is possible before they think about making a purchase.”

The Floral Atelier runs from July 3-26 in New York. The Bloom Collection launched globally today at maisondesabre.com, before rolling out to stockists including Bloomingdale’s, Nordstrom, Saks Fifth Avenue, Net-a-Porter’s FWRD, Revolve, Farfetch, Le Bon Marché and Ounass.

Idaho’s Most Unusual Listing: A Pair of Medieval Castles Complete With a Dungeon and Drawbridge

Idaho is not a place that’s often associated with Medieval castles, but a pair have just hit the market for $6.25 million.

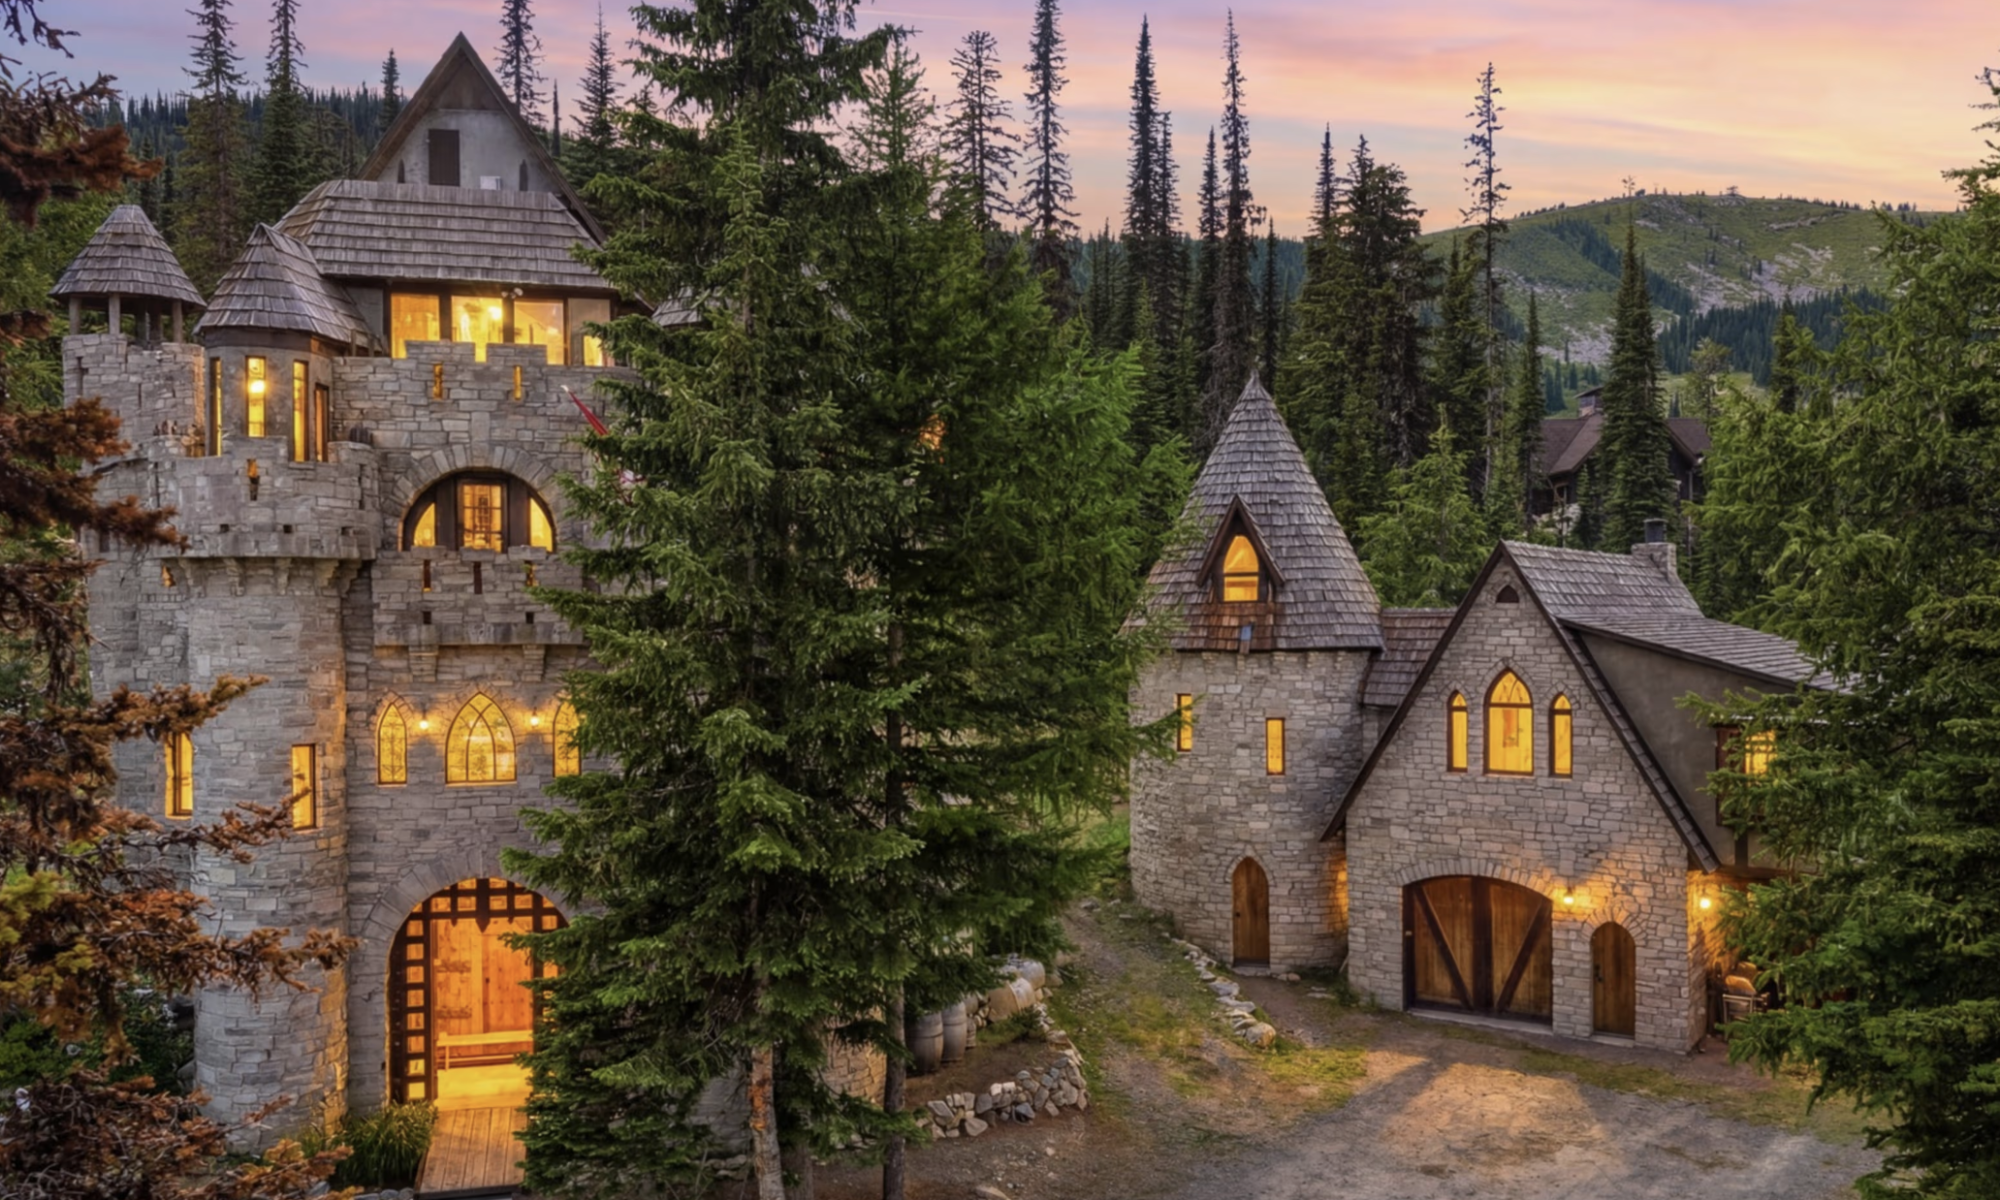
The imposing stone structures have towers, turrets, ramparts, arrow-slit windows and even a drawbridge, and might just be the most authentic-looking castles this side of the Atlantic.

“Who expects to see a castle like this in Idaho?” said listing agent Brenda Burk of Coldwell Banker Schneidmiller Realty, who brought the property to the market last week. They are, she said, “extremely unusual.”

Schweitzer Castle and Château de Melusine, as they’re known, stand within Schweitzer Mountain Resort in the Selkirk Mountains and overlook the nearby mountain resort town of Sandpoint. They take in panoramic views of Lake Pend Oreille, Idaho’s largest lake.

The pair of ski-in/ski-out homes each have three bedrooms, two bathrooms and three stories, Burk explained. They are “so authentic,” she said. “Every single stone was handlaid.”

Schweitzer Castle, she said, wasn’t built for “functionality,” but has been modernized and adapted and now has everything a 21st-century residence requires, along with a dungeon, which for some buyers may also be a requisite.

The chateau, meanwhile, has a hot tub room with mountain views, as well as a garage.

The property is being sold furnished, and will come complete with the hand-carved statues, armor, mounted swords, stained-glass windows and a host of antiques dating to the 15th and 16th centuries.

The owner, an antique collector who couldn’t be reached for comment, “is always looking for that hidden jewel and he found that here,” Burk said.

The next custodian is likely to stem from a varied pool of buyers, Burk said, that would include “the trophy-home buyer, someone who can say ‘I own a castle.’”

The property could also appeal to someone looking for a vacation home, or a multi-generational estate, and beyond that “there’s the dreamers,” she said. “We definitely try to market to people who like Medieval history or maybe do Renaissance fairs.”

The seller “really wants it to go to someone with the same passion.”