The 11 Retirement-Planning Milestones Everyone Over 50 Needs to Know

Retirement saving can seem like a marathon for a young worker just starting out, but turning 50 can make the finish line seem much closer. Fortunately, the final 15 years or so before retirement offer opportunities to supersize savings, penalty-free ways to tap in to accounts or strategies to minimize taxes.

But there are deadlines to meet both before and during retirement to take advantage of these benefits, and missing some of them can be costly.

Catherine Collinson, CEO of the Transamerica Center for Retirement Studies in Los Angeles, says planning around these milestones gives preretirees a chance to create optimal combinations to enrich their golden years. “The dates, the opportunities for saving, and then drawing down savings, they’re all interrelated,” she says.

Here are moves to make at 11 key ages.

Age 50: Catch-up contributions

People who already contribute the maximum to their workplace retirement accounts or individual retirement accounts can top off those amounts with catch-up contributions. This is simply extra money the government lets older workers—some of whom may be behind on retirement savings—put into a retirement account on top of their normal annual contribution limit.

In 2027, employees can contribute up to $25,500, while those over 50 can contribute an additional $8,500 for a total of $34,000. Catch-up contributions are also available for IRAs; in 2027, people over 50 can save an additional $1,100 beyond the current $7,500 limit.

High earners, take note: A rule went into effect this year that requires workers who earned more than $155,000 in wages subject to Social Security taxes in 2026 to funnel their catch-up contributions into Roth accounts. Unlike traditional 401(k) plans that are funded by pretax money, Roth versions aren’t tax-deferred. Instead, any growth on those savings can eventually be withdrawn tax-free.

The Roth mandate doesn’t affect workers who make less than $155,000 in Social Security wages. However, high earners who work at companies without Roth options can’t take advantage of the catch-up contributions in their workplace plans.

Age 55: 401(k) withdrawals, HSA contributions

A longstanding but little-known retirement-law provision is the Rule of 55, says Roger Young, thought leadership director at T. Rowe Price in Owings Mills, Md. The rule allows people to make penalty-free withdrawals directly from their employer 401(k) plan if they leave their jobs—voluntarily or involuntarily—during or after the calendar year they turn 55.

Employees who take advantage of this can avoid the usual 10% penalty for withdrawals from their workplace retirement plans, but they still have to pay taxes on the amount.

The Rule of 55 applies only to withdrawals from workplace plans from a person’s last employer, not from individual retirement accounts or 401(k) accounts from earlier employers.

Turning 55 also means people who have health-savings accounts can contribute an extra $1,000, bringing the total savings opportunity in an HSA to $5,500 for self-only coverage and $10,000 for families.

Age 59½: Penalty-free withdrawals

When near-retirees reach their half-birthday in the year they turn 59, they can tap their qualified retirement accounts—including 401(k)s, 403(b)s, 457s and IRAs—without paying a 10% penalty for early withdrawals. They still must pay taxes on these pretax accounts.

Turning 59½ is key to taking advantage of the rule; withdrawals before that date are still subject to the taxes. For example, someone whose birthday is Jan. 15 must wait until July 15.

To withdraw Roth IRA earnings tax- and penalty-free, savers must be age 59½ and have had the account open for at least five years. For Roth 401(k)s, employees need to be 59½ and meet the five-year rule for their particular employer’s plan. If they are still employed and over age 59½, they’ll need to check if their plan allows in-service distributions.

This age is also a good opportunity to start planning how to reduce taxes in retirement, says John Campbell, head of wealth planning and trust services at Calamos Wealth Management in Chicago. People who have substantial assets in tax-sheltered accounts, for instance, making incremental Roth conversions over several years can make a significant difference on the tax hit when it comes to claiming Medicare benefits at 65 and when required minimum distributions begin.

Ages 60-63: Super catch-up contributions

New retirement rules allow a “super catch-up” window for near-retirees who have already maxed out their standard workplace retirement contributions and the catch-up rules that began at age 50. This enhanced contribution allows workers to save $11,750 extra, for a total saving of $37,250. High-income earners will have to have these contributions sent to their Roth 401(k) if their Social Security-eligible wages are above $155,000.

The super catch-up is only for workplace plans, not IRAs, says Tim Steffen, director of advanced planning at Baird in Milwaukee.

Age 62: Claiming Social Security

People can start claiming their Social Security retirement or spousal benefits at age 62, but doing so can mean a permanent benefit reduction of 30% compared with full retirement age, which is age 67 for anyone born after 1960.

Also, people who claim Social Security before full retirement age while continuing to work will see their benefits subject to an earnings test as the agency withholds $1 in benefits for every $2 earned above an earnings limit of $25,560.

Despite the haircut from claiming early, Transamerica’s Collinson says it is reasonable for those with a shorter life expectancy or if there are immediate cash-flow needs. Her group’s research shows that the median age when people retire is around 63, often for health or employment reasons, or family responsibilities.

Age 63: The Medicare cliff

For near-retirees converting traditional IRAs to Roth IRAs, age 63 becomes important as it is when the two-year lookback window begins for potential surcharges on Medicare Part B, which covers outpatient care, doctor services and preventive tests, and Part D, prescription drug coverage, financial professionals say.

Single Medicare beneficiaries who earn more than $112,000 ($224,000 for a married couple) in modified adjusted gross income in 2025 must pay an “income-related monthly adjustment amount,” or Irmaa, surcharge that kicks in if the income goes over $1 over that threshold, referred to as the Medicare cliff.

Josh McNamara, managing partner at Prime Capital Tax Advisory in Fort Worth, Texas, says people who make large Roth conversions between ages 63 and 64 can trigger Medicare surcharges at age 65. “A lot of people are doing Roth conversions these days and are doing those aggressively. If it’s at age 63 or 64, the income from those conversions” will be in their Medicare premiums, he says.

Age 65: Medicare claiming begins

Unless retirees are already collecting Social Security, they need to specifically enroll in Medicare. The initial enrollment is seven months—three months before a person’s 65th birth month, the birth month and three months after. Don’t delay because retirees can face a permanent late-enrollment penalty of about 10% added to Part B premiums for each 12-month period delay.

Once a retiree enrolls in Medicare, he or she can no longer contribute to an HSA, but HSA funds already saved can be spent tax-free for qualified medical expenses, including Medicare premiums.

Also at age 65, some senior tax filers will receive a $6,000 tax deduction ($12,000 for married couples), on top of the standard deduction, McNamara says. It phases out at $75,000 for singles and $150,000 for married couples. This benefit was included in last year’s tax bill and lasts through 2028, if it isn’t extended.

Age 67: Social Security full retirement age

Claiming Social Security at age 67 unlocks full Social Security benefits and eliminates the earnings-test penalty for working older adults. The next planning decision is to either start taking Social Security at that age, or wait until age 70 to maximize benefits.

Financial pros say to balance your current retirement income needs and investments before deciding.

Age 70: Maximum Social Security payout

Each year a person waits to claim Social Security past full retirement age, their benefits grow by 8% simple interest rate a year. Retirees who wait until age 70 can get a total increase of 24%.

Delayed retirement benefits don’t apply after age 70.

Age 70½: Consider qualified charitable distributions

For charitably minded retirees who are staring at tax-bracket-busting distributions from their IRAs or 401(k)s in a few years, qualified charitable distributions (QCDs) can be a powerful planning tool.

To take advantage of this donation method, retirees must be 70½ or older. They can donate up to $114,000 a year directly from their IRAs to a qualified charity tax-free.

The law also allows a one-time lifetime QCD of up to $57,000 to a charitable remainder trust or a gift annuity, which are vehicles that allow donors to support a charity while receiving income before remaining funds are given to a charity.

Ages 73 and 75: RMDs begin

Required minimum distributions are the minimum amount of money retirees must withdraw from their tax-deferred retirement accounts, and the withdrawal amount is calculated on factors such as account balance, age and life expectancy, based on Internal Revenue Service mortality tables.

Congress passed several new rules in recent years to make RMDs less onerous. First, RMDs don’t start until age 73 for people who were born between 1951 and 1959, or 75 for those born after 1960. Penalties for not taking RMDs were cut in half, to 25% of the amount that should have been withdrawn, down from 50%. Baird’s Steffen says the penalty could fall to 10% if the oversight gets corrected promptly.

Also under the new retirement rules, Roth 401(k) accounts are no longer subject to RMDs, giving them equal treatment with Roth IRAs, which aren’t subject to RMDs.

RMDs and their potential to disrupt retirees’ taxes have become problematic in recent years as a bull market in stocks has boosted the balances of many 401(k)s and IRAs, T. Rowe Price’s Young notes.

“We do see a fair number of people who get surprised at how big their RMD is at 75 or 80 years old, and sometimes that that can bump you into a higher tax bracket,” Young says. “There are a number of planning strategies, but one is to smooth out that taxable income and reduce the balances that that are subject to RMDs.”
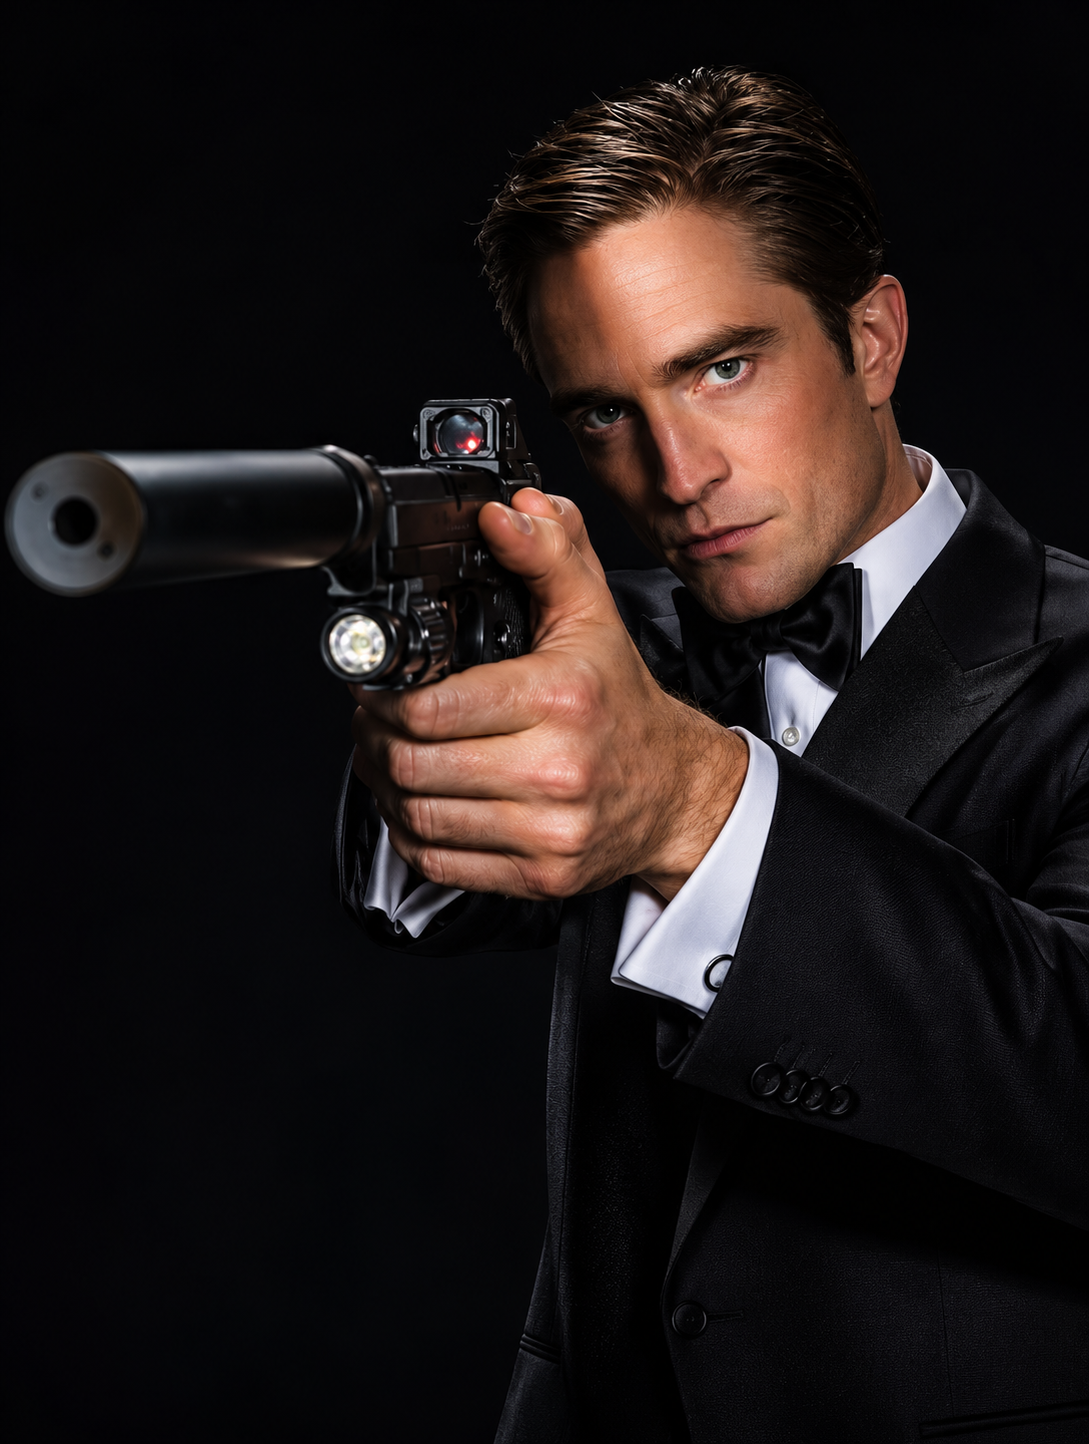
Robert Pattinson Wins the Race to Be the Next James Bond

The next James Bond to serve Britain—and the first selected under new corporate owner Amazon—has been assigned to the mission, bringing closure to a casting race that has gone on for more than a decade.

Robert Pattinson will play Agent 007 starting with the 26th official Bond movie being directed by “Dune” filmmaker Denis Villeneuve. Pattinson’s casting was revealed in an Instagram post which featured him emerging from the shadows, gun in hand, while Bond’s signature theme music played.

In a statement, Pattinson called the role an “honour of a lifetime.”

“To say this role is a dream come true is an understatement,” he said.

Pattinson, 40, first shot to fame as a vampire in the “Twilight” series and his second Batman film is currently in the works. His casting is the clearest signal yet of the strategy Amazon MGM Studios has for one of the most famous movie heroes of all time. As the first major movie star to get picked for the role that has often gone to less famous actors, Pattinson can help bring his existing fan base to Bond along with experience handling blockbuster pressure both on and off screen.

Robert Pattinson starred in the ‘Twilight’ series.
Robert Pattinson starred in the ‘Twilight’ series. Alamy

It’s highly unusual for an actor who has already anchored a tentpole franchise like Batman to also get the call to play Bond. In the past, producers have aimed for their Bonds to be linked primarily to that property.

Pattinson in ‘The Batman.’
Pattinson in ‘The Batman.’ ©Warner Bros/Everett Collection

The studio, formed by Amazon’s 2022 purchase of MGM, needs to reintroduce the international superspy for a new era following a clash over the storied franchise with the producing family who controlled it for more than 60 years. The stalemate over Bond’s direction contributed to the character’s longest-ever absence from the screen.

The issue of who was the right fit for Bond’s tuxedo loomed over the most drawn-out casting cycle yet for the movie series. In recent weeks, rumors gave way to reports by Hollywood trade publications that official screen tests were taking place.

Daniel Craig’s five-film run ended with his Bond perishing in 2021’s ‘No Time to Die.’
Daniel Craig’s five-film run ended with his Bond perishing in 2021’s ‘No Time to Die.’ ©Sony Pictures/Courtesy Everett Collection

These trade reports indicated a narrowing field of actors that included Jack Lowden, who has experience playing a spy in the Apple TV series “Slow Horses”; Josh O’Connor, best known for playing a young Prince Charles in Netflix’s “The Crown”; and Callum Turner, whose credits include “Masters of the Air,” an Apple TV series about World War II pilots.

Then came other trade reports of actors with more established names in the mix: Pattinson and Nicholas Hoult, who is currently Lex Luthor in the latest Superman movies.

Each of these apparent candidates was met with a frenzy of internet discussion over their respective levels of star power, charisma and other qualifications. Yet debate over Craig’s replacement has flared for years around other names, starting more than a decade ago when Idris Elba was among the actors rumored to be in contention, raising the possibility of a Black man playing Bond. (The actor has repeatedly said he only discussed the role with the franchise’s producer.)

The casting issue was the last big obstacle left over from a rough stretch of uncertainty for the franchise. After Amazon bought Metro-Goldwyn-Mayer for $6.5 billion, along with Bond as the crown jewel in the studio’s library, the tech company’s film executives found themselves at odds with the family who still held the power to decide when and how the next Bond film would move forward.

Producers Barbara Broccoli and Michael Wilson, her stepbrother, had steered the property for 30 years, having inherited control from Broccoli’s father, Albert “Cubby” Broccoli, whose Eon Productions first brought Bond to the big screen in 1962’s “Dr. No.”

Barbara Broccoli, who had been at the helm since Pierce Brosnan’s debut in 1995’s “GoldenEye,” was skeptical of the tech company’s qualifications to steer Bond, seeing Amazon as being driven more by data than storytelling, The Wall Street Journal reported. But then, in February 2025, she and Wilson closed a deal that gave Amazon full creative control over Bond.

When it was announced that Amazon had full control, company founder Jeff Bezos posted on social media, “Who’d you pick as the next Bond?”

The deal put the pending Bond movie and the ultimate casting decision fully in the hands of Amazon MGM Studios executives Mike Hopkins and Courtenay Valenti, along with veteran film producers Amy Pascal and David Heyman.

Pattinson is the seventh actor to officially play novelist Ian Fleming’s creation since Sean Connery in 1962. He inherits the role from Daniel Craig, whose five-film run ended with his Bond perishing in 2021’s “No Time to Die.”

Pattinson is one of the industry’s busiest stars. This year alone he played villains in “The Odyssey” and Villeneuve’s upcoming “Dune: Part Three,” and also appeared in smaller, edgier films released by the indie studio A24, “Primetime” and “The Drama.”

While Pattinson got his start as a heartthrob, he’s recently gravitated to stranger roles that show his range and his more unnerving qualities which stand in counter to Bond’s typical self-possession. His unique line readings have recently become the subject of memes.

The London native, whose most famous characters have been American, now faces the challenge of embodying a hero who is iconically British but one over which movie fans worldwide feel ownership.

Villeneuve, who will direct the Bond film being written by “Peaky Blinders” creator Steven Knight, acknowledged the lengthy search in a statement, saying, “We were surrounded by extraordinary talent, but there can only be one 007.”

Demand for Chinese Goods Is Soaring but Economic Momentum Slows at Home

China’s trade surplus surged past $1 trillion last month, but at home, its economy is losing steam.

The world’s second-largest economy weakened on several fronts in October, reflecting the country’s split-screen growth. Soaring exports mask tepid consumer spending, falling investment and a real estate slump with no end in sight.

Retail sales, a gauge of household consumption, rose 0.4% last month from a year ago, slowing from 1.1% in September, according to government data released Monday. Fixed-asset investment fell 8.1% in the first 10 months of the year. Property investment alone dropped nearly 22% during the same period.

“The data continue to depict a two-speed economy,” Société Générale economists Michelle Lam and Wei Yao wrote in a report Monday.

External demand has driven much of China’s economic growth this year. Exports rose 35% from a year earlier in October in dollar-denominated terms, according to official data released last week. The country’s trade surplus for the first 10 months of the year reached $1.04 trillion.

The deluge of exports risks further stoking tensions with Beijing’s trade partners, particularly in Europe, where officials increasingly say that competition from China is hollowing out their local industrial sectors. The European Union and Beijing last month agreed to cap shipments of Chinese hybrid vehicles.

Still, global demand for Chinese goods—especially for tech products that power artificial intelligence—appears to show no signs of slowing. China’s exports of integrated circuits more than doubled in value in the first 10 months of the year, government data show.

That reduces the pressure on Beijing to step up support for the economy. China remains on track to hit its growth target for the year of between 4.5% and 5% gross domestic product growth, making it unlikely Beijing would rush to unleash new stimulus.

“Policymakers are likely to continue doing just enough to meet the growth target,” Macquarie economists Larry Hu and Yuxiao Zhang wrote in a report Monday.

Despite the export momentum, China’s industrial production growth decreased to 4.8% last month, from 5.5% growth in September.

The property market remains a drag on the economy. Home sales fell 14.1% in the January to October period from a year ago, widening from a 13.7% decline in the first nine months.

Meanwhile, China’s headline surveyed urban unemployment rate stood at 5.1% last month, roughly in line with September’s 5.2%.

The Global Economy Looks Vulnerable to an AI Bust

A message from the violent swings in stock markets over the past week: The fallout from an artificial-intelligence bust wouldn’t stop at the U.S.’s shores.

The AI build-out has been an engine of growth not just for the U.S. this year but for the whole global economy. Squeezed by the energy crunch caused by the Iran war, the world has relied heavily on U.S. data-center investment to power otherwise lackluster growth.

Global trade has thrived as Asian economies such as China, Taiwan and South Korea have enjoyed booming exports of computer chips, server racks and electronic equipment to feed ravenous demand for computing power in the U.S.

The Silicon Valley bounty is spreading as other economies join the party. Assembly hubs such as Vietnam and Mexico are seeing exports take off. Malaysia, Thailand and Australia are building data centers of their own. Europe’s industrial giants are supplying the power and cooling systems that make the AI revolution possible.

Yet the anxiety that spread through global markets in the aftermath of the U.S. midterm elections shows this growing dependency on Silicon Valley has a downside.

A slowdown in AI investment would punish exports in economies that in many cases show few other signs of growth. A sustained stock slide would crush mom-and-pop investors all over the world who have piled into technology stocks in anticipation of bumper returns. Overstretched budgets mean governments have limited room to respond with more spending.

Economists calculating what might happen if the pace of investment slows or the AI boom turns to full-blown bust say the only real question is how severe the global consequences will be.

“There is very little that can be done to prevent a global recession should the AI boom collapse,” said Frederic Neumann, chief Asia economist at HSBC in Hong Kong.

Stock markets have been on a wild ride since the Democrats’ victory in the U.S. midterm elections sparked concerns that Congress will hit the brakes on data-center development.

The latest upset in the industry has been the alleged spying scandal engulfing Nvidia, the linchpin of the AI ecosystem because of its deep pockets and advanced chips.

Stocks have clawed back some losses in recent days, moves that suggest many investors think the selloff is overdone. Even so, key stocks and indexes remain well below recent peaks. The tech-heavy Nasdaq index closed Wednesday 8% below its year-to-date high. Japan’s Nikkei index is down 16%, and South Korea’s Kospi, home to major memory-chip maker Samsung Electronics and SK Hynix, is down 43%.

For now, the stock-market gyrations haven’t spilled over into real economic activity, with global data pointing to the AI boom still going strong.

Jensen Huang, CEO of NVIDIA, gives a keynote address on stage in front of screens displaying partner company logos.
Jensen Huang is under scrutiny after an affair with an alleged spy. Sean Gallup/Getty Images

Asian economies are still seeing bumper export growth, with many of the gains driven by surging prices for chips and other hardware. China’s exports were up 35% year-over-year in October, according to figures from data provider CEIC. South Korea’s were up 93%, with Japan, Taiwan, Singapore and others also posting double-digit gains.

Economists at Capital Economics said the export bonanza means global trade is on track for its best spell of annual growth this year since the days of hyperglobalization in the early 1990s, excluding the big rebounds after Covid-19 and the 2008-09 financial crisis.

But the consulting firm warned that as much as 80% of recent export growth has been concentrated in AI-related goods, leaving global trade vulnerable to any change in U.S. spending on data centers. China, South Korea and other major economies are beset by weak consumption, meaning a drop-off in trade would have an outsize hit on growth.

Political and regulatory hurdles could drag on data-center investment. So, too, could rising interest rates or disappointments on earnings if AI firms’ revenues fail to keep up with outlays. The AI splurge already eclipses past infrastructure booms such as the railroads, and even without external pressure it might struggle to maintain that breakneck rate of growth.

As data-center investment slows, “AI capex will turn from a major prop to a drag on world trade,” Marcel Thieliant, head of Asia-Pacific at Capital Economics, said in a report.

Some economists have looked back to the dot-com bubble of the early 2000s as a yardstick to measure the possible costs to the global economy of an AI blowup.

In that episode, U.S. business investment sank and stocks crashed, hurting U.S. consumer spending and crushing imports.

Activists hold signs reading "Stop Data Centers" and "Off Fossil Fuels" during a protest.
Data centers were an issue in the U.S. midterm elections. Michael Nigro/Pacific Press/ZUMA Press

As a share of gross domestic product, U.S. imports of IT-related equipment fell 55% in two years from their mid-2000 peak, according to Oxford Economics—a drop that hit Asian and other economies that were suppliers of the goods. Global trade plummeted, and world growth in 2001 collapsed to just 2%, consistent with a global recession.

The globalized financing of the AI boom would in a bust spread financial pain around the world, adding to the damage from a steep fall in trade. Gaurav Ganguly, head of international economics at Moody’s Analytics in London, said the world would struggle to absorb a sharp AI stock slide on top of an oil shock, tariffs and rising interest rates.

“The result could be a severe economic shock with global recessionary consequences,” he said.

The Parents Suing Schools Because Their Kids Got Bad Grades

When Weiwei Luo saw the report card saying her son needed to work on “cooperating with others,” the Silicon Valley mom demanded it be changed. When the school district declined, she called her lawyer.

What began last fall as a playground spat between third-graders has now escalated into a courtroom brawl: In a lawsuit filed in October, Luo calls the teacher’s comments “inaccurate and unsubstantiated,” and is asking a judge to order the district to rehear her case.

Time was when parents disciplined children for bringing home bad marks. Today, they often take a more adversarial approach, educators say, leaning on teachers and administrators to change grades in disputes that can even spill into court.

Ever since remote learning brought classrooms into living rooms during the pandemic, U.S. parents have grown more involved in and less enchanted with schools, according to numerous surveys. That includes scrutinizing how teachers evaluate their children.

Four in 10 American teachers report facing pressure from moms and dads to change grades, according to a 2024 EdWeek survey of a nationally representative sample of 1,500 educators. Affluent parents, teachers noted, were more likely to complain.

Esther Wojcicki, a retired Palo Alto teacher and author of “How to Raise Successful People,” said parents have a newfound sense of self-righteousness in protecting their children. “Especially if they get a bad grade,” she added, “the parents go to battle for them.”

That pushback is pushing some teachers over the edge. In Nashville, Tenn., Samira Hardcastle, a teacher of the year, became an internet sensation this year when she quit. Her resignation letter accused district officials of fabricating a grade to “appease an irate parent” whose child had repeatedly failed to turn in an art assignment in Hardcastle’s class at John F. Kennedy Middle School.

“There’s no accountability, so they learn that it doesn’t matter what their work ethic is,” Hardcastle told The Wall Street Journal. “That’s going to be a tough lesson when they get into the real world and realize it doesn’t work that way.”

A spokesman for Metropolitan Nashville Public Schools said it wasn’t “accurate to characterize this as the district simply changing a student’s grade at a parent’s request.” Sean Braisted said administrators stepped in to give the student another chance to finish the assignment, and independently graded the project.

Fueling this friction is the narrow path into a top U.S. university, argues Rowena Chiu, a Palo Alto school board member and mother of four. “To get your child into an elite university these days seems more impossible than ever,” she said. “I think that does trickle down into nervousness about a particular grade.”

Takashi Kato poses on stairs.
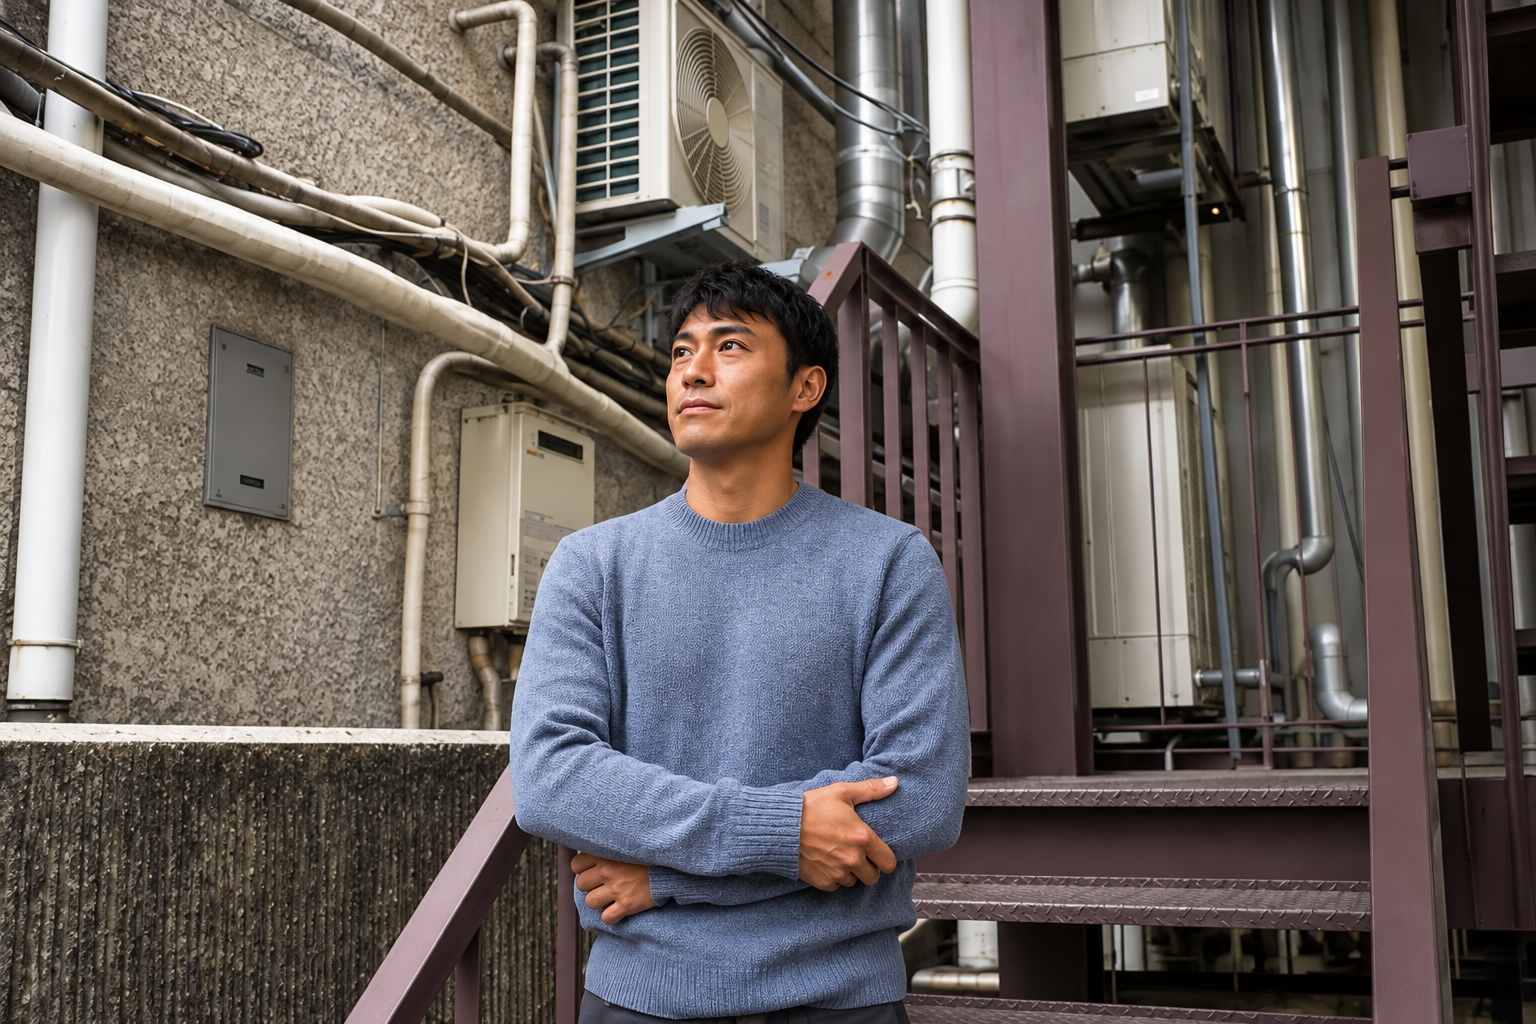
Takashi Kato, shown in 2019, sued his son’s school district over an essay flagged as ‘76% AI.’ Kentaro Takahashi/Bloomberg News

In one recent case, Takashi Kato, the founder and CEO of a Silicon Valley artificial-intelligence startup, sued the Palo Alto Unified School District in federal court after AI-detection software flagged an essay his son turned in as “76% AI.” The tenth-grade English teacher let him redo the assignment, on Arthur Miller’s “The Crucible,” but she gave him a D on the retake, bringing his final grade down to a C.

Kato fought back. He submitted to the district a 1,162-page packet showing the sophomore’s “drafting and revision process,” which he argued proved his son had done nothing wrong, the suit said. The suit said that detection software can be biased against non-native English writers. He offered to accept a B to resolve the dispute.

The district wasn’t persuaded and in March, Kato hired a lawyer. In his lawsuit, he argued that an “academic dishonesty” record could affect college admissions and more. After months of litigation, Kato dropped the suit in September. Kato declined to comment.

“If you’re going to accuse a student of using AI you need to understand the impact it has on the student and give them the proper due process,” said Evan Nelson, Kato’s attorney. “It was never about the grade and it was never about the money, it was all about trying to fix this.”

Lynette White, a spokeswoman for Palo Alto schools, said the district doesn’t comment on litigation, but added there was no settlement.

Also in Palo Alto, the Walter Hays Elementary School strife included a game of tag at recess. A third-grade boy stuck out his tongue at another student who kicked him, and then grew frustrated when his teacher didn’t believe the kick was intentional, according to court filings.

On his report card, the teacher wrote that the boy was “working on his responses to peers when he is frustrated” and “developing his ability to listen to others’ perspectives and collaborate with humility.”

The mom, Luo, hired a lawyer and complained to the school board that the incident didn’t justify the comments. The board disagreed, saying the remarks “reflected the teacher’s observations, were within her competence, were substantiated, and were not misleading,” according to the suit.

But Luo claims the hearing wasn’t fair because her attorney was disconnected from the video call. She didn’t respond to requests for comment and her lawyer declined to comment.

White, the district spokeswoman, said there is a process for parents to challenge grades. “The district follows that process and will respond to the petition in court,” White said.

Japan Spent Record $50 Billion in Single Day to Bolster Yen

Japan spent a record $50 billion in one day during July to prop up the yen, underscoring an aggressive intervention campaign that included rare joint action with the U.S.

Ministry of Finance data on Monday showed that Tokyo bought a total of 15.399 trillion yen, equivalent to $97.16 billion, in July and August. It deployed about half of that on July 30 alone, spending 7.976 trillion yen.

The sum exceeded the amount spent in April and May, reflecting officials’ growing anxiety after the currency tumbled to a four-decade low near 164 against the dollar earlier this year, and highlighting the difficulty of turning the tide against persistent yen weakness.

Japan’s Finance Minister Satsuki Katayama and U.S. Treasury Secretary Scott Bessent confirmed coordinated intervention to support the yen in late July, the first such operation since 1998.

The unusual move initially boosted the yen, but the currency is still hovering around 158.20 against the dollar as growing expectations of further Federal Reserve rate increases reinforce views that the wide U.S.-Japan interest-rate gap is here to stay.

Bessent was outspoken about the yen’s sharp slide during the summer, expressing support for Tokyo’s steps to counter the currency’s undervaluation and noting its role in driving up domestic inflation.

His remarks fueled speculation about faster monetary tightening by the Bank of Japan, which raised interest rates to 1.25% in September and is expected to act again by year’s end.

The central bank has cited the yen’s weakness as one of the major factors affecting Japan’s economic and inflation outlook.

How to Leave Your Career While Keeping the Door Open to a Comeback

Americans are death-gripping their jobs. A lack of options is only part of the reason.

It’s certainly true that opportunities to job hop have waned. The quit rate has been at or below 2% for 14 straight months, according to federal data. We haven’t had a stretch like this in a decade.

But recall that during the “great resignation,” a lot of quitters weren’t leaving for different jobs. Plenty stepped away to travel, start a business or focus on family. And they did it with confidence that they could boomerang back to the same, or similar, roles they left.

Today, that confidence is badly shaken. The disappearing belief that you can return to your previous rung on the career ladder is the other cause of workers’ paralysis.

But some are bold enough to walk away from a plum position, and there is an art to leaving the door open for a career comeback. Some of it is mental, some tactical. If you’re contemplating a break or change, there are strategies to overcome the natural fear you are feeling.

I’ve gone through it myself. I am sweating my way through a version of this concern as I write what is my final “On the Clock” column. I plan to work less and parent more as my wife returns to a full-time office job. After 11 years—and 11 children birthed, adopted or fostered—it’s her turn to come first professionally.

I’m excited for both of us, in no small part because I get to stay at The Wall Street Journal in a different role. I’ll anchor a revamped Careers & Leadership newsletter, coming soon to an email inbox near you. (You can sign up for the newsletter here in advance of the switch.) Still, it isn’t lost on me that the columnist’s role I am leaving is the kind of job that might come along only once in a career.

Sabra Meretab smiling while wearing a beige blazer and a necklace.
Sabra Meretab Wil Reiner/Reiner Photography

Many of you have faced something similar.

“There’s the fear of the musical chairs problem, which is really acute in our culture,” says Sabra Meretab, who was chief of staff of Stripe’s payments engineering division when she quit to travel and write a memoir in 2024. “It’s a really legitimate concern that, if I leave, what are the odds that there is still a chair for me when I return?”

In Meretab’s case, there was. She returned to her former company 18 months later.

Weigh the risk of regret

Not everyone will be so lucky. But the thought of picking up where you left off shouldn’t be top of mind. Instead, think of this: The role you’re in could be a once-in-a-career kind of job. What if the thing tempting you to leave is a once-in-a-lifetime opportunity?

“We fear the irreversibility of leaving and the opportunity cost of that, but we completely overlook the irreversibility of staying and the opportunity costs that are associated with that,” Meretab says.

Entering her 30s, she worried that the window to globe-trot as a freewheeling single might be closing. A career sabbatical would be harder to pull off later if she had a partner and children.

She concluded that she would regret missing her shot at adventure more than she would regret forfeiting a great job, even if she couldn’t get it back.

Understand you’re a catch

It’s hubris to think you are irreplaceable. At the same time, high performers don’t grow on trees.

Jawad Mourabet tries to keep this in mind as he runs his fledgling business, Velto Pickleball Club in Brooklyn, after leaving McKinsey & Co. earlier this year. He told me in March that he was giving himself two years to make it work when we spoke for a column about entrepreneurship.

Jawad Mourabet holding a pickleball paddle at Velto Pickleball Club.
Jawad Mourabet

He reports Velto is profitable, so he isn’t thinking about how to get his old job back. But could he, if he needed or wanted to?

“I actually think I’d be in a better position now to become a partner at McKinsey than if I had stayed,” he says.

This self-assurance is the result of a mindset shift. Like many who vied for and landed a competitive position, Mourabet internalized the sense that he was lucky to be there. Over time, though, he came to recognize his value. Maybe McKinsey was lucky to have him.

He reasons that if he was good enough the first time, he’d likely be good enough a second time—possibly even more so, with firsthand experience running a business.

Meanwhile, his pickleball club is a popular destination for some of his former colleagues. That helps keep those relationships warm.

Keep in touch

And networking, post-exit, is key to keeping your options open, says digital sales executive Shannon Leiro. She met regularly with a mentor when she stepped away for two years to start a family. She also monitored industry trends closely and, when she noticed a major shift, determined she couldn’t afford to prolong her hiatus.

“I was like, ‘Oh, my gosh, I better get back in before I become obsolete,’ ” Leiro says.

Portrait of Chika Uwazie
Chika Uwazie

Chika Uwazie, former chief executive of a technical recruiting startup, thinks she has more runway. She has spent the past few years creating content, including a podcast, newsletter and forthcoming book, “Timeline Grief,” about failing to hit milestones on schedule.

Still, whenever someone reaches out to gauge her interest in returning to the recruiting industry, she makes time for a conversation, even if she doesn’t expect it to go anywhere.

“I always take calls,” Uwazie says. “I think if you’re building your contacts, you can go back. I think the issue is when you are so focused on the new thing that you become disconnected.”

One caution: You don’t want to earn a reputation as someone who leads people on or wastes their time.

But if you are honest about your intentions, peeking back through the door you left open can help ensure it doesn’t slam shut forever.

Apple’s Growth Machine Is Slowing. High Prices Might Not Save It.

The Apple growth and profit machine is wavering, and the boost from price increases might not be enough to keep it going at historic rates. That dials up the pressure on Apple’s new chief executive, John Ternus.

The company saved the bad news for its earnings call, an hour after it posted its results for the September quarter, projecting that for the current quarter its high-margin services business will continue to slow and that its widely watched gross profit margin will continue to fall.

Apple AAPL -1.83%decrease; down pointing triangle shares had been flat in post-close trading but declined as much as 4% after the company made the projections, which fell short of Wall Street estimates.

The impact of high memory costs are weighing even more heavily on the company, Ternus and Apple Chief Financial Officer Kevan Parekh said on the company’s earnings call. Apple has stockpiled cheaper components purchased earlier, but those inventories are dwindling.

When Ternus took over as Apple’s third chief executive of the past 29 years on Sept. 1, he inherited sky-high expectations. The men he followed were among the most successful company leaders in American business history. Steve Jobs revolutionized consumer devices multiple times. Tim Cook expanded Jobs’s creation to spectacular heights.

The expectations are reflected in Apple’s huge valuation. Oppenheimer analyst Martin Yang noted that Apple stock trades at 36 times next year’s expected earnings, a premium to the overall market, even though its earnings are only expected to grow 1%, which is slower than its tech peers.

“We see insufficient upside to justify the premium,” Yang wrote in an investor note, adding that Apple needs to boost iPhone sales growth and turn around its slowing services business to make him more bullish.

Investors have bid up Apple shares because it has been a port in the AI storm—a reliable and capital-efficient business that stands apart from rivals which are spending hundreds of billions of dollars racing to the AI frontier.

While others invest in data centers, Apple has been pouring its own cash into buybacks and dividends. But that safety may be challenged if Ternus can’t speed up Apple’s innovation engine.

Apple’s lagging performance in AI was evident when its new “Siri AI” chatbot arrived this past quarter. Its long-maligned assistant was already stale the day it arrived, surpassed by agents such as Instinct and Muse that can complete multistep tasks for consumers, while Siri still sets kitchen timers.

Apple needs to give people reasons to buy its devices as they get more expensive. The company raised prices across the board last quarter to help offset higher costs. Without compelling new features, a big question is whether consumers will slow the frequency of iPhone upgrades.

The new iPhone Duo appears to be a bright spot. Consumers are scooping up the $1,999 foldable smartphone despite mixed reviews—so many that Apple can’t keep up with demand. Shipping dates jumped out to January soon after the device went on sale, a disappointment for the normally reliable Apple supply chain.

Apple said its revenue grew 12% in the September quarter, slightly ahead of Wall Street’s expectations. Its widely tracked gross profit margin, at 47.9%, also came in just ahead of analyst estimates.

Apple will need to find new growth avenues because a reliable engine during the Cook era—the services business—is slowing. Courts and regulators worldwide have limited Apple’s ability to charge developers big fees to distribute apps through its App Store, the biggest component of the company’s services segment.

One of its most lucrative App Store fee generators has been the ChatGPT app from OpenAI. Around the time Apple accused OpenAI of trade-secret theft this past summer, OpenAI began redirecting potential subscribers to pay via its website instead of the App Store, skirting Apple’s tollbooth.

Apple’s valuation has bumped up against a ceiling in recent weeks. Six times it traded above a $5 trillion market capitalization intraday before finally closing above the threshold, which it has already fallen back below.

News Corp, owner of The Wall Street Journal, has a commercial agreement to supply news through Apple services.

Companies Have a Solution for the Skilled Trade Shortage: More Women

Sammy Cossairt has tried call center work, waiting tables and hoisting concrete. She prefers hoisting concrete.

The 36-year-old tower crane operator in Nashville, Tenn., who works 12-hour shifts, helps lift and move rebar and buckets of concrete from a perch often hundreds of feet in the air. This isn’t what she envisioned when she received a liberal arts associate degree more than a decade ago, but after nearly a decade on the job, she feels at home in her crane.

“I’m out in the sun, making my mark on the world,” said Cossairt, who makes $120,000 a year. “I think more women would love to get in and make men’s money doing this work, if they only knew.”

The skilled trades have long been a boy’s club. But more women are breaking in, drawn by well-paying jobs that are in high demand. To keep them coming, many companies are courting women like Cossairt through new benefits and perks, including paid maternity leave and more flexibility. They are also trying to create a more welcoming work environment while cracking down on off-color jokes and catcalls on male-dominated jobsites.

The federal government tracks female participation in fields such as construction, and installation and repair, which includes jobs such as plumbers, carpenters and auto technicians. As of last year, women made up about 4.4% of those workers. But they have made mostly steady gains, with that figure rising from 2.9% a decade earlier.

At Universal Technical Institute’s campus in Exton, Pa., career services director Katie Yurick said women are enrolling partly because the industry has grown more tech-infused. Automotive technicians can hook up cars to computers for diagnosis, and plenty of in-demand jobs—such as welding and electrical work—can trade as much on brains and attention to detail as brawn.

“These jobs aren’t even dirty jobs anymore,” said Yurick, adding that she has also heard from employers who say they are trying to hire women, believing they possess high maturity levels and are detail-oriented.

UTI’s student body, which spans 17 campuses across the U.S., is now 8% female, quadruple what it was five years ago. In some areas, such as collision repair and auto refinishing, that figure is even higher, at 19%.

A student wearing safety gear in a Universal Technical Institute training program.
A student in a Universal Technical Institute training program. Universal Technical Institute

“Our industry needs this workforce,” said Maja Ericksen, executive vice president at construction company Mortenson, which in 2024 began offering 12 weeks of paid leave for birth mothers in its skilled workforce. More than 10% of Mortenson’s skilled workforce is now female, up from 7% a decade ago.

“There aren’t too many careers you feel are AI-proof, and being in the skilled trades is one that isn’t going away,” Ericksen said.

Women have broadly outperformed men in the labor market in recent years. This partly reflects booming growth in fields that traditionally employ more women, such as healthcare and social assistance, while women also are making inroads in traditionally male-dominated jobs.

Kym Gardner, 39, a project engineer in Charlotte, N.C., said that as a child, she never thought about working in the field. Her mother was a teacher, her father a computer analyst. “No one really talked about it, it wasn’t considered to be a career,” she said. “The expectation was to go to college.”

But in high school, she grew interested in architecture, found a construction mentorship program and quickly fell in love with seeing buildings rise from the ground up. Now the mother of three children, including a 5-month-old, starts her days on site and works remotely in the afternoons—flexibility she said helps give her peace of mind and ensures she doesn’t have to sacrifice her caregiving duties.

Her company, Turner Construction, is growing fast and needs all the workers it can get, said president Abrar Sheriff. The company hit $29 billion in revenue last year and expects around $35 billion this year, fueled in part by work on data centers. More worker flexibility, including creature comforts such as heated and cooled bathrooms with running water on worksites, or regularly cleaned breakrooms, are part of the pitch.

“We need more people to come into our industry,” Sheriff said.

Elsewhere, construction company Skanska has taken steps such as ensuring female employees have correctly sized gloves, helmets and work boots, rather than forcing them to make do with male-sized gear. Deila Ray, who spent a decade as a pipe welder and now teaches the trade in high school, said she had to shrink her own gloves with fire when she started in the industry.

Skanska this year also started mandating inclusivity for all its team leaders, encouraging them to be more aware of different workers’ needs, said Ayesha Adams, who joined Skanska in 2023 as its inaugural director of culture and engagement.

“You can get people all day, but how do you keep them here?” Adams said.

Some states are trying to make work in the trades more accommodating for women. Both Washington and Illinois, for example, have in the last few years passed laws requiring nursing rooms for mothers on construction sites, as well as refrigerators to store breast milk, flexible break schedules and access to water for cleaning.

Tower crane operator Sammy Cossairt inside the cab of a crane.
Cossairt works 12-hour shifts, helping lift and move rebar and concrete. Travis Harakal/Maxim Crane Works

Construction companies are also tackling another issue: workplace harassment. At Turner, senior leaders there get on a call within four hours of any incident being reported. In one recent case in Texas, a subcontractor’s entire project crew of around a dozen men were replaced when that company couldn’t identify who had written derogatory graffiti about female employees, said Sheriff, Turner’s president.

Part of the challenge is that it doesn’t take aggressive comments to make a jobsite feel hostile, said Rebecca Heustess, 42, a tile foreman who makes $65,000 a year in Henry, S.D. Even after 20 years in the trades, she said she regularly encounters men who patronize her or ignore her instructions.

Still, she said she has thick skin and that the jobsite culture has slowly improved. She also loves the work.

“When I leave a job, it’s this beautiful shiny sparkly project that I know will be there for years to come,” Heustess said. “It’s super fulfilling.”

The Beleaguered Chip Sellers Getting Their Revenge on Apple

During a ride in a Southern California desert, sales executive Scott Nelson stopped his dirt bike, pulled out a rifle and shot his old iPod.

Nelson sold flash storage to Apple AAPL -0.94%decrease; down pointing triangle and hated feeling like he always got the worst end of the deal. His Japan-based manufacturer, Kioxia, had little leverage. Apple was the world’s biggest buyer of flash—the chips in iPhones that store photos, music and apps—and used its position to squeeze every cent from suppliers. Apple bullied flash makers into opening their books so it could monitor sales, making sure no one else got a better deal.

Kioxia and other flash makers stewed as Apple paid them pennies for flash storage that the iPhone maker resold to customers for dollars. The disparity in bargaining power had galled Nelson, who used Android phones in protest.

Nelson kept the broken pieces of his iPod, the first Apple device to use flash. They sit on his desk and hold a special reverence now that the tables have turned.

In the past year, demand by AI hyperscalers has quintupled prices for flash, according to research firm TechInsights, opening a new era for Kioxia and other suppliers. Two years ago, Apple bought nearly twice the flash storage of Microsoft, Amazon, Meta and Google combined, according to TechInsights estimates. Hyperscalers are now buying double Apple’s share.

Flash memory suppliers and their sales teams privately expressed their glee at Apple’s comeuppance during chitchat at the industry’s largest conference this summer in Santa Clara, Calif. AI deals have given Kioxia sales executives and other flash suppliers new leverage to charge Apple higher prices.

Meta, Microsoft and Amazon signed contracts with Kioxia this year to secure long-term supply by committing to higher prices. The contracts protect Kioxia’s profits if the market turns. The company declined to comment.

Hyperscalers can afford to pay more. Flash storage is a smaller part of building a data center than making an iPhone, and accounting rules allow companies to spread the cost over years.

Apple is expected to spend $25 billion on flash storage this year for about the same amount it bought for $6 billion in 2025, according to estimates by TechInsights. Tim Cook, Apple’s executive chairman, compared escalating memory chip prices to a “100-year flood.”

Yet Apple had ignored analysts’ warnings and was caught off guard, said people familiar with the company’s procurement practices.

Company executives believed they knew the market better than anyone else, the people said. Flash that cost $68 a gigabyte in 2005 had fallen to a nickel by 2023. Now, demand by the AI industry has lifted the price to more than 30 cents a gigabyte, a 550% jump, threatening Apple’s steep profit margins from selling extra storage.

Buyers of the iPhone 17 Pro paid Apple $200 last year for double the storage of its 256-gigabyte base model. The extra storage at the time cost Apple $15 and has since shot up to $66, according to an analysis by The Wall Street Journal.

Storage upgrades for iPhone 17 Pro (2025) versus iPhone 18 Pro (2026)

“Apple has historically driven a very hard bargain with memory suppliers,” said Walt Coon, an analyst at TechInsights. “And there’s no shortage of satisfaction among suppliers now that the balance of power is shifting.”

“We’ve worked with many of our suppliers for decades, and we deeply value their partnership over the years,” Apple said in statement. “We look forward to continuing our important work together.”

A buyer at the Apple store on Fifth Avenue in New York City last month.
A buyer at the Apple store on Fifth Avenue in New York City last month. Vanessa Carvalho/ZUMA Press

Apple recorded an average gross profit of more than 80 cents for every dollar it charged iPhone and iPad buyers for extra storage since it first released those devices through 2025, the Journal found. For Mac computers sold since 2010, it averaged nearly 80 cents.

In recent months, Apple raised prices for nearly all of its products. Prices rose an average of 13% for iPhones, an increase that included older models which typically get a price cut.

Price, change from Fall 2025 to 2026

The question for Apple is whether consumers will react to the higher prices by keeping their iPhones longer or whether they will continue to buy at their usual pace. For flash-storage makers, the question is when—or if—Apple will regain its flash-market leverage.

“It’s been a love-hate relationship between Apple and the flash industry,” said Mark Newman, an analyst with Bernstein Research. Apple has sustained the manufacturers for years, he said, but its power to cap prices, while beneficial to shareholders, left suppliers feeling “screwed.”

Commitment-phobe

In 2001, engineers at Kioxia, then called Toshiba, showed two Apple executives a 1.8-inch-diameter, 5-gigabyte hard drive they had developed but didn’t yet know what to do with.